Part I: elections and other information
Lines 1 to 3 hold three elections, line 4 covers the foreign economic process requirements and the $5 million exception, and line 5 records the business activity code, product line and reporting basis.
8873
Extraterritorial Income Exclusion
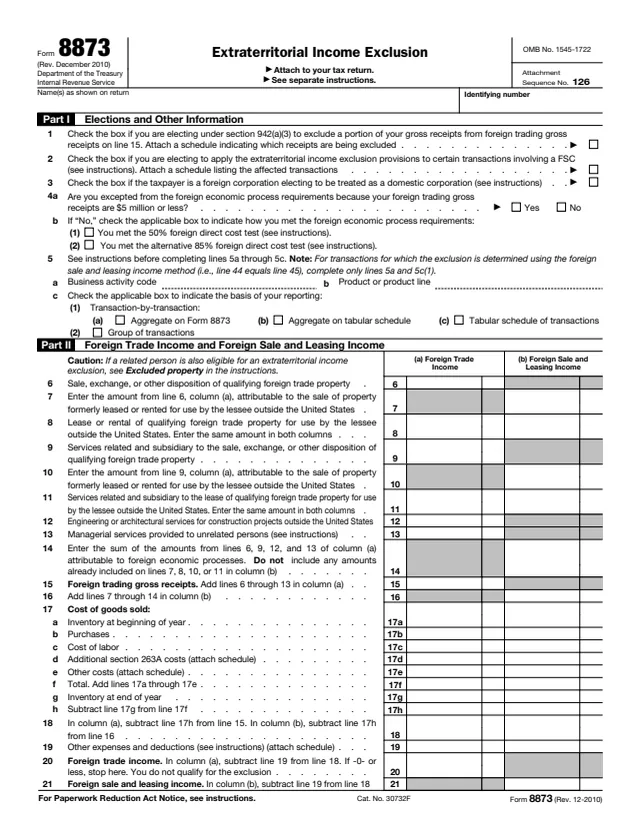
Form 8873, Extraterritorial Income Exclusion, is used to figure the amount of extraterritorial income excluded from gross income for the tax year. The IRS says to attach the form to your income tax return, and the instructions note that the amount figured on the form is net of the disallowed deductions.
The instructions define extraterritorial income as gross income attributable to foreign trading gross receipts. The taxpayer reports all of it on the tax return, then uses Form 8873 to calculate the exclusion for the part that is qualifying foreign trade income.
The instructions also say the American Jobs Creation Act of 2004 repealed the ETI exclusion provisions generally for transactions after 2004, subject to transition rules, and that the binding contract exception was repealed for tax years beginning after May 17, 2006. The current revision of the form is dated December 2010. You can fill out Form 8873 free in your browser on this page and download it without an account.
Lines 1 to 3 hold three elections, line 4 covers the foreign economic process requirements and the $5 million exception, and line 5 records the business activity code, product line and reporting basis.
Lines 6 to 21 list foreign trading gross receipts by type in column (a) and foreign sale and leasing income in column (b), then subtract cost of goods sold and other expenses.
Lines 22 to 36 apply the marginal costing method in three sections. The form says to skip Part III if marginal costing is not used.
Lines 37 to 44 apply 15% of foreign trade income, 1.2% of foreign trading gross receipts and 30% of foreign sale and leasing income. Line 45 takes the greatest of lines 33, 36, 38, 42 or 44.
Lines 46 to 51 adjust for disallowed deductions and reductions for international boycott operations, illegal bribes and kickbacks. Line 52 is the extraterritorial income exclusion.
Check any election that applies and attach the statement the instructions describe. On line 4a, answer whether foreign trading gross receipts are $5 million or less. If not, check the 50% or 85% foreign direct cost test on line 4b.
Enter the six-digit business activity code from the tax return instructions, the product or product line, and check the reporting basis: transaction-by-transaction or group of transactions.
Enter foreign trading gross receipts by type, compute cost of goods sold on lines 17a to 17h, and enter other expenses on line 19 with an attached statement. The form says to stop if line 20 is zero or less.
The instructions say marginal costing takes into account only direct production costs. Complete it to see whether that method helps, or skip to Part IV.
Work through the three methods and enter the greatest on line 45, unless using the alternative computation the instructions describe. Enter any line 50 reduction, then figure line 52.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. The instructions say the amount on line 52 is an exclusion, not a deduction, but is included on the "Other deductions" or "Other expenses" line of the return or schedule.
On Schedule C (Form 1040), the instructions say to enter "Extraterritorial income exclusion from Form 8873" in Part V. On Schedule E (Form 1040), enter "Form 8873" on the "Other" line under Expenses in Part I.
The instructions say to include the amount on the "Other deductions" line of Form 1120.
A filer reporting on a tabular schedule enters only the name and identifying number on one Form 8873. The instructions say the schedule is in spreadsheet or similar format, with columns matching each line and totals.
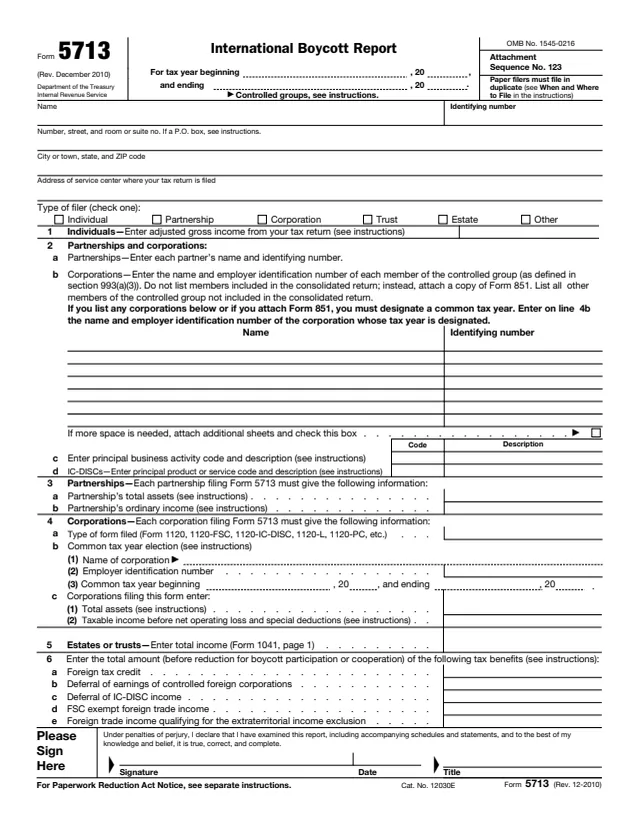
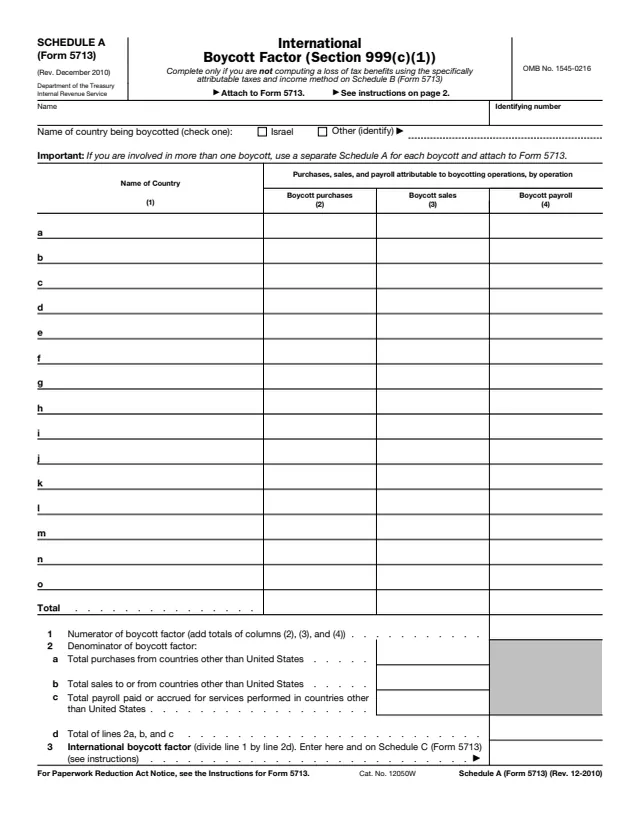
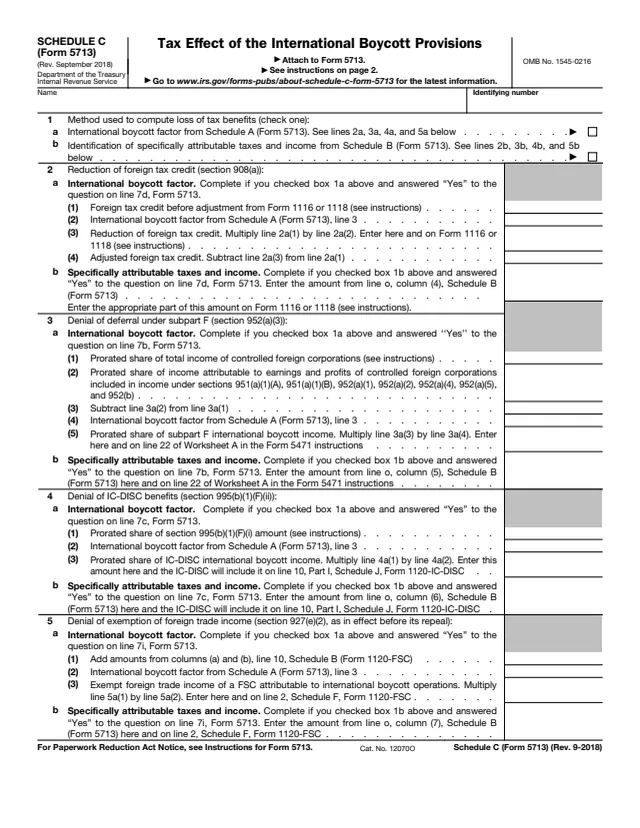
For line 50, the instructions point to Form 5713. Filers of Form 5713 complete Schedules A and C (Form 5713) and enter the amount from Schedule C, line 6c.
5713
383 fields, 4 pages
5713
74 fields, 2 pages
5713
26 fields, 2 pages

1120
481 fields, 6 pages
1040
105 fields, 2 pages
1040
185 fields, 2 pages
The form is attached to the income tax return of the taxpayer claiming the exclusion. The instructions describe which taxpayers and transactions the pre-repeal rules covered.
No tool matches that search.
The instructions say the American Jobs Creation Act of 2004 repealed the ETI exclusion provisions generally for transactions after 2004, subject to transition rules. They describe claims for transactions before 2005 or under a qualifying binding contract.
The instructions define it as the gross income of the taxpayer attributable to foreign trading gross receipts. Form 8873 calculates the exclusion for the part that is qualifying foreign trade income.
The instructions say the foreign economic process requirements do not apply to taxpayers whose foreign trading gross receipts for the tax year are $5 million or less. All related persons are treated as one taxpayer for this limit.
Only if the marginal costing method is used. The form says that if you are not using marginal costing, skip Part III and go to Part IV.
The instructions say to include it on the "Other deductions" or "Other expenses" line of the tax return or schedule, even though it is an exclusion from income and not a deduction.
For line 50. The instructions say operations in or related to a boycotting country, or participation in an international boycott, may reduce the exclusion, and point to the Form 5713 instructions for details.