Header and boycotted country
Name, identifying number, and the country being boycotted: Israel, or Other with a space to identify it.
5713
International Boycott Factor (Section 999(c)(1))
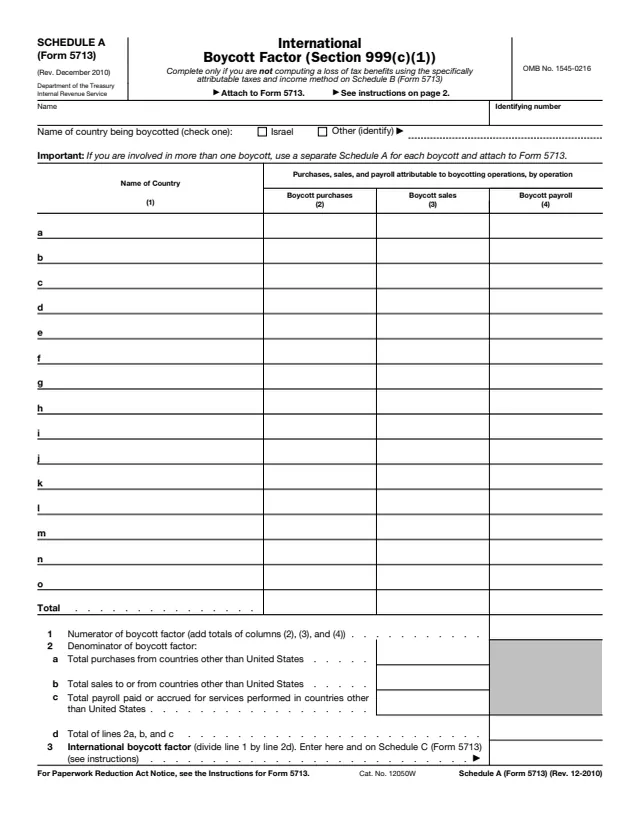
Schedule A (Form 5713) is used to figure the international boycott factor under section 999(c)(1). The factor compares boycott purchases, boycott sales and boycott payroll with all purchases, sales and payroll related to countries other than the United States. It is one of two ways to figure the loss of tax benefits for participating in or cooperating with an international boycott.
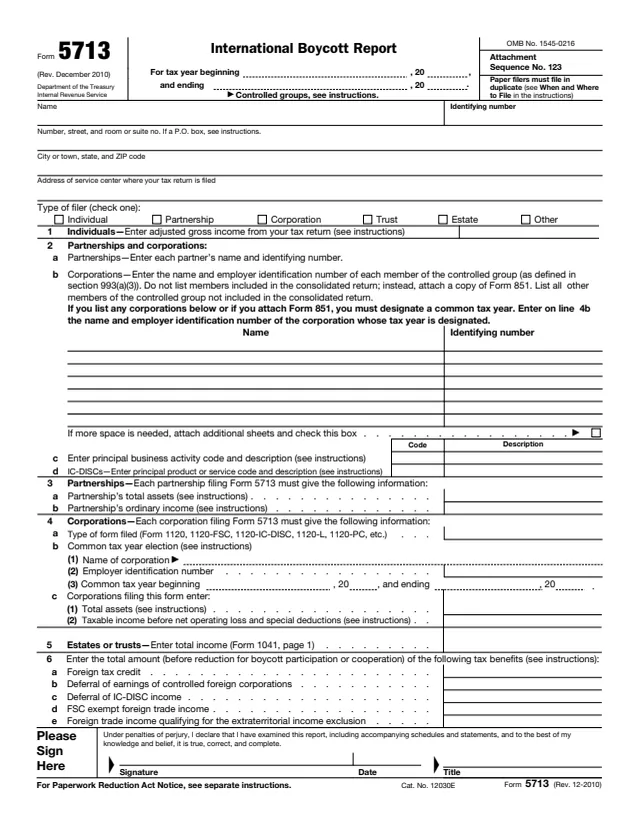
The schedule says to complete it only if the loss of tax benefits is not being figured with the specifically attributable taxes and income method on Schedule B (Form 5713). Its instructions say the international boycott factor is the method used to figure the reduction to foreign trade income qualifying for the extraterritorial income exclusion. The schedule is attached to Form 5713, International Boycott Report, which the IRS says U.S. persons file.
You can fill out Schedule A (Form 5713) free in your browser on this page and download the result without an account.
Name, identifying number, and the country being boycotted: Israel, or Other with a space to identify it.
Purchases, sales and payroll attributable to boycotting operations, by operation: name of country, boycott purchases, boycott sales and boycott payroll, with a total row.
The numerator of the boycott factor, the sum of the totals of columns (2), (3) and (4).
Total purchases from, sales to or from, and payroll for services performed in countries other than the United States, added on line 2d.
The international boycott factor, line 1 divided by line 2d, which is also entered on Schedule C (Form 5713).
Enter the name and identifying number, and check Israel or Other for the country being boycotted, identifying it if Other.
Enter the country that requires participation in or cooperation with the boycott as a condition of doing business there. The instructions say this is not necessarily the country where the operation takes place.
Show all boycott purchases, sales and payroll from one operation on one line: purchases from boycotting countries, sales to or from them, and payroll for services performed in them.
Add the totals of columns (2), (3) and (4). The instructions say not to include amounts for operations for which you rebutted the presumption of boycott participation or cooperation.
Enter all purchases, sales and payroll in or related to all countries other than the United States. Here the instructions say to include amounts for operations where the presumption was rebutted.
Divide line 1 by line 2d and enter the factor on the Schedule C (Form 5713) line that matches the tax benefit affected. Partnerships skip this line.
The instructions say to compute a separate boycott factor and schedule for each international boycott, including your own operations and, if applicable, those of partnerships, trusts and members of your controlled group.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 5713. It is not filed on its own.
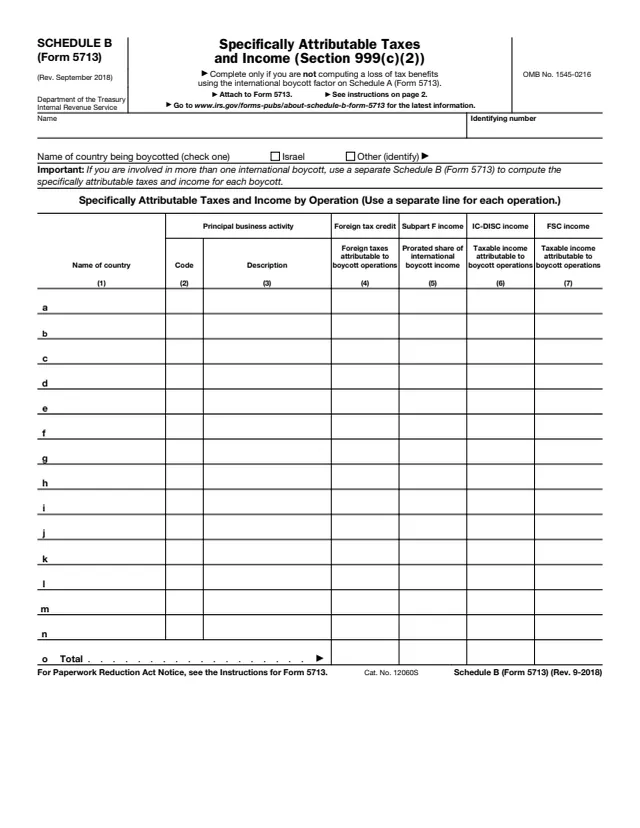
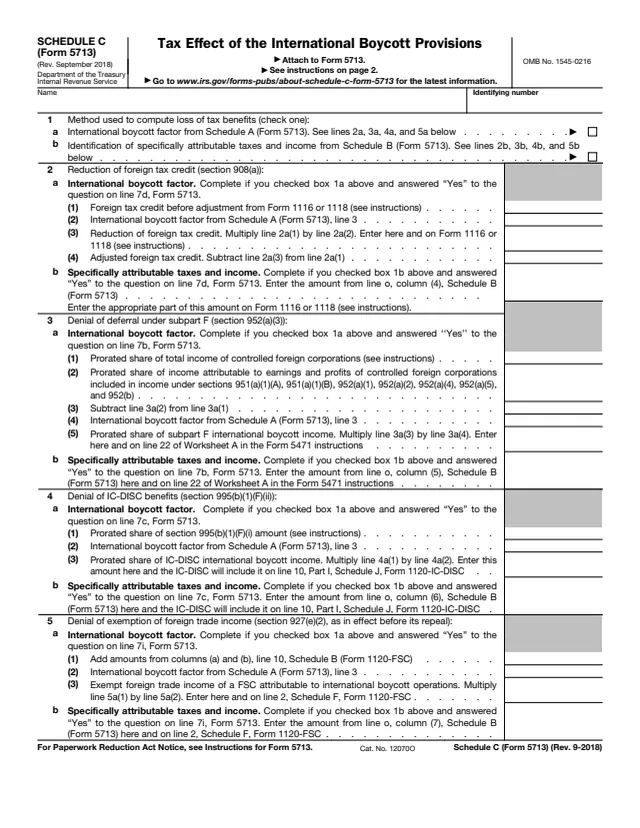
To figure the loss of tax benefits other than the extraterritorial income reduction, the instructions say either the boycott factor (Schedule A) or specifically attributable taxes and income (Schedule B) may be used.
The instructions list line 2a(2) for a reduced foreign tax credit, line 3a(4) for subpart F income, line 4a(2) for IC-DISC income, line 5a(2) for FSC foreign trade income and line 6b for the extraterritorial income exclusion.
All operations in a boycotting country are considered boycott operations unless the presumption is rebutted. Operations outside a boycotting country count if they are connected to the boycott.
The instructions say the Secretary maintains a list of countries that require participation in or cooperation with an international boycott, and point to the Instructions for Form 5713 for the current list.
The instructions say to complete Schedule A if you participated in or cooperated with an international boycott and you are using the international boycott factor to figure the loss of tax benefits.
No tool matches that search.
The instructions say to complete it if you participated in or cooperated with an international boycott and are using the international boycott factor to figure the loss of tax benefits.
Schedule A figures a boycott factor from purchases, sales and payroll. Schedule B specifically attributes taxes and income by operation. Schedule A says to complete it only if Schedule B's method is not being used.
Line 1, the total of boycott purchases, sales and payroll, is divided by line 2d, the total of purchases, sales and payroll related to countries other than the United States.
The instructions say amounts for operations for which you rebutted the presumption of boycott participation or cooperation are left out of line 1, but included in line 2.
No. Partnerships complete lines a through o, the column totals and line 2, and give this information to all partners so they can compute their own factor.
The schedule says to use a separate Schedule A for each boycott and attach each one to Form 5713.