5472

Information Return of a 25% Foreign-Owned U.S. Corporation or a Foreign Corporation Engaged in a U.S. Trade or Business (Under Sections 6038A and 6038C of the Internal Revenue Code)

Agency
IRS
Revision
Rev. December 2023
Fillable fields
143
Pages
3
Official source
IRS form page
Checked
October 21, 2026
Fill 5472 online
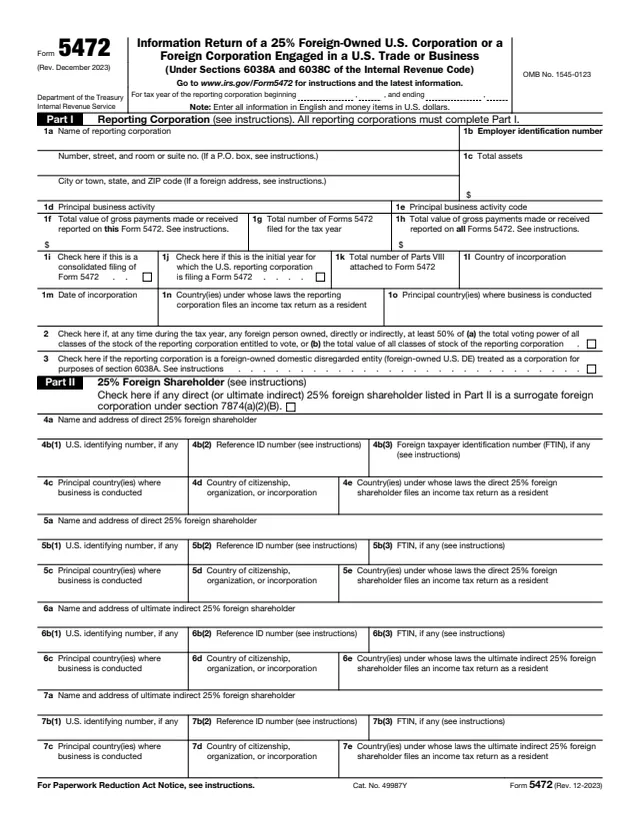
Page 1 of form 5472

Form 5472: Information Return of a 25% Foreign-Owned U.S. Corporation

Form 5472, Information Return of a 25% Foreign-Owned U.S. Corporation or a Foreign Corporation Engaged in a U.S. Trade or Business, is filed under sections 6038A and 6038C of the Internal Revenue Code. The instructions say it is used to provide information when reportable transactions occur during the tax year of a reporting corporation with a foreign or domestic related party.

The instructions define a reporting corporation as either a 25% foreign-owned U.S. corporation, including a foreign-owned U.S. disregarded entity (DE), or a foreign corporation engaged in a trade or business within the United States. A separate Form 5472 is filed for each related party the corporation had a reportable transaction with.

The form says to enter all information in English and money items in U.S. dollars. It is attached to the reporting corporation's income tax return, and a foreign-owned U.S. DE attaches it to a pro forma Form 1120. This page covers the December 2023 revision. You can fill out the PDF free in your browser on this page and download it without an account.

What's on Form 5472

Part I: Reporting Corporation

Name, EIN, address, total assets, business activity and code, gross payments reported, number of Forms 5472 filed, country and date of incorporation, and checkboxes for 50% foreign ownership and foreign-owned U.S. DE status.


Part II: 25% Foreign Shareholder

Up to two direct and two ultimate indirect 25% foreign shareholders, each with identifying numbers, a reference ID number, an FTIN and countries, plus a box for a surrogate foreign corporation.

Part III: Related Party

Whether the related party is a foreign or U.S. person, then its name, address, identifying numbers, business activity, relationship and countries.

Part IV: Monetary Transactions

Amounts received on lines 9 to 22 and amounts paid on lines 23 to 36, such as sales, rents, royalties, services, commissions, loans, interest and insurance premiums.

Parts V and VI: Other Transactions

Part V covers other transactions of a foreign-owned U.S. DE, such as formation, contributions and distributions. Part VI covers nonmonetary and less-than-full consideration transactions. Both are described on an attached sheet.

Parts VII to IX: Additional Information

Part VII asks about imports, cost sharing, section 267A, FDII, safe-haven loan rates and covered debt. Part VIII covers each cost sharing arrangement. Part IX covers base erosion payments under section 59A.

How to fill out Form 5472

  1. 1

    Tax year and Part I

    Enter the tax year, then Part I. The instructions say domestic corporations take total assets on line 1c from Form 1120, page 1, item D, and foreign corporations from Form 1120-F, Schedule L, line 17, column (d).

  2. 2

    Lines 1f to 1k

    Line 1f is the total value of foreign related party transactions on this form and line 1h the total on all Forms 5472. Line 1g counts the forms filed, one per related party, and line 1k counts the Parts VIII attached.

  3. 3

    Part II

    The instructions say only 25% foreign-owned U.S. corporations, including foreign-owned U.S. DEs, complete Part II. A reference ID number is needed only when no U.S. identifying number is entered, and is alphanumeric with up to 50 characters.

  4. 4

    Part III

    The instructions say all filers complete Part III, even if the related party is already listed in Part II as a 25% foreign shareholder.

  5. 5

    Part IV

    Enter amounts in U.S. dollars and attach a schedule of the exchange rates used. The instructions allow reasonable estimates of at least 75% but not more than 125% of the actual amount, and amounts not over a total of $50,000 may be reported as "$50,000 or less."

  6. 6

    Parts V to IX

    Describe Part V and Part VI transactions on attached sheets, answer the Part VII questions, complete a separate Part VIII for each cost sharing arrangement, and enter the section 59A amounts in Part IX.

Why fill Form 5472 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

When and where to file, and penalties

When and where to file

The instructions say to file Form 5472 as an attachment to the reporting corporation's income tax return by the due date, including extensions, of that return.

Foreign-owned U.S. DEs

They write "Foreign-owned U.S. DE" across the top of a pro forma Form 1120 and file by fax (300 DPI or higher) to 855-887-7737, or by mail to Internal Revenue Service, 1973 Rulon White Blvd, M/S 6112 Attn: PIN Unit, Ogden, UT 84201. The instructions say they cannot file Form 5472 electronically.

Extension for a DE

The instructions say a foreign-owned U.S. DE can request more time with Form 7004, filed by the regular due date, entering the code for Form 1120 and faxing or mailing it to the same number or address.

Penalties

The instructions list a $25,000 penalty for failing to file Form 5472 when due and in the manner prescribed, or failing to keep required records. A substantially incomplete form counts as a failure to file. An additional $25,000 can apply if the failure continues more than 90 days after IRS notification.

Records

The instructions say a reporting corporation keeps the permanent books of account or records required by section 6001, including records relevant to transactions with related parties.

Accrual method

A reporting corporation using an accrual method uses accrued payments and accrued receipts to figure the amount on each line.

Who files Form 5472?

  • 25% foreign-owned U.S. corporations

    The instructions say a corporation is 25% foreign owned if it has at least one direct or indirect 25% foreign shareholder at any time during the tax year, measured by voting power or value.

  • Foreign corporations in a U.S. business

    A foreign corporation engaged in a trade or business within the United States is also a reporting corporation under the instructions.

  • Foreign-owned U.S. disregarded entities

    The instructions describe a domestic DE wholly owned by a foreign person, treated as a corporation for the limited purposes of section 6038A. It files a pro forma Form 1120 with Form 5472 attached and checks line 3.

  • Consolidated groups

    The instructions say a member of a group filing a consolidated return may file a U.S. consolidated Form 5472, with the common parent attaching a schedule of the members joining in.

  • Exceptions

    The instructions list exceptions, such as no reportable transactions of the types in Parts IV and VI (and Part V for a DE), or a U.S. person that controls the foreign related corporation filing Form 5471 with Schedule M.

The About Form 5472 page says corporations file it. The instructions say a reporting corporation generally files Form 5472 if it had a reportable transaction with a foreign or domestic related party.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 5472

What is a reporting corporation?

The instructions say it is either a 25% foreign-owned U.S. corporation, including a foreign-owned U.S. DE, or a foreign corporation engaged in a trade or business within the United States.

Does a foreign-owned disregarded entity file Form 5472?

The instructions say a foreign-owned U.S. DE, a domestic DE wholly owned by a foreign person, files a pro forma Form 1120 with Form 5472 attached by the due date, including extensions, of that Form 1120.

Is one Form 5472 enough for several related parties?

No. The instructions say to file a separate Form 5472 for each foreign or U.S. person who is a related party with which the reporting corporation had a reportable transaction.

Can Form 5472 be filed electronically?

A corporation that e-files its income tax return can see that return's instructions for e-filing. The instructions say a foreign-owned U.S. DE cannot file Form 5472 electronically and uses the fax number or mailing address given.

What is the penalty for not filing?

The instructions list a $25,000 penalty on a reporting corporation that fails to file when due and in the manner prescribed. If the failure continues more than 90 days after IRS notification, an additional $25,000 applies for each related party for each 30-day period, or part of one, that it continues.

What language and currency does the form use?

The form says to enter all information in English and money items in U.S. dollars.