Header boxes
Four boxes (non-consolidated return, consolidated return (Form 1120-PC only), mixed 1120/L/PC group, dormant subsidiaries schedule attached), then the name of the corporation (the common parent, if consolidated) and EIN.
1120-PC Sch. M-3
Net Income (Loss) Reconciliation for U.S. Property and Casualty Insurance Companies With Total Assets of $10 Million or More
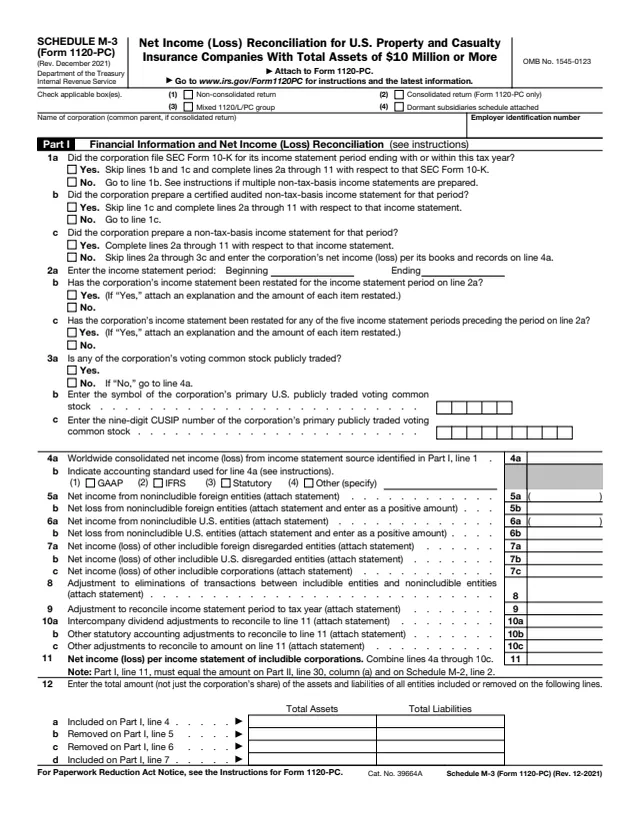
Schedule M-3 (Form 1120-PC) is the Net Income (Loss) Reconciliation for U.S. Property and Casualty Insurance Companies With Total Assets of $10 Million or More. The About Form 1120-PC page says it is used to reconcile financial statement net income (loss) with taxable income reported on Form 1120-PC. The instructions say Part I reconciles net income (loss) on line 4a to net income (loss) for U.S. taxable income purposes on line 11, and Parts II and III reconcile line 11 to the subtotal on Form 1120-PC, Schedule A, line 35 (or Schedule B, line 19, if applicable).
For property and casualty insurance companies that prepare an annual statement, the instructions say financial statement net income (loss) should be reported on the statutory basis on Part I, line 11. The schedule says to attach it to Form 1120-PC.
This page hosts the December 2021 revision; the instructions linked here were revised in December 2025. You can fill it out free in your browser on this page and download the result without an account.
Four boxes (non-consolidated return, consolidated return (Form 1120-PC only), mixed 1120/L/PC group, dormant subsidiaries schedule attached), then the name of the corporation (the common parent, if consolidated) and EIN.
Which income statement is used (SEC Form 10-K, certified audited, other non-tax-basis, or books and records), the income statement period, any restatements, and the stock symbol and CUSIP number if voting common stock is publicly traded.
Worldwide consolidated net income (loss) with the accounting standard (GAAP, IFRS, statutory or other), then adjustments. The form notes that line 11 equals Part II, line 30, column (a), and Schedule M-2, line 2.
Total assets and total liabilities (not just the corporation's share) of all entities included or removed on Part I, lines 4, 5, 6 and 7.
Lines 1 to 30 in four columns: income statement, temporary difference, permanent difference and tax return. Insurance lines include premium income (attach statement), and line 13 interest income says to attach Form 8916-A.
Lines 1 to 40, including write-off of premium receivables, guarantee fund assessments, discounting of unpaid losses (section 846), reduction of loss deduction (section 832(b)(5)(B)) and interest expense (attach Form 8916-A).
The instructions say Part I is completed for any tax year the company files Schedule M-3. Check box (1), (2) or (3), as applicable, and box (4) if a dormant subsidiaries schedule is attached.
If SEC Form 10-K was filed for the period, check Yes on line 1a and skip lines 1b and 1c. If line 1c is No, the form says to skip lines 2a through 3c and enter net income (loss) per books and records on line 4a.
Column (a) is the amount included on Part I, line 11, and column (d) the amount in the subtotal on Form 1120-PC, Schedule A, line 35 (or Schedule B, line 19). The instructions say differences are split into temporary in column (b) and permanent in column (c), following SAP when statements use it.
Column (a) is earned premiums included in Part I, line 11, and column (d) earned premiums on Schedule A, line 35. Attach a statement of amounts from changes in items such as advanced premiums, earned but unbilled premiums and retrospective premium accruals.
Column (a) is the change in liability for unpaid losses and loss adjustment expense net of reinsurance, and column (d) the change in the same liability valued for tax purposes. Paid losses are not included. A statement shows the section 846 discounting at the start and end of the year.
Report the proration adjustment required by section 832(b)(5)(B) as a negative amount in column (d), with amounts in columns (b) and (c) as appropriate. The instructions say not to enter an amount in column (a).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 1120-PC. The instructions give the address for Form 1120-PC and all attachments: Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0012.
A company filing Schedule M-3 checks Item A, box 3, on Form 1120-PC, page 1, whether the schedule is required or voluntary, and does not file Schedule M-1.
The instructions say total assets on Schedule L, line 15, column (d), equal the company's total assets on the last day of the tax year, and Schedule M-2, line 2, equals Schedule M-3, Part I, line 11.
For U.S. consolidated tax returns, the instructions say to file supporting statements for each includible corporation. A statement or explanation may be attached to any line even if none is required.
The About Form 1120-PC page lists a notice dated 20-FEB-2026: no penalty for not electronically filing Forms 1120-REIT, 1120-RIC, 1120-L, and 1120-PC for 2025.
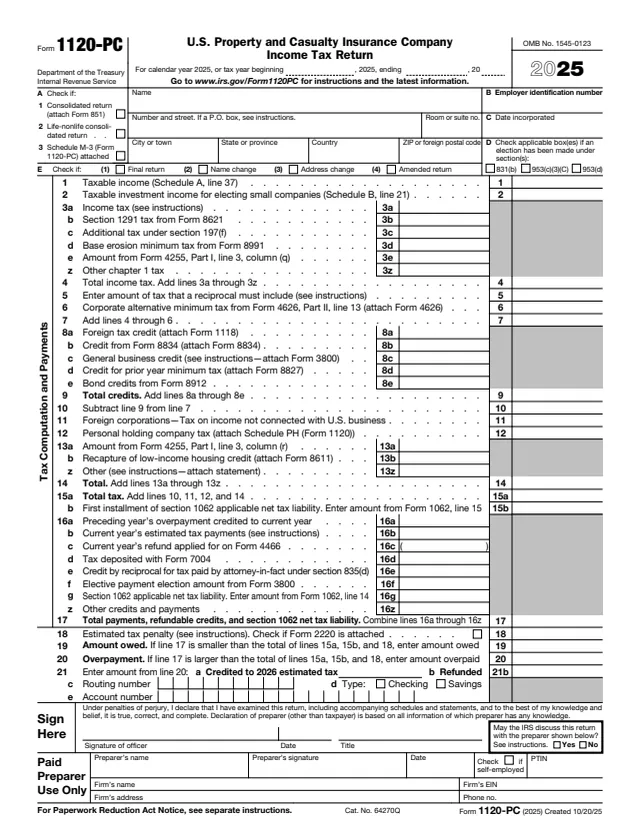
1120-PC
565 fields, 9 pages
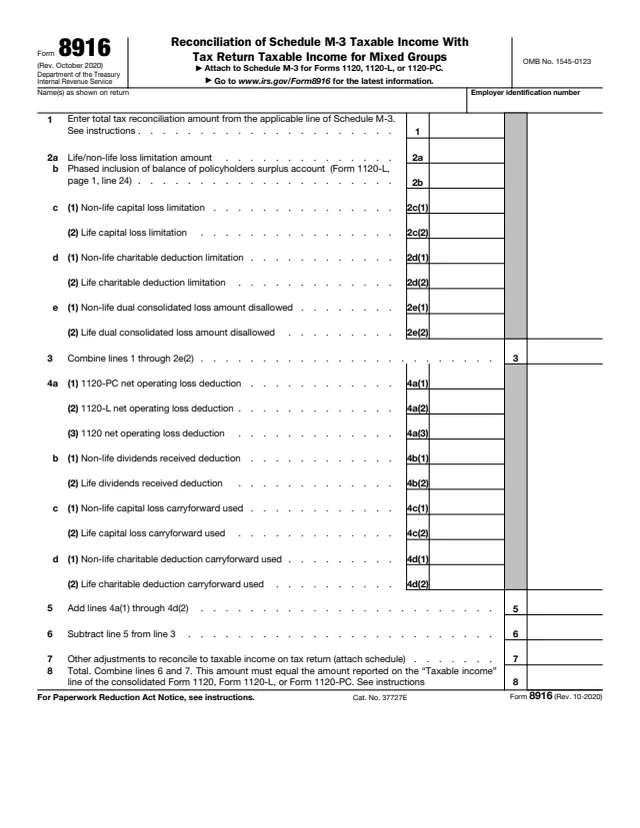
8916
25 fields, 2 pages
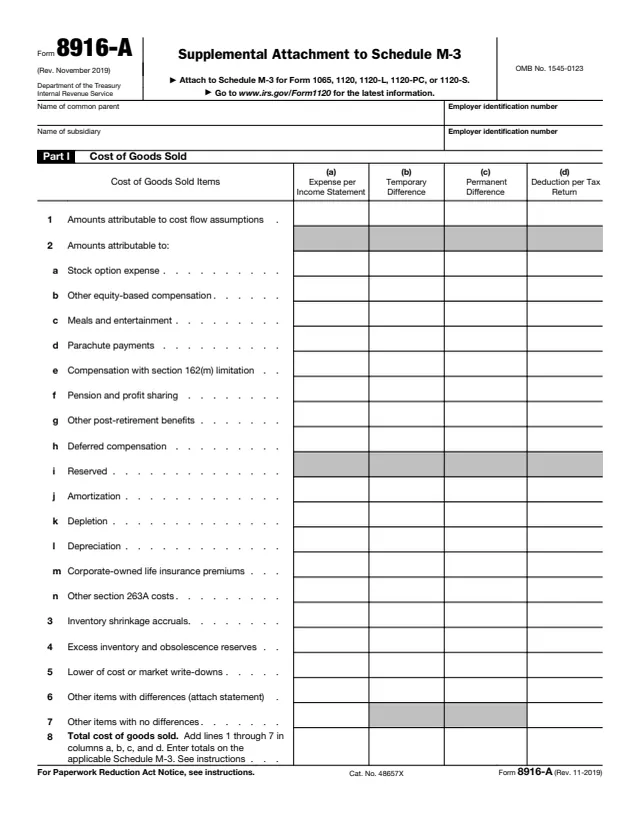
8916-A
140 fields, 4 pages
851
256 fields, 4 pages
1120 Sch. M-3
380 fields, 3 pages
1120-L Sch. M-3
383 fields, 3 pages
The property and casualty insurance company, or the common parent on a consolidated return, completes it and attaches it to Form 1120-PC.
No tool matches that search.
A domestic corporation or consolidated group filing Form 1120-PC that reports total assets of $10 million or more on Schedule L at the end of the tax year. Others filing Form 1120-PC may file it voluntarily.
No. The instructions say a property and casualty insurance company filing Schedule M-3 does not file Schedule M-1.
To the subtotal on Form 1120-PC, Schedule A, line 35 (or Schedule B, line 19, if applicable). The form notes that Part II, line 30, column (d), equals Schedule A, line 35.
For companies that prepare an annual statement, the instructions say financial statement net income (loss) should be reported on the statutory basis.
That member files the Schedule M-3 for its own form, and the group follows the mixed group rules and also files Form 8916 and, if applicable, Form 8916-A.
With Form 1120-PC and all attachments, to the Internal Revenue Service Center, Ogden, UT 84201-0012, as the instructions list.