Header
Name and employer identification number of the common parent and of the subsidiary.
8916-A
Supplemental Attachment to Schedule M-3
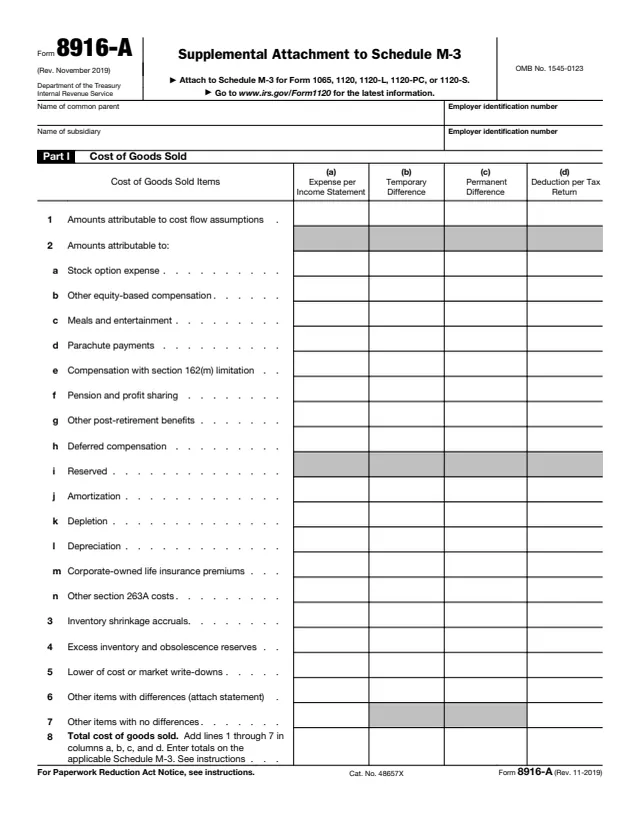
Form 8916-A is a supplemental attachment to Schedule M-3. The form says it is used to provide a detailed schedule of the amounts reported on the applicable Schedule M-3 for cost of goods sold, interest income and interest expense. It is attached to Schedule M-3 for Form 1065, 1120, 1120-L, 1120-PC or 1120-S.
Each of its three parts has four columns: the amount per income statement, the temporary difference, the permanent difference and the amount per tax return. The totals of each part are entered on the applicable Schedule M-3.
The instructions are printed on pages 3 and 4 of the form. You can fill it out free in your browser on this page and download the result without an account.
Name and employer identification number of the common parent and of the subsidiary.
Lines 1 to 8: cost flow assumptions, items such as stock option expense, depreciation and other section 263A costs on line 2, inventory shrinkage, reserves, lower of cost or market write-downs, other items and the total.
Lines 1 to 6: tax-exempt interest, hybrid securities, sale/lease interest, intercompany interest from outside and from within the tax affiliated group, other interest and the total.
Lines 1 to 5: hybrid securities, lease/purchase interest, intercompany interest paid to outside and to the tax affiliated group, other interest and the total.
Each line runs across the amount per income statement, the temporary difference, the permanent difference and the amount per tax return.
The instructions say to report differences attributable to cost flow assumptions, for example differences between book and tax LIFO computations.
Line 2n holds differences attributable to section 263A. Line 6 holds other items with differences and needs an attached statement. Line 7 holds other items with no differences.
Add lines 1 through 7 in each column. The instructions say line 8 should equal Schedule M-3 (Form 1120), Part II, line 17; Schedule M-3 (Form 1120-S), Part II, line 15; or Schedule M-3 (Form 1065), Part II, line 15.
Report each type of interest income on its own line. The instructions say interest income from a debt that is both a hybrid debt and a related party debt goes on line 2, not line 4a or 4b. Line 6 totals the part.
Report each type of interest expense on its own line. The instructions say interest expense from a debt that is both hybrid and related party goes on line 1, not line 3a or 3b. Line 5 totals the part.
The instructions say any filer that completes Parts II and III of Schedule M-3 (Form 1120) and Form 8916-A completes all columns, without exception.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8916-A to each applicable separate Schedule M-3.
Part I, line 8, Part II, line 6 and Part III, line 5 are entered on the applicable Schedule M-3. The instructions name the matching Schedule M-3 line for each part.
The statement separately states and adequately discloses the nature and amount of each expense. The instructions say this detail is not required for the eliminations Schedule M-3 or the consolidated Schedule M-3.
The instructions say a mixed group files Form 8916-A, if applicable, at the sub-consolidated level and the sub-consolidated elimination level.
The form points to www.irs.gov/Form1120 for developments such as legislation enacted after it was published.
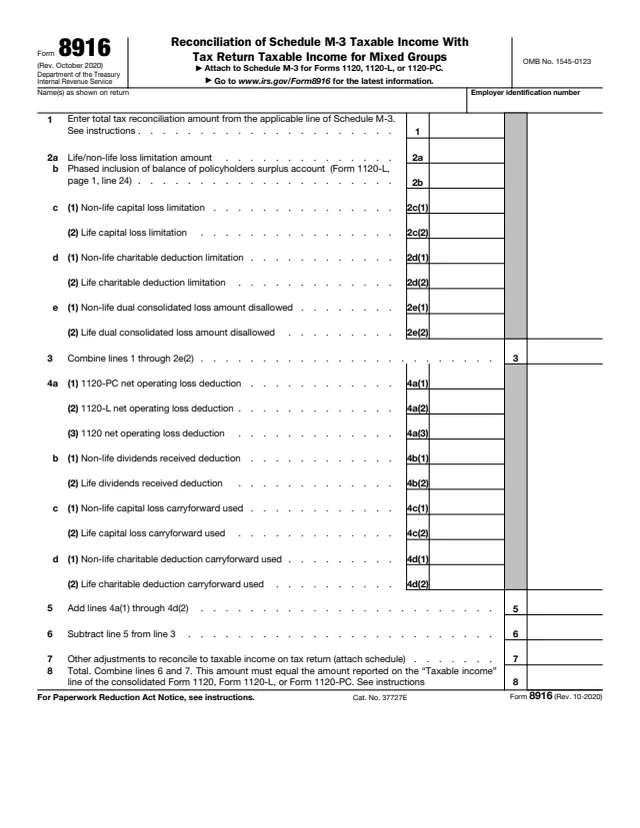
8916
25 fields, 2 pages
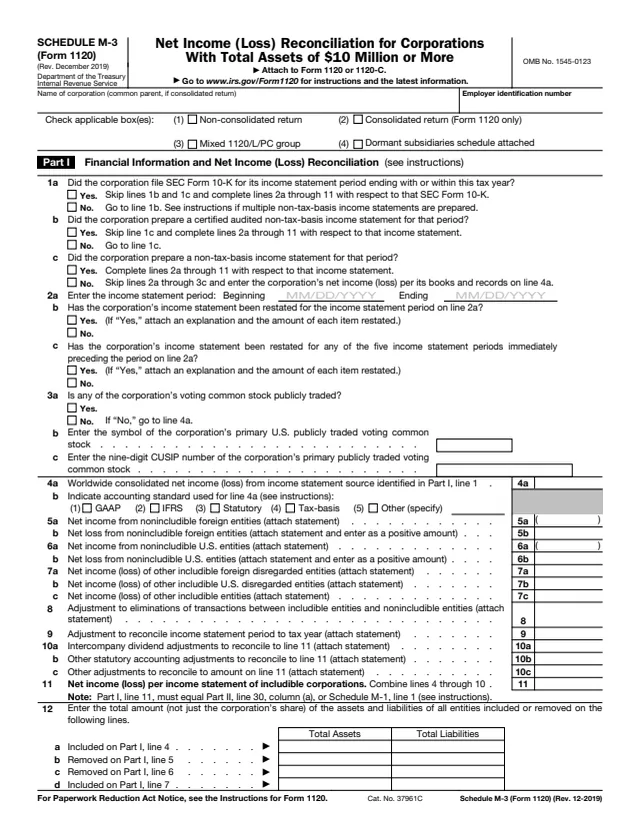
1120 Sch. M-3
380 fields, 3 pages
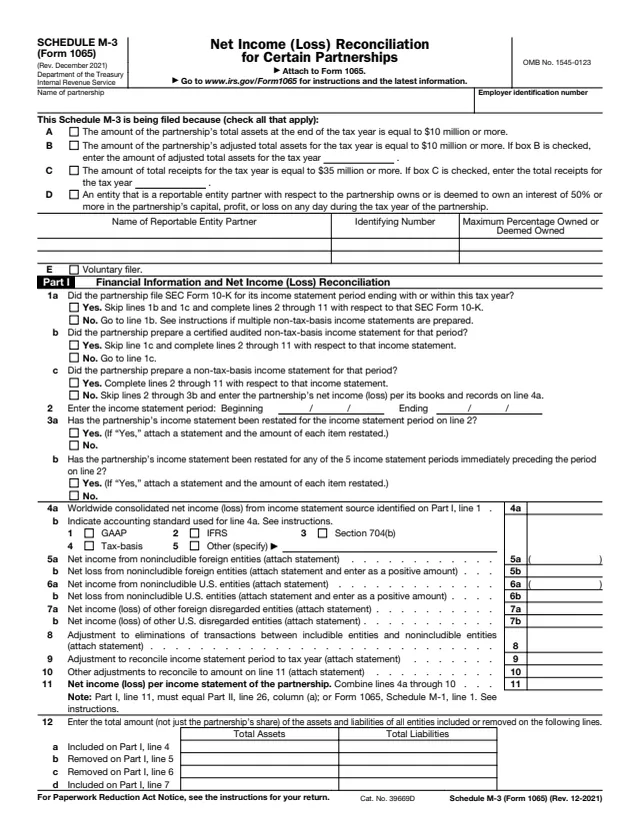
1065 Sch. M-3
316 fields, 3 pages
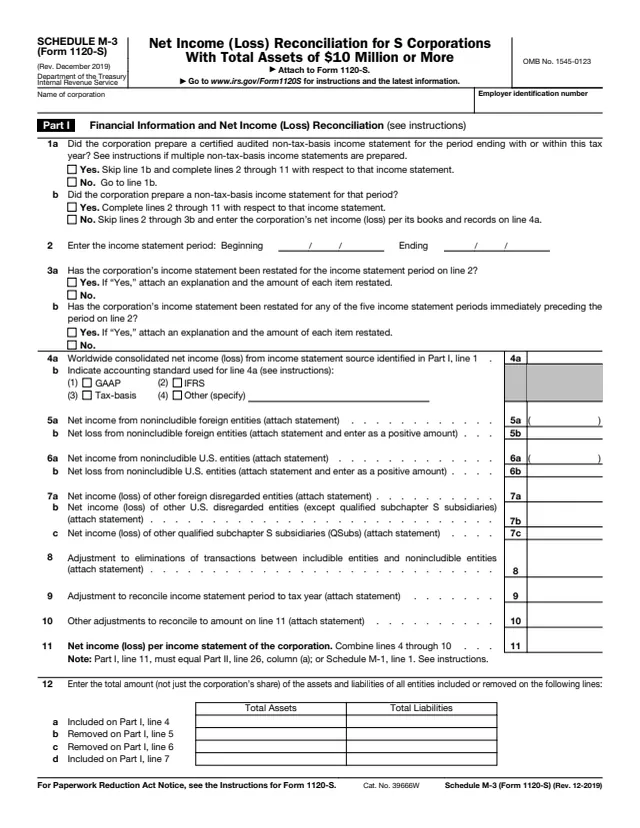
1120-S Sch. M-3
305 fields, 3 pages
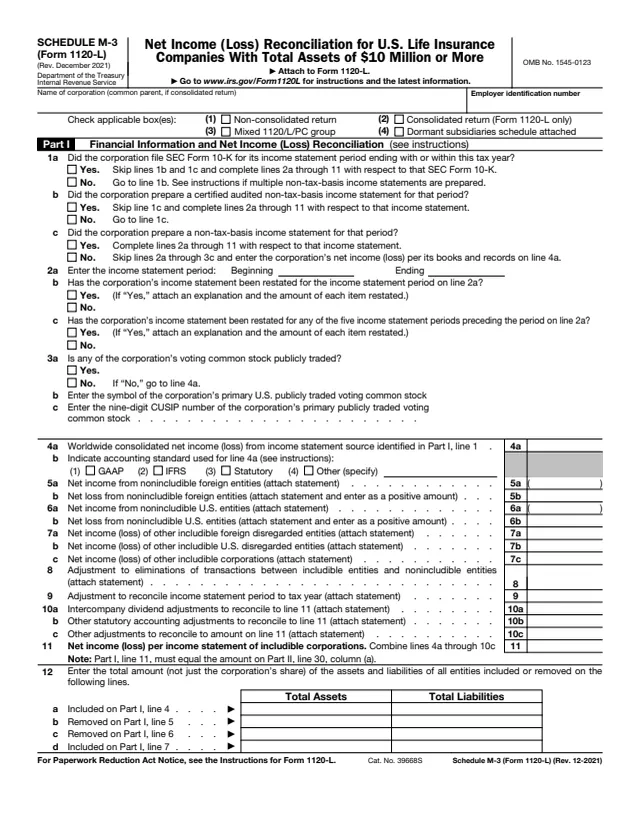
1120-L Sch. M-3
383 fields, 3 pages
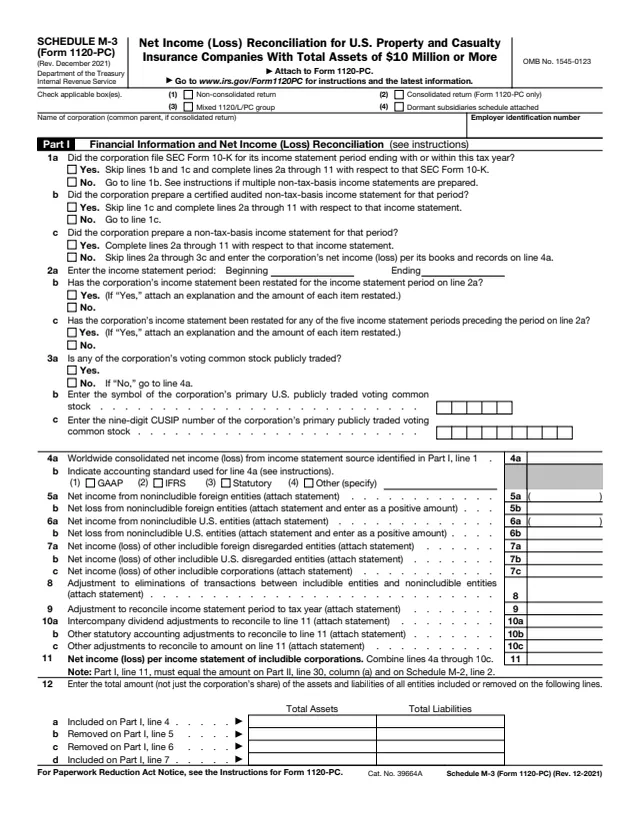
1120-PC Sch. M-3
383 fields, 3 pages
The form is completed by business entities that file a Schedule M-3. The instructions describe these filers.
No tool matches that search.
The form says it is attached to Schedule M-3 for Form 1065, 1120, 1120-L, 1120-PC or 1120-S. The instructions also list Form 1120-C.
No. The instructions say entities with less than $50 million in total assets at the end of the tax year, and voluntary Schedule M-3 filers, are not required to file it but may do so.
The instructions say to attach it to each applicable separate Schedule M-3, not directly to the return.
Column (a) is the amount per income statement, (b) the temporary difference, (c) the permanent difference and (d) the amount per tax return.
The form says to enter the totals of each part on the applicable Schedule M-3. The instructions name the matching line for Forms 1120, 1120-S, 1065, 1120-L and 1120-PC.