Header boxes
Name of the corporation (the common parent, if consolidated), EIN and four boxes: non-consolidated return, consolidated return (Form 1120-L only), mixed 1120/L/PC group, and dormant subsidiaries schedule attached.
1120-L Sch. M-3
Net Income (Loss) Reconciliation for U.S. Life Insurance Companies With Total Assets of $10 Million or More
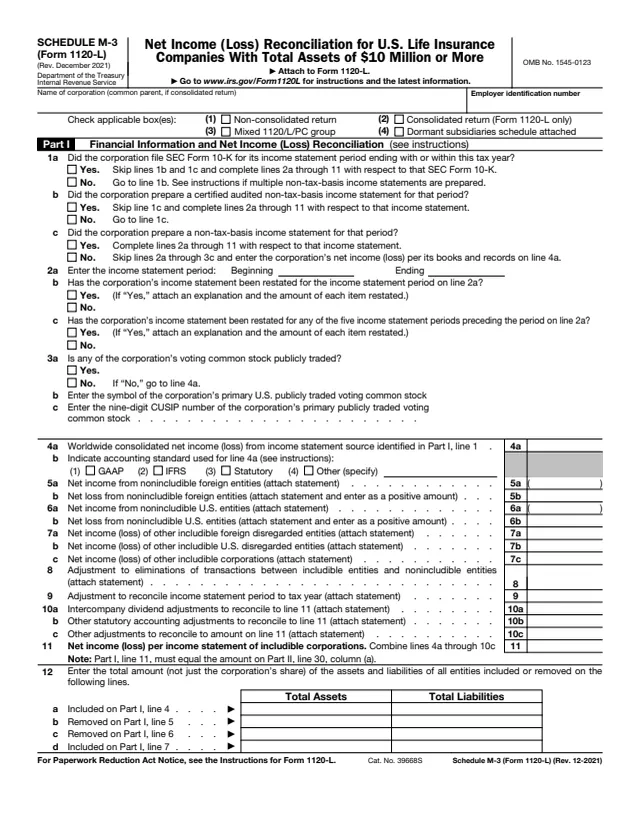
Schedule M-3 (Form 1120-L) is the Net Income (Loss) Reconciliation for U.S. Life Insurance Companies With Total Assets of $10 Million or More. The About Form 1120-L page says this schedule reconciles financial statement net income (loss) with taxable income reported on Form 1120-L, that it must be filed by life insurance companies with total assets of $10 million or more, and that it may be voluntarily filed by life insurance companies not otherwise required to file it.
Part I asks about the company's income statement and arrives at net income (loss) per income statement of includible corporations on line 11. Parts II and III reconcile that amount line by line, and the form notes that Part II, line 30, column (d), equals Form 1120-L, page 1, line 20. The schedule says to attach it to Form 1120-L.
This page hosts the December 2021 revision. You can fill it out free in your browser on this page and download the result without an account.
Name of the corporation (the common parent, if consolidated), EIN and four boxes: non-consolidated return, consolidated return (Form 1120-L only), mixed 1120/L/PC group, and dormant subsidiaries schedule attached.
Which income statement is used (SEC Form 10-K, certified audited, other non-tax-basis, or books and records), the income statement period, any restatements, and the stock symbol and CUSIP number if voting common stock is publicly traded.
Worldwide consolidated net income (loss) with the accounting standard (GAAP, IFRS, statutory or other), adjustments down to line 11, and on line 12 the total assets and liabilities of entities included or removed.
Lines 1 to 30 in four columns: income statement, temporary difference, permanent difference and tax return. Insurance lines include accrual of bond discount, deferred and uncollected premiums, amortization of interest maintenance reserve and market discount reclassification.
Lines 1 to 40, including capitalization and amortization of deferred acquisition costs, changes in section 807(c) tax reserves, section 807(f) adjustments, the section 846 amount and interest expense.
Part II, line 13 (interest income) and Part III, line 36 (interest expense) say to attach Form 8916-A.
The Instructions for Form 1120-L say a company filing Schedule M-3 (Form 1120-L) checks box 3, "Schedule M-3 (Form 1120-L) attached," in item A at the top of page 1 of Form 1120-L.
If SEC Form 10-K was filed for the period, check Yes on line 1a and skip lines 1b and 1c. If line 1c is No, the form says to skip lines 2a through 3c and enter net income (loss) per books and records on line 4a.
Enter the income statement period. If the income statement was restated for that period or for any of the five preceding periods, attach an explanation and the amount of each item restated.
Enter worldwide consolidated net income (loss) and the accounting standard, then the adjustments on lines 5a through 10c, attaching the statements those lines ask for. The form says line 11 equals Part II, line 30, column (a).
For each line, enter the income statement amount in column (a), the temporary and permanent differences in columns (b) and (c), and the tax return amount in column (d). Attach statements where a line says so.
Part III, line 40 combines lines 1 through 39 and goes on Part II, line 27, with positive amounts shown as negative and negative as positive. Part II, line 30, column (d), equals Form 1120-L, page 1, line 20.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 1120-L. The Instructions for Form 1120-L list Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0012 for a company whose principal business, office or agency is in the United States.
The Instructions for Form 1120-L say a corporation generally files by the 15th day of the 4th month after the end of its tax year, with a different rule for a fiscal year ending June 30. Form 7004 requests an extension.
A company that does not file Schedule M-3 (Form 1120-L) attaches a statement reconciling Form 1120-L with the annual statement used as the basis for computing taxable income.
The Instructions for Form 1120-L point to the Instructions for Schedule M-3 (Form 1120-L) for more details, and the About Form 1120-L page links both.
The About Form 1120-L page lists a notice dated 20-FEB-2026: no penalty for not electronically filing Forms 1120-REIT, 1120-RIC, 1120-L, and 1120-PC for 2025.
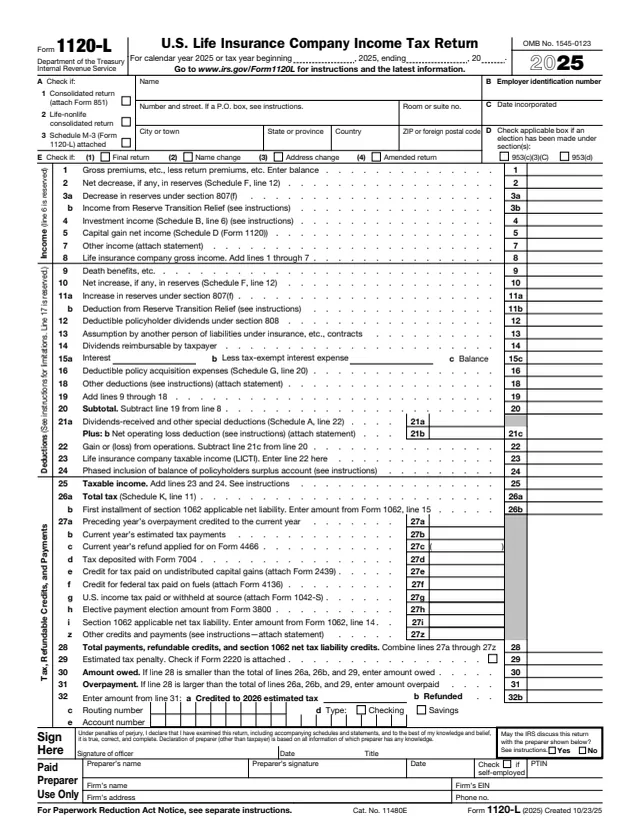
1120-L
337 fields, 6 pages
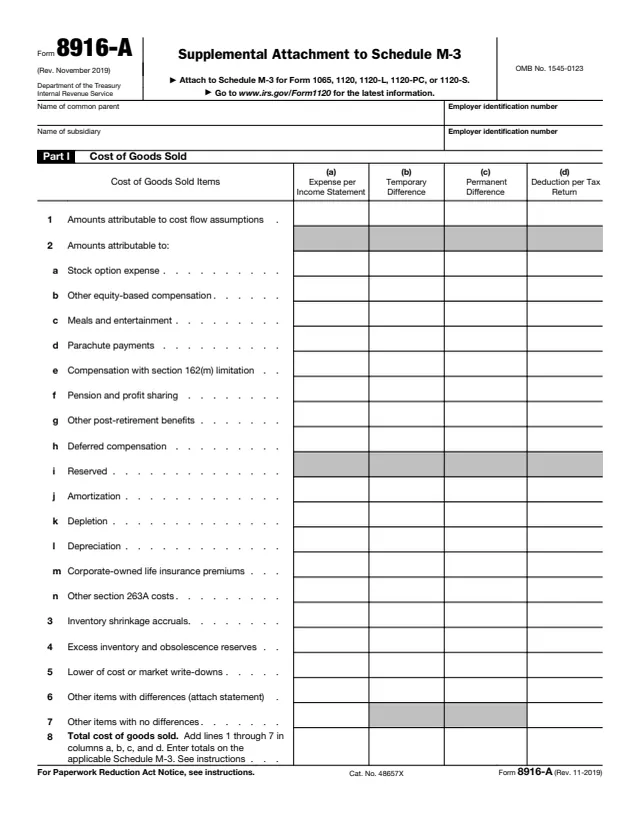
8916-A
140 fields, 4 pages
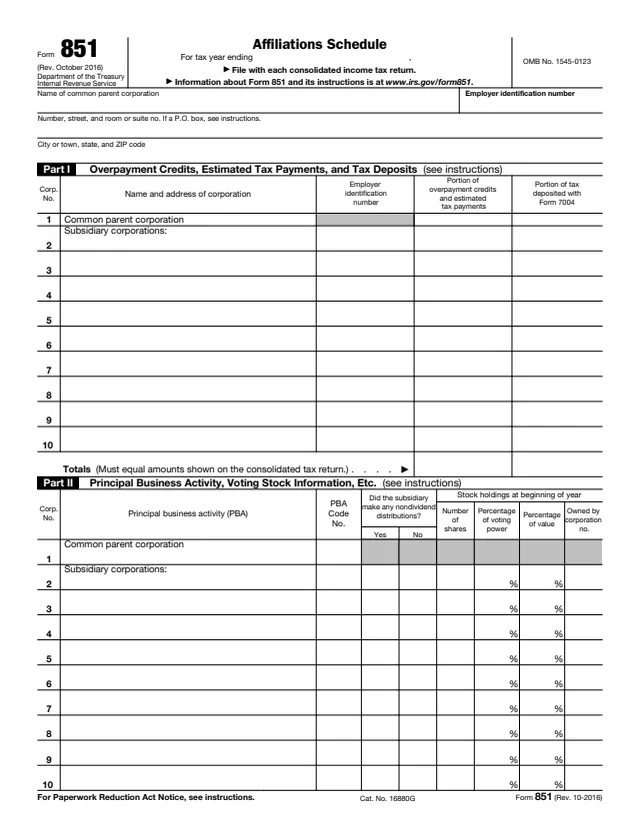
851
256 fields, 4 pages

7004
26 fields, 1 page
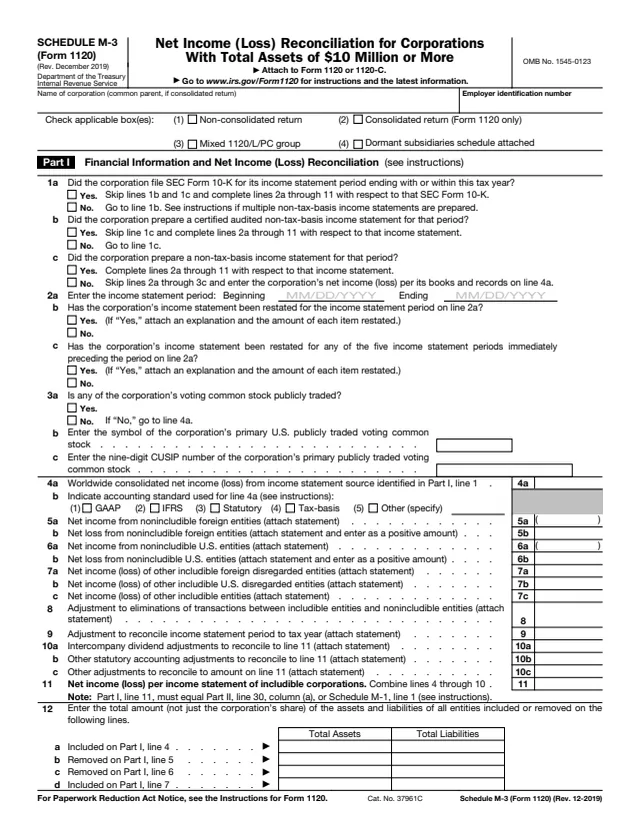
1120 Sch. M-3
380 fields, 3 pages
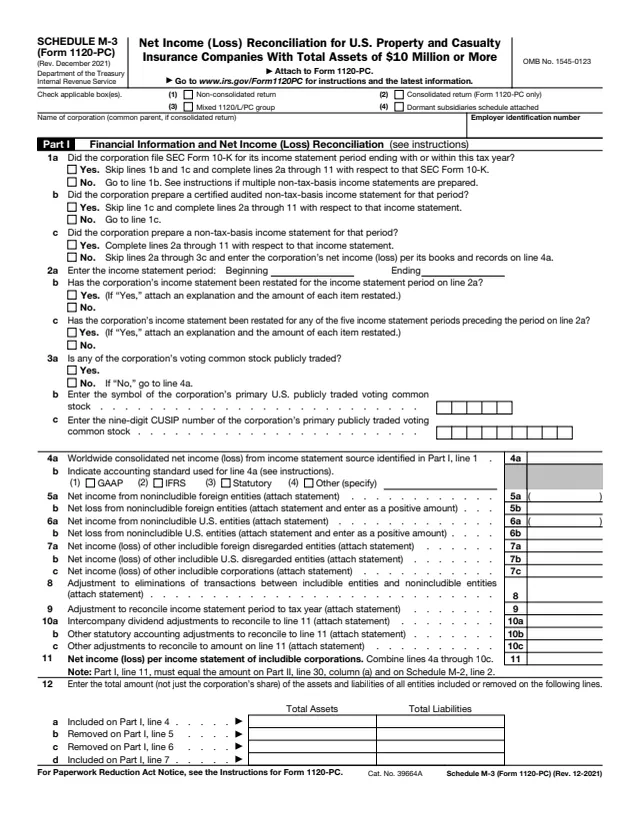
1120-PC Sch. M-3
383 fields, 3 pages
The life insurance company, or the common parent on a consolidated return, completes it and attaches it to Form 1120-L.
No tool matches that search.
A life insurance company with total assets of $10 million or more on the last day of the tax year, counting all companies in a tax consolidation group, according to the Instructions for Form 1120-L.
Yes. The instructions say a corporation filing Form 1120-L that is not required to file Schedule M-3 may file it voluntarily.
The Instructions for Form 1120-L say it attaches a statement that reconciles Form 1120-L with the annual statement used as the basis for computing taxable income.
The form notes that Part II, line 30, column (d), equals Form 1120-L, page 1, line 20, and column (a) equals Part I, line 11.
Part II, line 13 (interest income) and Part III, line 36 (interest expense) say to attach Form 8916-A.
The Instructions for Form 1120-L say to see the Instructions for Schedule M-3 (Form 1120-L) for more details. The About Form 1120-L page links both sets of instructions.