Header
The tax year ending date, the name of the common parent corporation, its employer identification number and its address.
851
Affiliations Schedule
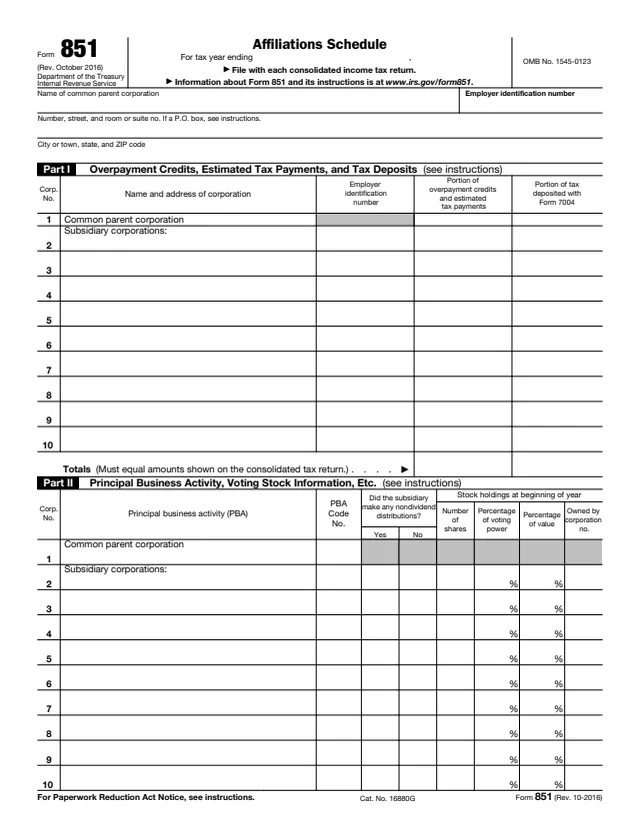
Form 851, Affiliations Schedule, is a four-page form filed with a consolidated income tax return. The IRS About page says the parent corporation of an affiliated group files it with its consolidated return to identify the common parent corporation and each member of the group, report the overpayment credits, estimated tax payments and tax deposits attributable to each corporation, and determine that each subsidiary qualifies as a member of the affiliated group.
The form's instructions describe an affiliated group as one or more chains of includible corporations connected through stock ownership with a common parent corporation, where stock representing at least 80% of the total voting power and at least 80% of the total value is owned directly within the group.
The instructions are printed on page 4 of the form. You can fill out Form 851 free in your browser on this page and download it without an account.
The tax year ending date, the name of the common parent corporation, its employer identification number and its address.
For each corporation, its portion of overpayment credits and estimated tax payments and its portion of tax deposited with Form 7004, with totals that must equal the consolidated return.
Principal business activity (PBA) and code, whether the subsidiary made nondividend distributions, and stock holdings at the beginning of the year by shares, voting power and value.
Shares acquired and disposed of during the tax year, plus questions (c) to (f) on basis exceeding value, worthless stock, equitable owners and stock issued or retired.
More than one class of stock, reaffiliation within 60 months of disaffiliation, and arrangements letting nonmembers acquire stock or voting power.
Purpose of the form, who must file, the affiliated group rules, the address rule and line instructions for Parts I to IV.
Include the suite, room or other unit number after the street address. The instructions say to show a P.O. box only if the post office does not deliver mail to the street address.
Use the same corporation number for the parent and each subsidiary in Parts II, III and IV as in Part I.
Enter each corporation's prior-year overpayment credited to this year, its estimated tax payments, and the tax deposited with Form 7004 attributable to it. Totals equal the consolidated return lines.
Enter the PBA and code from the list in the Instructions for Form 1120, based on the activity that produces the largest percentage of total receipts. Mark nondividend distributions; the instructions refer to Form 5452.
List stock changes during the year, then answer question (c) on transfers where basis exceeded value and (d) on worthless stock. The instructions say certain basis adjustments may be required.
Answer the three questions. For question 3, the instructions say an arrangement includes phantom stock, stock appreciation rights, an option, warrant or conversion feature. Items 3a to 3d give the percentages and a description.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "File with each consolidated income tax return." The instructions say it is attached to the consolidated tax return for the group.
The form and its instructions say the Part I totals must equal the amounts shown on the consolidated tax return, including the "Tax deposited with Form 7004" line.
Part I has a column for tax deposited with Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns.
The About page lists the October 2016 revision as the current Form 851, with no recent developments.
The instructions say the parent corporation files Form 851 for itself and for the corporations in the affiliated group, by attaching it to the consolidated tax return for the group.
No tool matches that search.
The instructions say the parent corporation files it for itself and for the corporations in the affiliated group, attached to the group's consolidated tax return.
The instructions say it is one or more chains of includible corporations connected through stock ownership with a common parent corporation. See sections 1504(a) and (b).
The instructions say they are distributions, other than stock dividends and distributions in exchange for stock, made to shareholders during the tax year in excess of the corporation's current and accumulated earnings and profits.
The instructions say the list of principal business activities and code numbers is in the Instructions for Form 1120.
The instructions say equitable owners are those that essentially have all the rights to enjoy the benefits of stock ownership without actually holding the stock, for example, beneficiaries of a trust.