Header
The calendar year ending December 31 that the report covers, the corporation's name and its employer identification number.
5452
Corporate Report of Nondividend Distributions
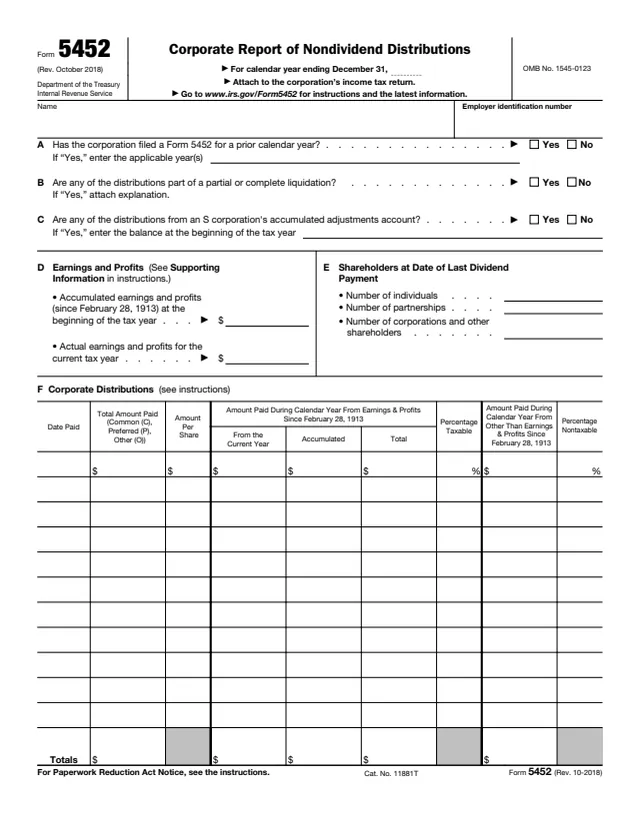
Form 5452 is the Corporate Report of Nondividend Distributions. The instructions say to complete it if the corporation made nondividend distributions to shareholders under section 301, section 1368(c)(3), section 1371(e), or section 1371(f). They describe nondividend distributions as distributions made to shareholders in the normal course of business that are fully or partially nontaxable as dividends only because the paying corporation's current and accumulated earnings and profits are less than the distributions. Tax-free stock dividends and distributions exchanged for stock in liquidations or redemptions are not included.
The form is completed by the corporation that made the distributions, and the form says to attach it to the corporation's income tax return. It reports the corporation's earnings and profits, the number of shareholders and the taxable and nontaxable status of each distribution. Pages 3 and 4 hold an example and a blank worksheet for figuring current year earnings and profits.
This page hosts the October 2018 revision. You can fill it out free in your browser on this page and download the result without an account.
The calendar year ending December 31 that the report covers, the corporation's name and its employer identification number.
Whether the corporation filed Form 5452 for a prior calendar year, whether any distributions are part of a partial or complete liquidation, and whether any come from an S corporation's accumulated adjustments account.
Accumulated earnings and profits since February 28, 1913, at the beginning of the tax year, and actual earnings and profits for the current tax year.
The number of individuals, the number of partnerships, and the number of corporations and other shareholders at the date of the last dividend payment.
One row per distribution: date paid, total amount paid as common (C), preferred (P) or other (O), amount per share, amounts from current and accumulated earnings and profits, percentage taxable, amount from other than earnings and profits, and percentage nontaxable.
Page 3 shows a filled-in example for XYZ Corporation and page 4 a blank worksheet for figuring current year earnings and profits, lines 1 to 11, with the cash distribution split below.
Enter the year after "For calendar year ending December 31," then the corporation's name and EIN. The amounts in item F are amounts paid during that calendar year.
Check Yes or No for each. If A is Yes, enter the prior years. If B is Yes, attach an explanation. If C is Yes, enter the accumulated adjustments account balance at the beginning of the tax year.
The form points to Supporting Information in the instructions for item D. The worksheet starts from taxable income on Form 1120, line 28 (or the comparable line of another income tax return), before the net operating loss deduction and special deductions.
Enter how many shareholders were individuals, partnerships, and corporations and other shareholders at the date of the last dividend payment.
The instructions say to show the taxable and nontaxable status of distributions reported to shareholders. The percentages are based on the amounts on each line in the Total Amount Paid column. For noncash distributions, attach a statement showing both the tax bases and fair market values.
Attach a computation of earnings and profits for the tax year, a year-by-year computation of accumulated earnings and profits, any schedule of differences from Schedule M-1 or Schedule M-3 (Form 1120), and a tax basis balance sheet if Schedule L (Form 1120) was required. The instructions cite Rev. Proc. 75-17.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the corporation's income tax return.
The instructions say to attach Form 5452 and the supporting information to the income tax return due for the tax year in which the nondividend distributions were made.
The instructions say to attach them to the income tax return due for the first fiscal year ending after the calendar year in which the nondividend distributions were made.
If the corporation used an accelerated method of depreciation, the instructions ask for a schedule of the depreciation (and any amortization) figured under the straight line method, and a reconciliation to the amount deducted on the return.
The parent also attaches a schedule of the allocation of the consolidated tax liability and the method used, a schedule of each member's taxable income or loss, and the supporting information for each member that made nondividend distributions.
The instructions are printed on page 2 of the form. The form points to www.irs.gov/Form5452 for the latest information, and the About page lists no recent developments.
The instructions say all corporations that have made nondividend distributions to their shareholders file Form 5452. It goes to the IRS attached to the corporation's income tax return.
No tool matches that search.
A corporation that made nondividend distributions to its shareholders. If the corporation is a member of a consolidated group, the instructions say the parent corporation files it.
No. The form says to attach it to the corporation's income tax return, along with the supporting information the instructions list.
The instructions describe it as a distribution made to shareholders in the normal course of business that is fully or partially nontaxable as a dividend only because the corporation's current and accumulated earnings and profits are less than the distributions.
The instructions say nondividend distributions do not include tax-free stock dividends or distributions exchanged for stock in liquidations or redemptions.
The instructions say when distributions are made under section 1371(e) or 1371(f), or in the year when distributions fully exhaust accumulated earnings and profits.
On page 2 of the form itself, followed by a filled-in example and a blank worksheet for figuring current year earnings and profits.