Payer and recipient boxes
Payer's name, address and phone number, payer's TIN, recipient's TIN, name and address, account number and the 2nd TIN not. box.
1099-PATR
Taxable Distributions Received From Cooperatives
Form 1099-PATR is the information return a cooperative files to report taxable distributions to its patrons. The IRS says cooperatives file it for each person to whom they paid at least $10 in patronage dividends and other distributions described in section 6044(b), and for each person from whom they withheld federal income tax under the backup withholding rules, regardless of the amount.
The form reports patronage dividends, nonpatronage distributions, per-unit retain allocations, backup withholding, redeemed nonqualified notices, section 199A items and credits passed through to the patron. The cooperative files Copy A with the IRS and gives Copy B to the recipient. The instructions say dividends on a cooperative's capital stock go on Form 1099-DIV instead.
The instructions say Copy B is fillable online and may be sent to the recipient. You can fill out the PDF free in your browser on this page and download it without an account.
Payer's name, address and phone number, payer's TIN, recipient's TIN, name and address, account number and the 2nd TIN not. box.
Box 1 patronage dividends, box 2 nonpatronage distributions and box 3 per-unit retain allocations.
Box 4 federal income tax withheld (backup withholding) and box 5 redeemed nonqualified notices.
Box 6 section 199A(g) deduction, box 7 qualified payments, box 8 section 199A(a) qualified items and box 9 section 199A(a) SSTB items.
Box 10 investment credit, box 11 work opportunity credit, box 12 other credits and deductions, and box 13 for specified cooperatives.
Copy A is for the Internal Revenue Service Center and Copy B is for the recipient, with Instructions for Recipient on the back.
Enter the cooperative's and the patron's names, addresses and TINs. The instructions say the payee's TIN may be truncated on payee statements but not on documents filed with the IRS.
The instructions say an account number is required when a recipient has multiple accounts with more than one Form 1099-PATR, and the IRS encourages one on every form.
Enter the patron's share of patronage dividends, nonpatronage distributions (box 2 is for farmers' cooperatives exempt under section 521 only) and per-unit retain allocations.
Enter backup withholding on patronage payments in box 4, and redeemed nonqualified written notices of allocation and per-unit retain certificates in box 5.
Boxes 6 and 7 are for specified agricultural and horticultural cooperatives only. The instructions say the box 6 deduction cannot exceed 9% of the qualified payments in box 7.
Enter the patron's share of credits, list each other credit or deduction by type and amount in box 12, and check box 13 for a specified agricultural or horticultural cooperative.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The PDF says the Copy A printed from the website is not scannable and not to file it; a penalty may be imposed for filing forms that can't be scanned. Official Copy A forms can be ordered at IRS.gov/EmployerForms.
The instructions say a filer of Form 1099-PATR furnishes a statement to the recipient. Copy B can be filled out online and sent to the recipient.
The PDF says a filer with 10 or more information returns may be required to e-file, and the IRS strongly encourages e-filing for fewer than 10.
The instructions point to the General Instructions for Certain Information Returns for who must file, when and where to file, corrections, backup withholding and penalties.
The instructions say to use them for tax year 2025 and later years until a superseding revision is issued.
1099-DIV
140 fields, 6 pages
3491
29 fields, 2 pages
8995
33 fields, 1 page
8995-A
111 fields, 2 pages
W-9
23 fields, 6 pages
3468
321 fields, 12 pages
The cooperative, as payer, completes and files the form. The patron receives Copy B and does not file the form.
No tool matches that search.
A cooperative. The IRS says cooperatives file it for each person paid at least $10 in patronage dividends and other section 6044(b) distributions, or from whom federal income tax was backup withheld.
No. The cooperative files Copy A with the IRS and gives Copy B to the patron, who keeps it for their records.
No. The instructions say dividends paid on a cooperative's capital stock are reported on Form 1099-DIV.
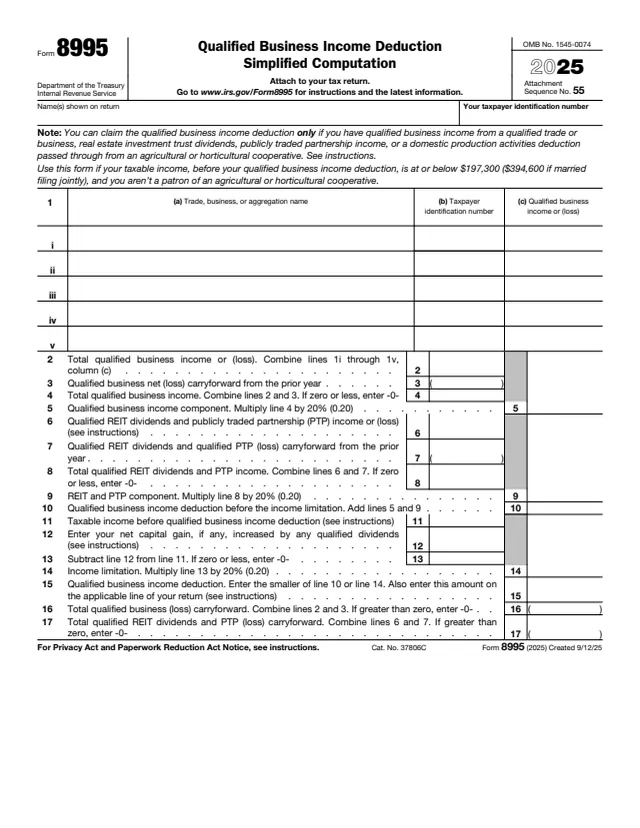
The recipient instructions say these amounts are information needed to compute the section 199A(a) deduction, and point to the instructions for Form 8995 or 8995-A.
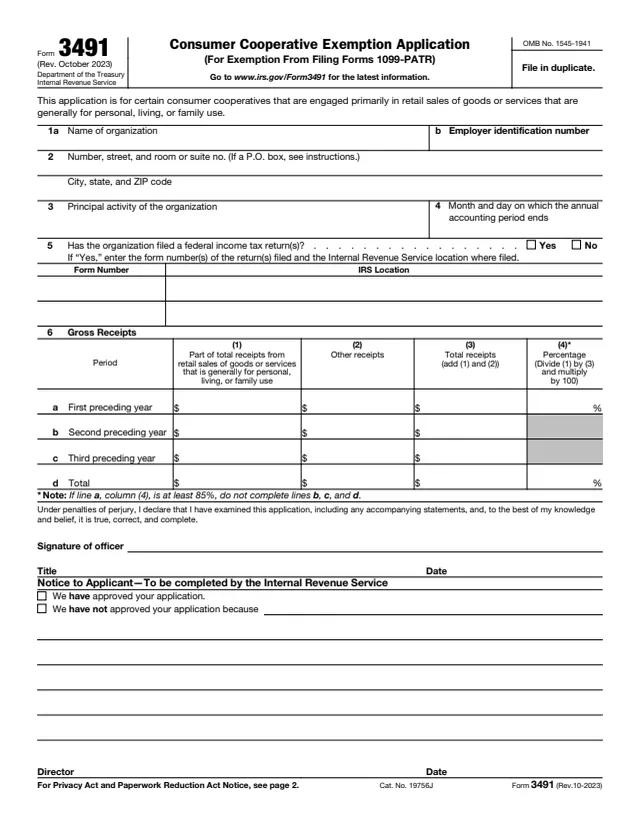
The instructions say a cooperative primarily engaged in retail sales of goods or services generally for personal, living or family use of members may ask for an exemption on Form 3491.
The PDF says the online Copy A is for information only and is not scannable. Copy B and the other black copies may be printed and given to the recipient.