Part I: trade, business or aggregation
Line 1 lists up to three rows, A to C, with the name, boxes for a specified service business, an aggregation or a cooperative patron, and the taxpayer identification number.
8995-A
Qualified Business Income Deduction
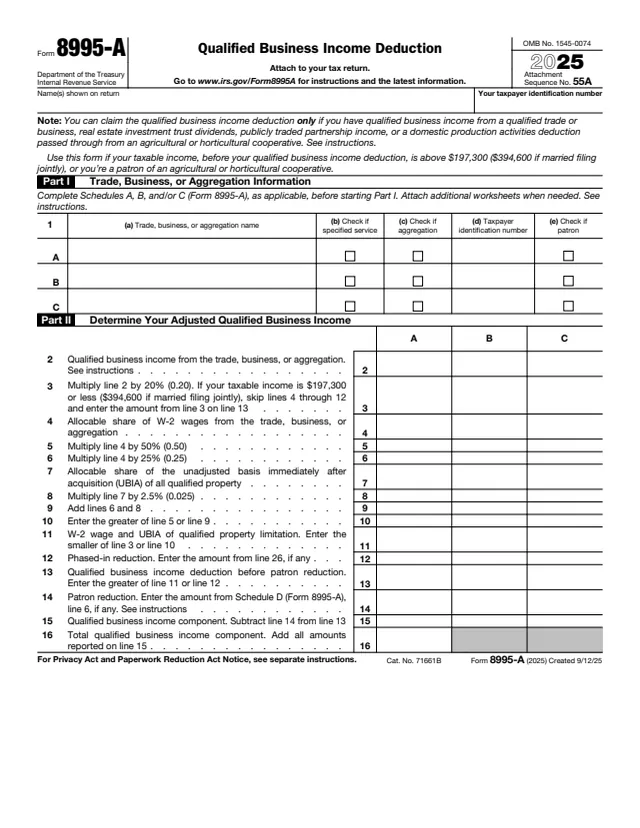
Form 8995-A is the full worksheet for the qualified business income (QBI) deduction. The About page says to use it to figure your qualified business income deduction, with separate Schedules A, B, C and D as appropriate to help calculate it.
The 2025 form says to use it if your taxable income, before the QBI deduction, is above $197,300 ($394,600 if married filing jointly), or if you are a patron of an agricultural or horticultural cooperative. The instructions say that otherwise Form 8995, the simplified computation, is used instead. The form is attached to the tax return, and the total on line 39 goes to a line of that return, such as Form 1040, line 13a.
The form works through each trade, business or aggregation, applies the W-2 wage and property limits, adds the REIT and publicly traded partnership component, and caps the total by an income limitation. You can fill it out free in your browser on this page and download the result without an account.
Line 1 lists up to three rows, A to C, with the name, boxes for a specified service business, an aggregation or a cooperative patron, and the taxpayer identification number.
Lines 2 to 16 take QBI, 20% of it, W-2 wages, the unadjusted basis of qualified property (UBIA), the wage and property limit, the patron reduction and the total QBI component.
Lines 17 to 26 apply only when taxable income is more than $197,300 but not $247,300 ($394,600 and $494,600 if married filing jointly) and line 10 is less than line 3.
Lines 27 to 40 add the REIT and PTP component, apply the income limitation of 20% of taxable income less net capital gain, add any section 199A(g) deduction, and show any loss carryforward.
Separate schedules cover specified service trades or businesses (A), aggregation of business operations (B), loss netting and carryforward (C), and special rules for cooperative patrons (D).
The form says to complete Schedules A, B and/or C, as applicable, before starting Part I. The instructions say a cooperative patron completes Schedule D before Schedule A.
Enter each trade or business, or the aggregation group name such as Aggregation 1. In column (d) the instructions say to enter the EIN, or an SSN or ITIN if there is no EIN.
Enter QBI, W-2 wages on line 4 and UBIA on line 7. The instructions say lines 4 and 7 are zero when line 2 is zero, and a statement is attached for four or more trades or businesses.
In the phase-in range, enter taxable income before the QBI deduction on line 20, the threshold on line 21 and the phase-in range of $50,000 ($100,000 if married filing jointly) on line 23.
Enter REIT dividends and PTP income on line 28, as a negative number if a loss. Line 33 is taxable income before the QBI deduction, for Form 1040 filers line 11a minus lines 12e and 13b.
Line 39 is the deduction. The instructions say it goes on Form 1040 or 1040-SR, line 13a, Form 1040-NR, line 13a, or Form 1041, line 20. A loss on line 40 carries forward to next year.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. It has no mailing address of its own and is filed with that return.
The instructions say that a filer at or under the threshold who is not a cooperative patron files Form 8995, Qualified Business Income Deduction Simplified Computation, instead.
The Schedule C (Form 8995-A), line 6 amount is reported next year on Schedule C, line 2, or Form 8995, line 3. A REIT and PTP loss on line 40 also carries forward.
The instructions say certain tip income may be excluded when figuring QBI, and not to include in QBI amounts deducted under IRC 224 for qualified tips.
The About page lists a February 13, 2026 correction to the instructions on how to calculate taxable income before the QBI deduction.
Starting Part I before the schedules, entering wages or UBIA for a business whose QBI is zero, skipping the statement for a fourth business, and leaving out a prior year loss carryforward.
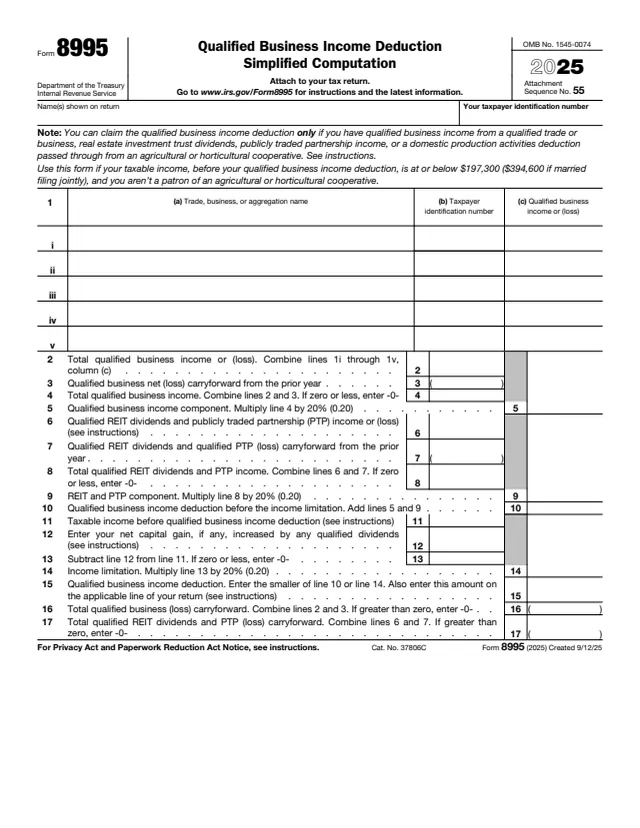
8995
33 fields, 1 page
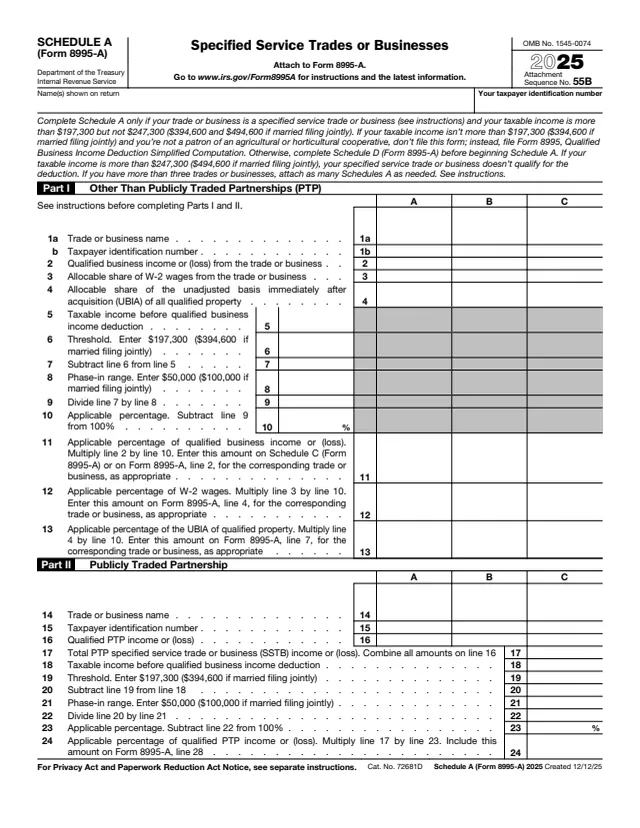
8995-A
67 fields, 1 page
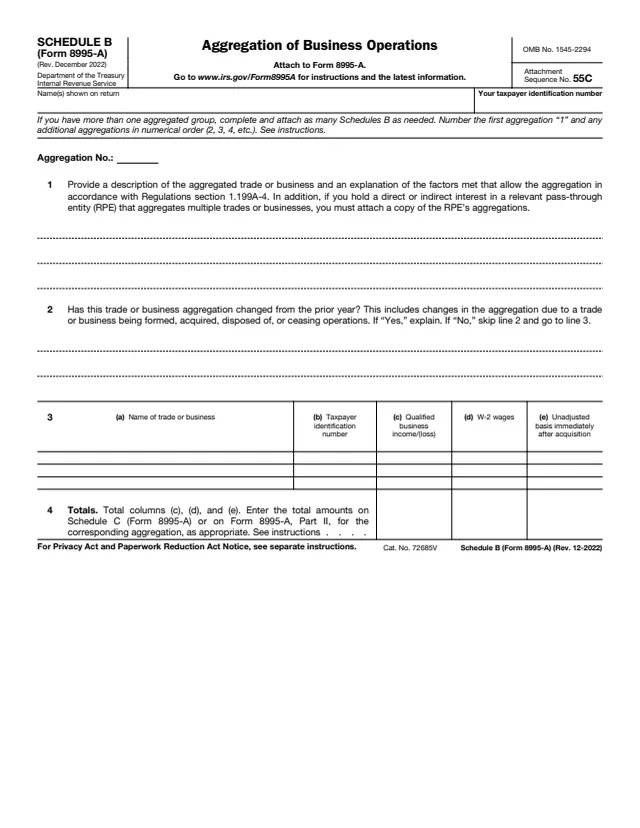
8995-A Sch. B
27 fields, 1 page
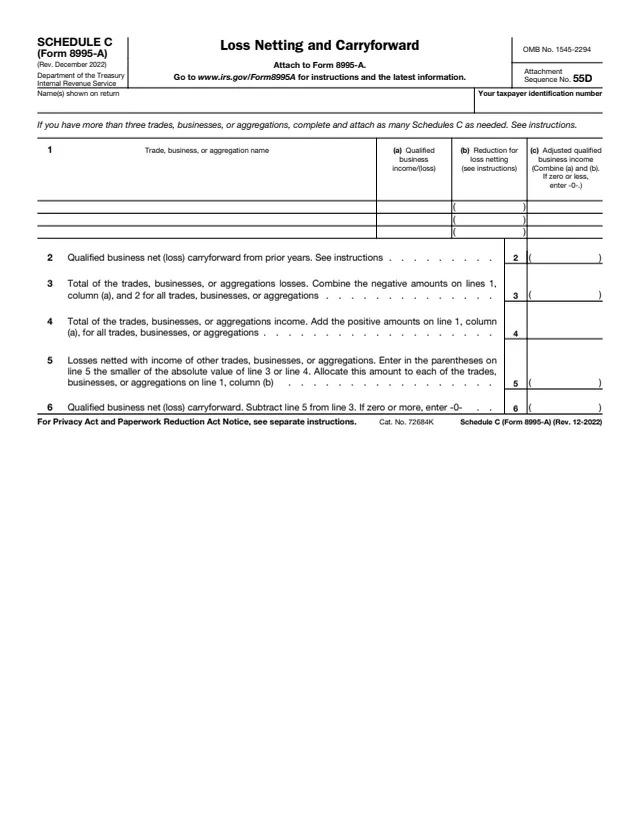
8995-A Sch. C
19 fields, 1 page
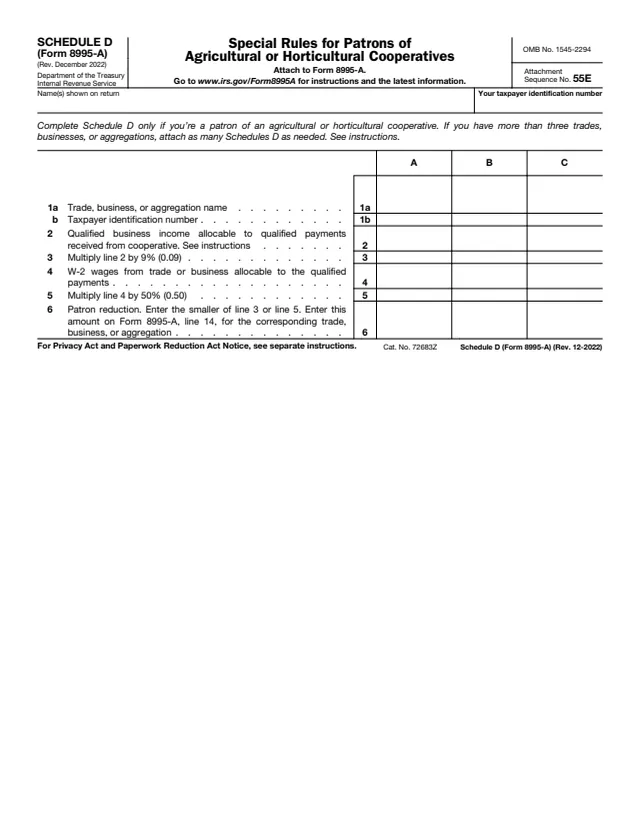
8995-A Sch. D
23 fields, 1 page

1040
199 fields, 2 pages
The instructions say individuals and eligible estates and trusts use Form 8995-A when their income or cooperative patronage puts them outside the simplified Form 8995.
No tool matches that search.
The 2025 form says to use it if taxable income before the QBI deduction is above $197,300 ($394,600 if married filing jointly), or for a patron of an agricultural or horticultural cooperative. Otherwise the instructions point to Form 8995.
No. The instructions say S corporations and partnerships are not eligible for the deduction. They pass the information to shareholders or partners on an attachment to Schedule K-1.
The instructions say to enter it on Form 1040 or 1040-SR, line 13a, Form 1040-NR, line 13a, Form 1041, line 20, Form 1041-N, line 9, or Form 990-T, Part I, line 9.
They are separate schedules of Form 8995-A for specified service trades or businesses, aggregation of business operations, loss netting and carryforward, and special rules for cooperative patrons.
The instructions say that with four or more trades or businesses, a statement with the Parts I, II and III information is attached, and line 16 is completed only on the first page.
Schedule C (Form 8995-A) nets it against QBI from other businesses. The instructions say the line 6 amount is reported next year and offsets QBI in later years.