Header
Calendar year, name of trust, employer identification number, name of trustee and the trustee's address.
1041-A
U.S. Information Return Trust Accumulation of Charitable Amounts
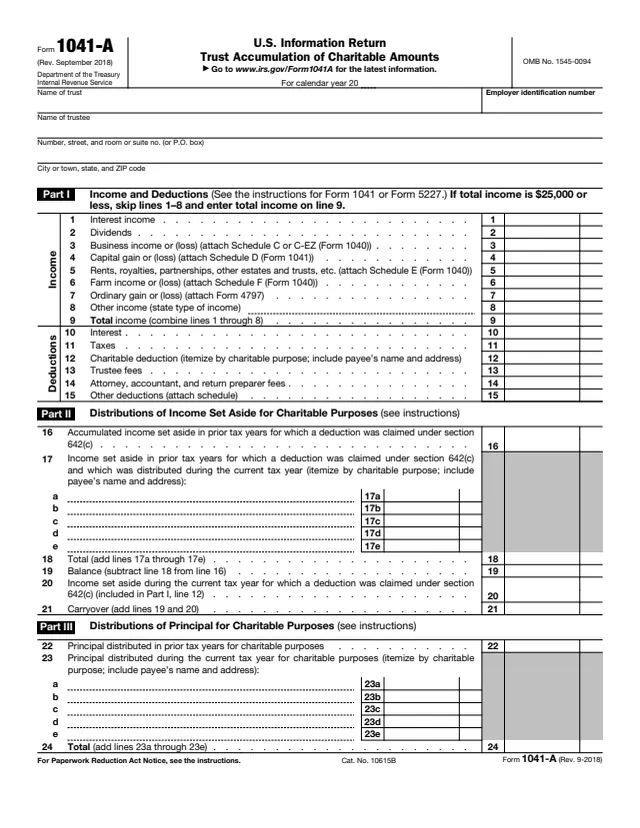
Form 1041-A, U.S. Information Return Trust Accumulation of Charitable Amounts, is filed by the trustee of a trust. The instructions say to use it to report the charitable information required by section 6034 and the related regulations, and that the trustee files it for a trust that claims a charitable or other deduction under section 642(c) unless an exception applies.
The return covers a calendar year. It reports the trust's income and deductions, income set aside in earlier years and distributed for charitable purposes, principal distributed for charitable purposes, and beginning and end-of-year balance sheets. The trustee or an officer representing the trustee signs it. The instructions are printed on pages 3 and 4 of the same PDF.
You can fill out Form 1041-A free in your browser on this page and download it without an account.
Calendar year, name of trust, employer identification number, name of trustee and the trustee's address.
Lines 1 to 9 list income such as interest, dividends, business income, capital gain, rents and farm income. Lines 10 to 15 list deductions, including the charitable deduction and trustee fees.
Lines 16 to 21 track income set aside in prior years under section 642(c), the part distributed this year, income set aside this year and the carryover.
Lines 22 to 24 show principal distributed in prior years and in the current year for charitable purposes, itemized with each payee's name and address.
Lines 25 to 46 list assets, liabilities and net assets at beginning-of-year and end-of-year book value.
Signature of the trustee or officer representing the trustee, and the Paid Preparer Use Only section.
Enter the calendar year, the trust's name and EIN, and the trustee's name and address.
Report income and deductions using the instructions for Form 1041 or Form 5227. The form says that if total income is $25,000 or less, skip lines 1 to 8 and enter total income on line 9.
List, in enough detail, each class of activity for which a disbursement was made and a section 642(c) deduction was taken. The instructions say to give the purpose, not just the category, for example "payments of $4,000 to indigent persons for medical purposes."
List amounts paid out of principal for charitable purposes for each class of activity, in the same level of detail, with each payee's name and address.
Complete the balance sheets using the accounting method the trust uses for its books, in columns (a) and (b). The form says that if line 9 is $25,000 or less, complete only lines 38, 42 and 45.
The trustee or an authorized representative signs and dates the return. A paid preparer also signs and completes the Paid Preparer Use Only area.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions give this address: Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0027.
File by April 15 following the close of the calendar year. If the due date falls on a Saturday, Sunday, or legal holiday, file on the next business day.
The trustee can get an automatic extension by filing Form 8868 on or before the original due date of Form 1041-A.
Section 6652(c)(2) provides for separate penalties of $10 a day, up to a maximum of $5,000, against both the trust and the trustee for not filing on time, unless there is reasonable cause.
The instructions say to complete the entire return, not just the new or corrected information, and enter "Amended Return" across the top.
If more space is needed, attach sheets in the same order as the printed form, with the trust's EIN on each sheet, and show the totals on the printed form.

1041
173 fields, 3 pages
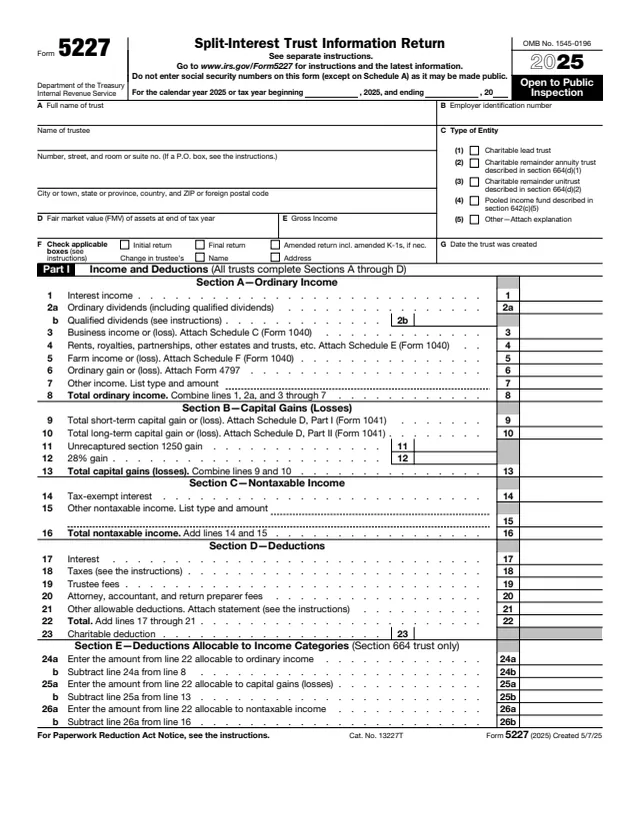
5227
411 fields, 7 pages
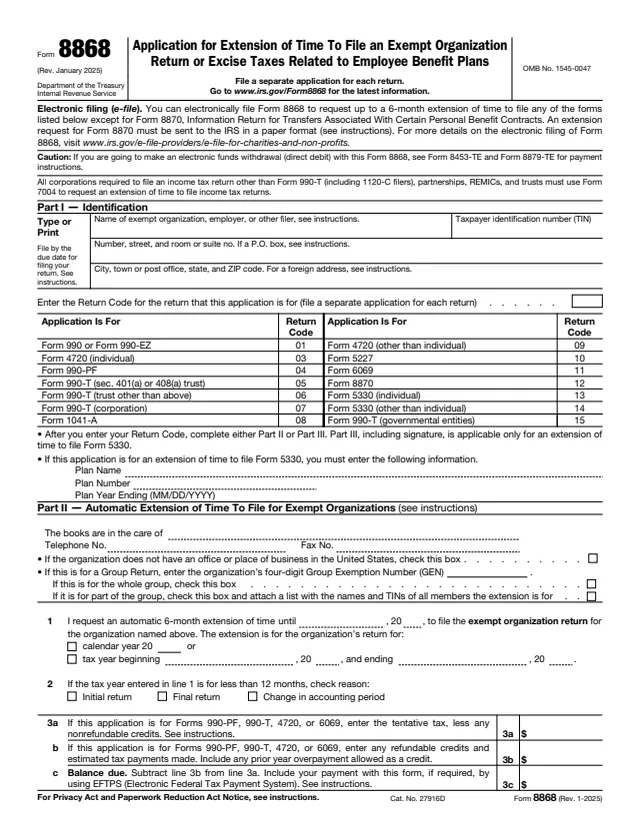
8868
47 fields, 2 pages
4797
182 fields, 2 pages
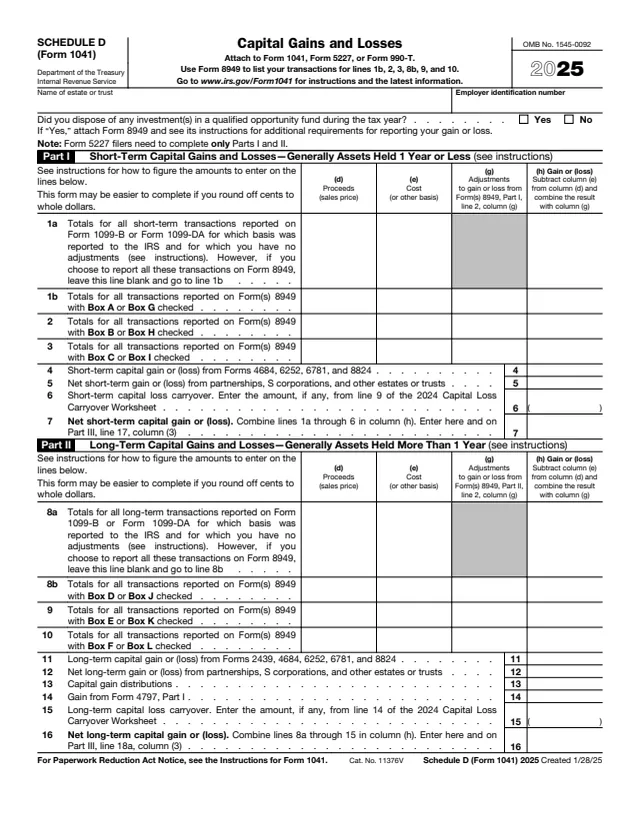
1041
87 fields, 2 pages
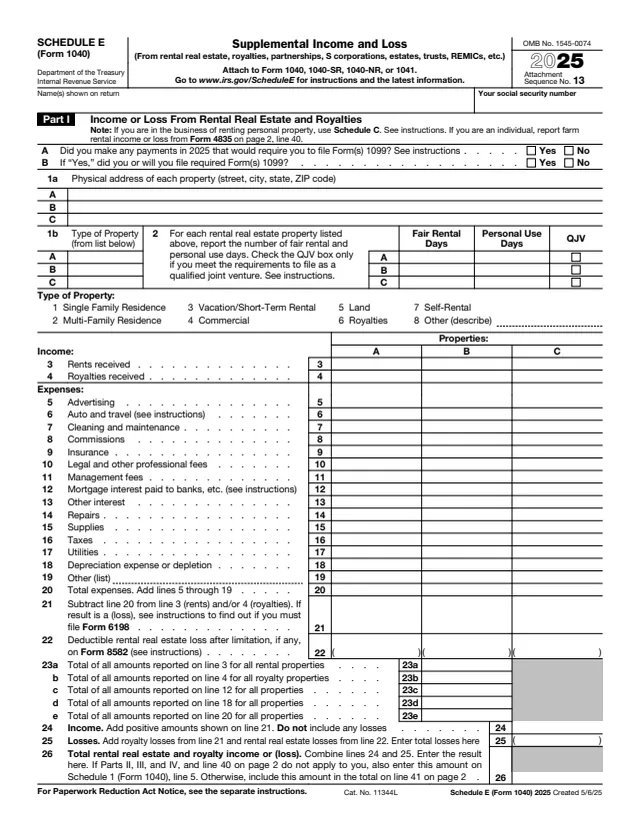
1040
185 fields, 2 pages
The trustee files it with the IRS for the trust. The instructions also name the trusts that don't file it.
No tool matches that search.
The instructions say it is signed by the trustee or by an authorized representative. A paid preparer also signs.
By April 15 following the close of the calendar year, or the next business day if that date falls on a Saturday, Sunday, or legal holiday.
No. The instructions say split-interest trusts described in section 4947(a)(2) file Form 5227, which meets the section 6034 filing requirements.
No. The instructions say electing small business trusts are no longer subject to the charitable information reporting requirements under section 6034.
Yes. The instructions say the trustee may get an automatic extension by filing Form 8868 on or before the original due date.
The instructions point to Regulations section 301.6104(b)-1(d) for the procedures to request public inspection of this form.
The form says to skip lines 1 to 8, enter total income on line 9, and complete only lines 38, 42 and 45 of the balance sheets.