Lines 1a to 1c
Gross proceeds reported to you on Forms 1099-B or 1099-S that you include on line 2, 10 or 20, and the gain and loss from partial dispositions of MACRS assets.
4797
Sales of Business Property (Also Involuntary Conversions and Recapture Amounts Under Sections 179 and 280F(b)(2))
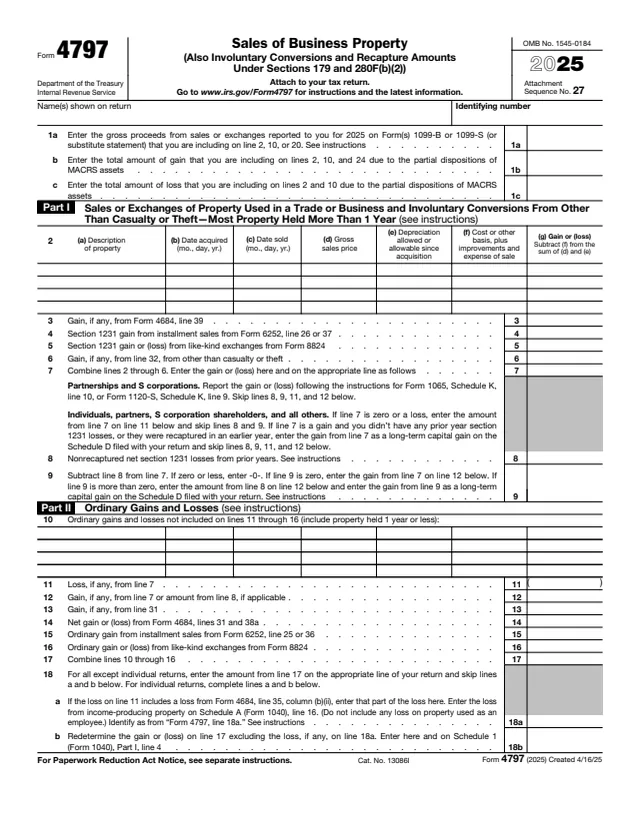
Form 4797, Sales of Business Property, also covers involuntary conversions and recapture amounts under sections 179 and 280F(b)(2). The IRS page says it reports the sale or exchange of property, the involuntary conversion of property and capital assets, the disposition of noncapital assets and of capital assets not reported on Schedule D, and certain section 179 property dispositions by partnerships and S corporations.
It also figures recapture when the business use of section 179 or listed property decreases to 50% or less, and reports ordinary gains or losses for a trader in securities or commodities who made a mark-to-market election under section 475(f).
This page covers the 2025 form. The form says to attach it to your tax return. Gains and losses flow from it to Schedule D, Schedule 1 (Form 1040) or the business return. You can fill out the PDF free in your browser on this page and download it without an account.
Gross proceeds reported to you on Forms 1099-B or 1099-S that you include on line 2, 10 or 20, and the gain and loss from partial dispositions of MACRS assets.
Sales or exchanges of property used in a trade or business and involuntary conversions from other than casualty or theft. Lines 2 to 9 figure the net section 1231 gain or loss.
Lines 10 to 18 cover ordinary gains and losses, including property held 1 year or less, amounts from other parts and forms, and the line 18a and 18b split for individual returns.
Gain from disposition of property under sections 1245, 1250, 1252, 1254 and 1255, with columns for up to four properties A through D on lines 19 to 32.
Lines 33 to 35 figure recapture under section 179 in column (a) and section 280F(b)(2) in column (b) when business use drops to 50% or less.
Enter the name shown on the return and the identifying number. On line 1a, enter the gross proceeds from Forms 1099-B or 1099-S that you include on line 2, 10 or 20.
The instructions chart says where to make the first entry. For example, depreciable trade or business property held more than 1 year goes in Part III at a gain and Part I at a loss. Property held 1 year or less goes in Part II.
Complete lines 19 to 29b for each property, then lines 30 to 32. Line 31 goes to line 13. Line 32 goes to line 6, or to Form 4684 for the casualty or theft portion.
List each sale in columns (a) to (g), add amounts from Forms 4684, 6252 and 8824, and combine on line 7. Line 8 is for nonrecaptured net section 1231 losses from the 5 preceding tax years.
Enter other ordinary gains and losses on line 10, combine lines 10 to 16 on line 17, and for individual returns complete lines 18a and 18b. Show losses in parentheses.
Complete lines 33 to 35. The instructions say the line 35 recapture amount is reported as other income on the same form or schedule on which the deduction was taken.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." Its attachment sequence number is 27. It has no separate mailing address.
A line 7 or line 9 gain goes to Schedule D as a long-term capital gain. Line 18b goes to Schedule 1 (Form 1040), Part I, line 4. Other returns use the appropriate line.
The instructions name Form 4684 for casualties and thefts, Form 6252 for installment sales and Form 8824 for like-kind exchanges. Results from those forms go on lines 3 to 5 and 14 to 16.
The instructions say Form 8949 reports sales of capital assets not reported on another form or schedule, and Schedule D figures the overall gain or loss.
The instructions say a sale of a group of assets that make up a trade or business is also reported on Form 8594, Asset Acquisition Statement.
Part III has columns for four properties. The instructions say to use additional forms for more.
8949
202 fields, 2 pages
1040
55 fields, 2 pages
4684
162 fields, 4 pages
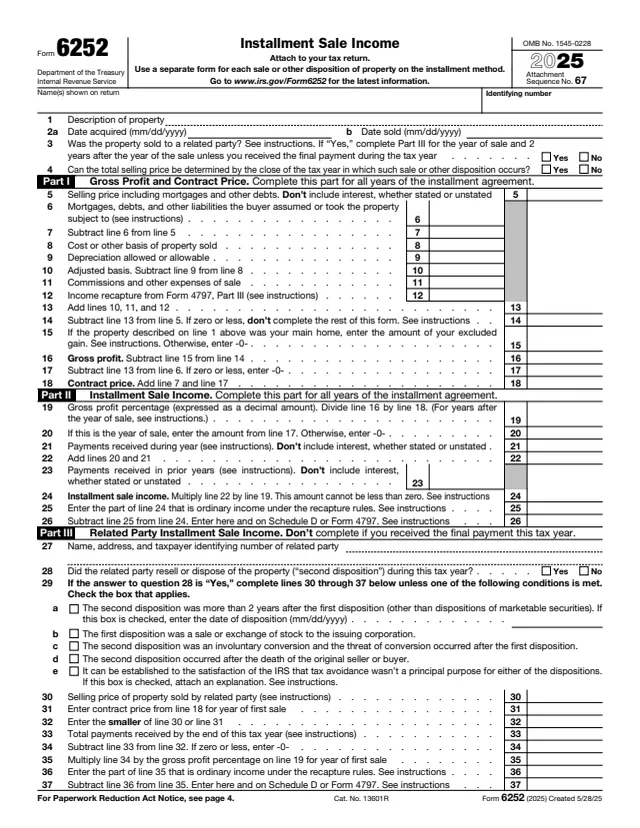
6252
49 fields, 4 pages
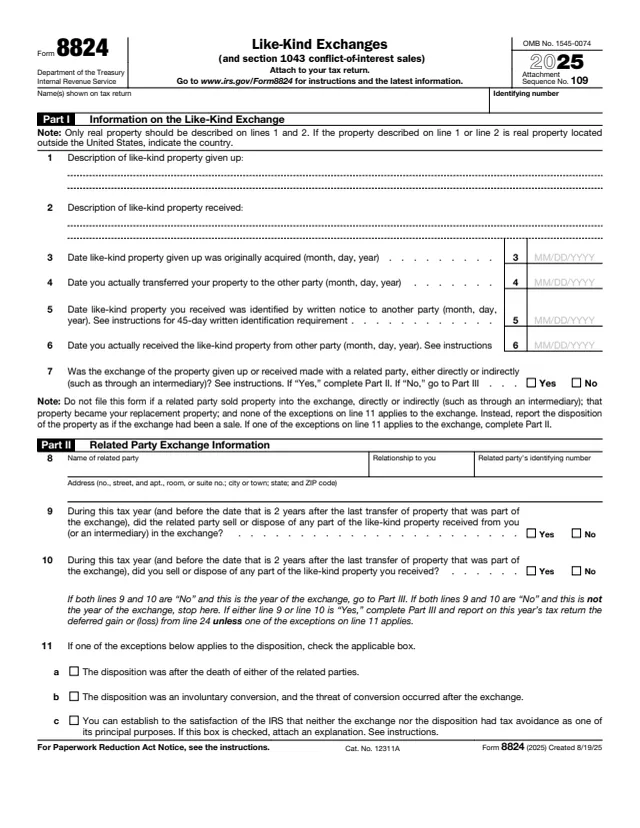
8824
63 fields, 2 pages
4255
646 fields, 5 pages
The form gives separate directions for individuals, partners and S corporation shareholders, partnerships and S corporations, and all other returns.
No tool matches that search.
The IRS page says it reports sales or exchanges of property, involuntary conversions, dispositions of noncapital assets and of capital assets not on Schedule D, certain section 179 dispositions, and recapture when business use drops to 50% or less.
No. The instructions say Form 8949 reports the sale or exchange of capital assets not reported on another form or schedule. Form 4797 covers business property and recapture.
The instructions chart depends on the type of property, gain or loss and holding period. Property held 1 year or less generally goes in Part II. Depreciable property held longer goes in Part III at a gain.
The instructions say they are net section 1231 losses deducted during the 5 preceding tax years that have not yet been applied against a net section 1231 gain. They go on line 8.
The instructions say partnerships and S corporations do not report those transactions on Form 4797. They give partners and shareholders the information on Schedule K-1.
It is not mailed on its own. The form says to attach it to your tax return.