Lines 1 to 4: the sale
A code and description of the property, the dates acquired and sold, whether the property was sold to a related party, and whether the total selling price can be determined by the close of the tax year.
6252
Installment Sale Income
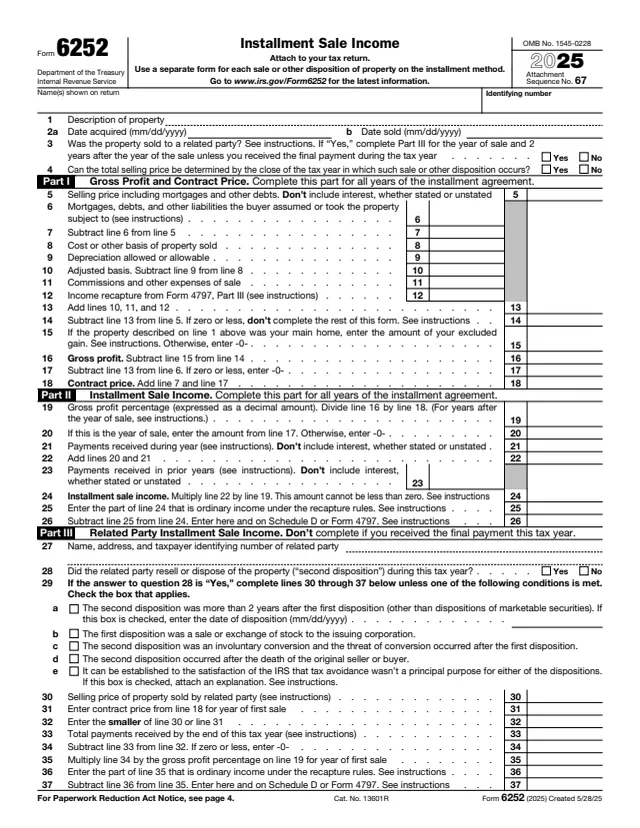
Form 6252 is used to report income from an installment sale on the installment method. The IRS says that, generally, an installment sale is a disposition of property where at least one payment is received after the end of the tax year in which the disposition occurs. The form is attached to the seller's tax return, and a separate Form 6252 is used for each sale or other disposition of property on the installment method.
The instructions say to file Form 6252 for the year of the disposition and all later years, whether or not a payment is received in a given year, until and including the year the final payment is received or the obligation is disposed of. The form works out the gross profit, the contract price, the gross profit percentage and the installment sale income for the year. Part III covers sales to a related party.
The PDF on this page prints the year 2026 and carries its own instructions on pages 2 to 4. You can fill it out free in your browser on this page and download the result without an account.
A code and description of the property, the dates acquired and sold, whether the property was sold to a related party, and whether the total selling price can be determined by the close of the tax year.
Lines 5 to 18: selling price, debts the buyer assumed, cost or other basis, depreciation, selling expenses, income recapture from Form 4797, excluded gain on a main home, gross profit and contract price.
Lines 19 to 26: the gross profit percentage, payments received this year and in prior years, the installment sale income, the part that is ordinary income under the recapture rules, and the amount for Schedule D or Form 4797.
Lines 27 to 37: the related party's name, address and identifying number, whether it resold the property this year, five exception boxes on line 29, and the figures for income from the second disposition.
Purpose of the form, which parts to complete, special rules on interest, related party sales, the pledge rule and interest on deferred tax, and line by line instructions.
Enter a code and describe the property. The instructions list code 1 for a timeshare or residential lot, code 2 for a sale by an individual of personal-use property, code 3 for property used or produced in farming, and code 4 for all other installment sales.
Line 5 holds the selling price, including debts the buyer assumed, but not interest. Line 6 holds only debts the buyer assumed from the seller or took the property subject to, not new loans. The instructions say not to file the form if line 14 is zero or less.
Enter the gross profit percentage as a decimal rounded to at least 4 digits, for example 25% = 0.2500. For years after the year of sale, the instructions say to use the percentage determined for the year of sale.
Line 21 holds all money and the fair market value of property or services received this tax year, without interest. Line 23 holds what was received in prior years, including deemed payments such as a related party's second disposition or the pledge rule.
Line 25 holds the part of line 24 that is ordinary income under the recapture rules, and it is not more than line 24. Line 26 goes to Schedule D for capital assets or to Form 4797 for trade or business property, as the instructions explain.
Complete it for the year of sale and 2 years after when the buyer is a related party, unless the final payment came in this year. If a condition on line 29 is met, check its box and skip lines 30 to 37. Box 29e needs an attached explanation.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. A separate Form 6252 is used for each sale or other disposition of property on the installment method.
The instructions say to complete lines 1 to 4, Part I and Part II for each year of the installment agreement, including the year of final payment, even if no payment was received during the year.
Interest, carrying charges, original issue discount and unstated interest are not reported on Form 6252. The instructions point to Pub. 537, Installment Sales, for details.
To elect out, the instructions say to report the selling price on Form 4797, Form 8949 or Schedule D on a timely filed return. An amended return filed no later than 6 months after the due date, excluding extensions, can carry the election with "Filed pursuant to section 301.9100-2" at the top.
The instructions describe interest on deferred tax when the sales price is over $150,000 and the balance of nondealer installment obligations at year end is more than $5 million. That interest is not figured on Form 6252.
4797
182 fields, 2 pages
8949
202 fields, 2 pages
1040
55 fields, 2 pages
8997
143 fields, 4 pages

1040
199 fields, 2 pages

1041
173 fields, 3 pages
The form is completed by the seller of the property and attached to the seller's own tax return.
No tool matches that search.
The instructions say that, generally, it is a disposition of property where at least one payment is received after the end of the tax year in which the disposition occurs.
No. The instructions say the installment method can be used only if the sale results in a gain, and a loss cannot be claimed under it. The entire sale goes on Form 4797, Form 8949 or Schedule D.
Yes. The instructions say to complete lines 1 to 4, Part I and Part II for each year of the installment agreement, even if no payment was received during the year.
Not on Form 6252. The instructions say to report interest or original issue discount on the appropriate form or schedule for the year it is includible in income.
For this purpose the instructions list a spouse, child, grandchild, parent or sibling, or a related corporation, S corporation, partnership, estate or trust, and point to section 453(f)(1).
Line 15 holds the excluded gain if the property on line 1 was the seller's main home. The instructions point to Pub. 523, Selling Your Home, for details.