Part I: holdings at the start of the year
QOF investment holdings due to deferrals before the start of the tax year. If they differ from last year's ending holdings, the form says to attach an explanation.
8997
Initial and Annual Statement of Qualified Opportunity Fund (QOF) Investments
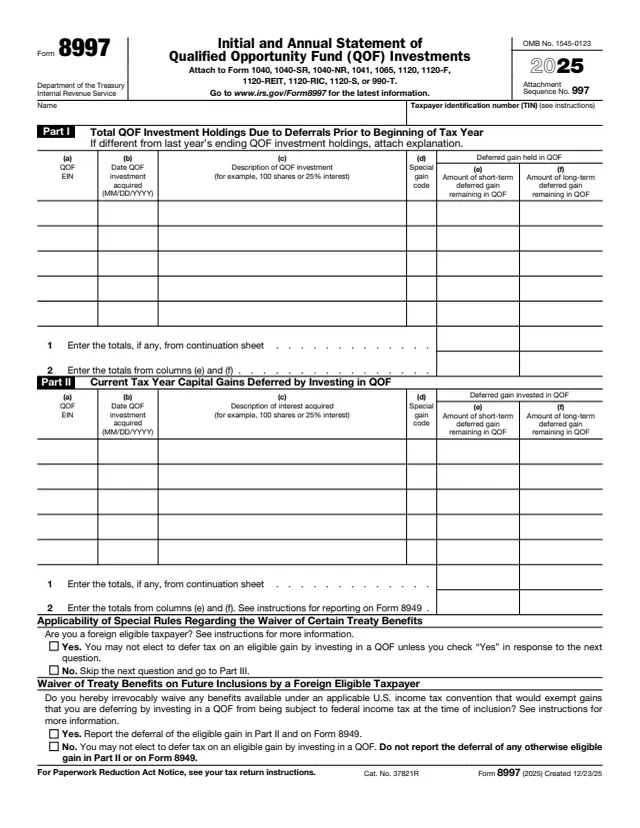
Form 8997, Initial and Annual Statement of Qualified Opportunity Fund (QOF) Investments, is used by an investor in a QOF to inform the IRS of the QOF investments and deferred gains held at the beginning and end of the tax year, any capital gains deferred by investing in a QOF, and QOF investments disposed of during the year.
This is the 2025 form. It says to attach it to Form 1040, 1040-SR, 1040-NR, 1041, 1065, 1120, 1120-F, 1120-REIT, 1120-RIC, 1120-S or 990-T. Its four parts list holdings at the start of the year, current year deferrals, inclusion events and year end holdings, each by QOF EIN, date, description, special gain code and short-term or long-term deferred gain. The instructions are printed on pages 3 and 4 of the form.
You can fill out Form 8997 free in your browser on this page and download the PDF without an account.
QOF investment holdings due to deferrals before the start of the tax year. If they differ from last year's ending holdings, the form says to attach an explanation.
Capital gains deferred during the year by investing in a QOF, followed by the foreign eligible taxpayer and treaty benefit waiver questions.
Inclusion events and certain other transfers during the year, with a box to check for a disposition without a Form 1099-B from the QOF or other third party.
Total QOF investments due to deferrals at the end of the tax year.
Each part asks for the QOF EIN, a date, a description, a special gain code, and short-term and long-term deferred gain amounts, with a line for continuation sheet totals and a totals line.
Individuals enter an SSN or ITIN. C corporations, partnerships, S corporations, non-grantor trusts, estates and Indian tribes enter an EIN.
List each QOF investment held at the start of the year, generally January 1, 2025 for individuals, and enter the remaining deferred gain in column (e) or (f) depending on whether it was short-term or long-term.
Report capital gains deferred this year by investing in a QOF. The form points to its instructions for reporting the line 2 totals on Form 8949.
Codes A to H mark gains from section 1256, Form 4797 (section 1231), straddles, collectibles, a treaty exemption, a noninclusion transfer, or a 5-year or 7-year basis adjustment.
Report each inclusion event. If a regulatory exception applies, enter "Exception" and the citation in column (c) and leave columns (d) to (f) blank. For a 5-year or 7-year basis adjustment, use code G or H.
List holdings at year end, generally December 31, 2025 for individuals. If an investment continues one in a different QOF, enter "Formerly" and the earlier QOF's EIN in column (c).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach it to the return listed on the form: Form 1040, 1040-SR, 1040-NR, 1041, 1065, 1120, 1120-F, 1120-REIT, 1120-RIC, 1120-S or 990-T.
The instructions say it is filed with the taxpayer's timely filed federal income tax return, including extensions.
If there are more QOF investments than lines in a part, attach and label a separate continuation sheet and carry its totals to line 1 of that part.
The instructions say a QOF investment is also reported on Form 8949.
The instructions say the investment generally must have occurred within the 180-day period beginning on the date the gain would be recognized if the taxpayer did not elect to defer it.
8996
479 fields, 4 pages
8949
202 fields, 2 pages

1040
199 fields, 2 pages
1040-NR
171 fields, 2 pages

1065
440 fields, 6 pages

1120
481 fields, 6 pages
The instructions say an eligible taxpayer holding a QOF investment at any point during the tax year files Form 8997 with its timely filed federal income tax return (including extensions).
No tool matches that search.
The instructions describe it as an investment vehicle organized as a corporation or partnership to invest in qualified opportunity zone property (other than another QOF) that holds at least 90% of its assets in that property.
An eligible taxpayer holding a QOF investment at any point during the tax year, with its timely filed federal income tax return, including extensions.
On pages 3 and 4 of the form itself. The About page lists no separate instructions.
The What's New section says an investment held at least 7 years may be eligible for an additional 5% basis increase, for a total of 15% of the deferred gain. It is reported in Part III with code H.
Check the box in Part III if a QOF investment was disposed of during the year and no Form 1099-B reporting it came from the QOF or another third party.
The form says a foreign eligible taxpayer may not elect to defer tax on an eligible gain by investing in a QOF unless it checks Yes to the treaty benefit waiver.