8996

Qualified Opportunity Fund

Agency
IRS
Revision
Rev. December 2021
Fillable fields
479
Pages
4
Official source
IRS form page
Checked
October 21, 2026
Fill 8996 online
Page 1 of form 8996

Form 8996: Qualified Opportunity Fund

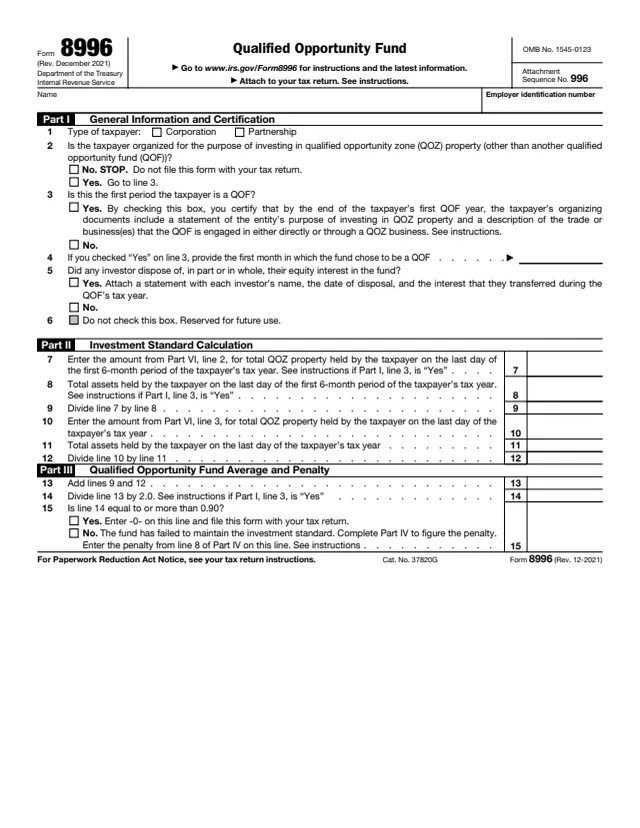
Form 8996, Qualified Opportunity Fund, is used to certify that a corporation or partnership is a qualified opportunity fund (QOF). The IRS About page says it is also used to annually report whether the QOF met the investment standard during its tax year.

The instructions describe a QOF as an investment vehicle organized as a corporation or partnership to invest in qualified opportunity zone (QOZ) property, and say a QOF must hold at least 90% of its total assets in QOZ property. The form measures this on the last day of the first 6-month period of the tax year and on the last day of the tax year, and Part IV figures a penalty for the months the standard was not met.

The form says to attach it to the fund's tax return. You can fill it out free in your browser on this page and download the result without an account.

What's on Form 8996

Part I: General Information and Certification

Lines 1 to 6: corporation or partnership, whether the taxpayer is organized to invest in QOZ property, whether this is the first QOF period and its first month, and whether any investor disposed of an equity interest. Line 6 is reserved.


Part II: Investment Standard Calculation

Lines 7 to 12 compare QOZ property with total assets on the last day of the first 6-month period and on the last day of the tax year.

Part III: Average and Penalty

Lines 13 to 15 average the two ratios and ask whether the result is equal to or more than 0.90. If it is not, the penalty from Part IV goes on line 15.

Part IV: Line 15 Penalty

Twelve monthly columns for total assets, 90% of that amount, QOZ property, the shortfall, the underpayment rate and the monthly amount, added up on line 8.

Part V: Property Owned or Leased Directly

Each QOZ where the taxpayer directly owns or leases QOZ business property, with owned and leased values at both test dates.

Parts VI and VII: QOZ Stock or Partnership Interests

Each QOZ business by QOZ number and EIN, with investment values and owned and leased tangible property at both test dates. Part VII is a continuation. Part VI, line 4 records the valuation method.

How to fill out Form 8996

  1. 1

    Name and EIN

    Enter the same name and employer identification number shown on the fund's tax return, then check corporation or partnership on line 1.

  2. 2

    Part I, lines 2 to 5

    Line 2 Yes is a self-certification as a QOF, and the instructions say to complete the entire form. Line 3 Yes is for the first QOF period, with the first month on line 4. A Yes on line 5 needs a statement with each investor's name, TIN, date of disposition and the interest disposed of.

  3. 3

    Parts V to VII

    Enter each QOZ by its 11-digit number, and non-QOZs as 99999999999. Part VI, lines 2 and 3 add Part V and Part VI values for each test date and carry them to Part II, lines 7 and 10. Check the valuation method on Part VI, line 4.

  4. 4

    Part II

    Enter QOZ property and total assets for each test date, then divide. The instructions say to enter each result as a decimal to two places, for example 92% as 0.92 and 100% as 1.00.

  5. 5

    Part III

    Add lines 9 and 12 and divide by 2.0, or use line 13 alone when lines 7 through 9 are blank. If line 14 is 0.90 or more, enter -0- on line 15. Otherwise complete Part IV.

  6. 6

    Part IV

    For each month, multiply total assets by 0.90, subtract QOZ property, apply the underpayment rate and divide by 12.0. Add the months on line 8 and carry the total to Part III, line 15.

Why fill Form 8996 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, deadlines and the penalty notice

Attach to the tax return

The instructions say a QOF files Form 8996 annually with its Form 1120, 1120-F, 1120-REIT, 1120-RIC, 1120-S or 1065, as applicable.

Deadline

The instructions say to file Form 8996 by the due date of the tax return, including extensions.

Every year

Parts I, II, III, V and VI are completed annually. Part IV is completed only when line 15 is answered No, and Part VII only when more lines are needed.

Penalty notice

The instructions say the IRS sends a notice about the penalty reported on line 15, with instructions on the penalty, the reasonable cause relief process and payment.

Recent developments

The About page lists updates to the Instructions for Form 8996 (Rev. 12-2024) due to Notice 2025-50, dated 24-NOV-2025.

Who files Form 8996?

  • Corporations operating as a QOF

    The instructions list Form 1120, Form 1120-F, Form 1120-REIT, Form 1120-RIC and Form 1120-S as the returns the form is filed with.

  • Partnerships operating as a QOF

    A partnership organized and operated as a QOF files the form with Form 1065, U.S. Return of Partnership Income.

  • Funds organized in a U.S. territory

    The instructions say a QOF organized in a U.S. territory is eligible to attach Form 8996 to its Form 1120-F.

  • Consolidated groups

    The instructions say a consolidated group should include with its return a separate Form 8996 for each group member that must certify its QOF status.

  • Not QOZ businesses

    The instructions say qualified opportunity zone businesses do not file Form 8996. If line 2 is answered No, the form says not to file it with the tax return.

The instructions say a corporation or partnership that is organized and operated as a QOF files it annually with its tax return. Completing it is a self-certification of QOF status.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 8996

Do QOZ businesses file Form 8996?

No. The instructions say qualified opportunity zone businesses do not file Form 8996. It is filed only by entities that self-certify as a QOF or certify that they met the 90% investment standard.

What is the 90% investment standard?

The instructions say a QOF must hold at least 90% of its total assets in QOZ property, measured as the average of the percentages on the last day of the first 6-month period and the last day of the tax year.

When is Form 8996 due?

The instructions say it is filed by the due date of the fund's tax return, including extensions.

What goes on line 4 for a new fund?

The first month in which the fund chose to be a QOF. The instructions say this month cannot be any earlier than the month in which the entity forms.

How is a location outside a QOZ entered?

The form and instructions say to indicate non-QOZs by 99999999999 in column (a) of Parts VI and VII.

What if line 14 is below 0.90?

The form says the fund has failed to maintain the investment standard. Part IV figures the penalty, and the instructions say the IRS sends a notice about it.