Part I: the exchange
Lines 1 to 7: descriptions of the property given up and received, the dates acquired, transferred, identified and received, and whether a related party was involved.
8824
Like-Kind Exchanges (and section 1043 conflict-of-interest sales)
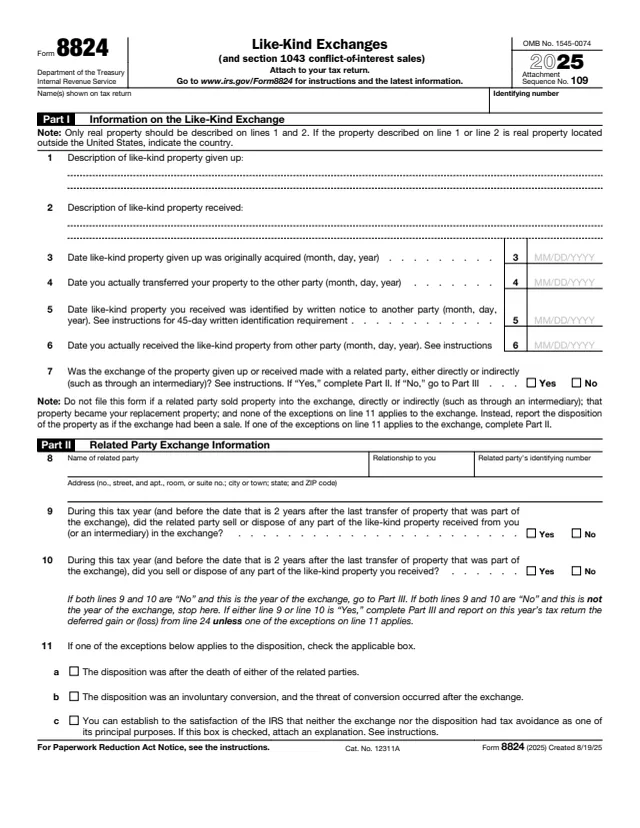
Form 8824 is used to report each exchange of business or investment real property for real property of a like kind. The instructions say it figures the amount of gain deferred as a result of a like-kind exchange, the gain to report in the current year when cash or property that is not of a like kind is involved, and the basis of the like-kind property received.
Part IV serves a different group: certain members of the executive branch and judicial officers of the federal government use it to elect to defer gain on sales made to comply with conflict-of-interest requirements under section 1043. The form says to attach it to your tax return, and the IRS About page lists it alongside returns such as Forms 1041, 1065, 1120 and 1120-S.
The instructions note that for 2018 and later years, section 1031 treatment applies only to exchanges of real property held for use in a trade or business or for investment. This page covers the 2025 form. You can fill it out free in your browser on this page and download the result without an account.
Lines 1 to 7: descriptions of the property given up and received, the dates acquired, transferred, identified and received, and whether a related party was involved.
Lines 8 to 11: the related party's name, relationship, identifying number and address, whether either party disposed of the property within 2 years, and the exceptions.
Lines 12 to 14 apply only when property that was not like-kind was given up: its fair market value, adjusted basis and the gain or loss recognized.
Lines 15 to 25: cash and other property received, realized gain or loss, recapture, recognized gain, deferred gain and the basis of the like-kind property received.
Lines 26 to 38: the certificate of divestiture number, the divested and replacement property, the sale date, price and basis, and the deferred gain.
Describe the property given up and received. The form says only real property should be described here. The instructions say to enter the address and type of property, and the country for property outside the United States.
Enter the dates as MM/DD/YYYY. The instructions say replacement property is identified in writing no later than 45 days after the transfer, and received by the 180th day or the return due date with extensions, whichever is earlier.
Answer whether the exchange was made with a related party, directly or indirectly. The instructions list a spouse, child, grandchild, parent, grandparent, brother, sister, or certain related entities. If Yes, complete Part II; if No, go to Part III.
Complete lines 12 to 14 only for property given up that was not like-kind. Then enter cash and other property received, the fair market value of the like-kind property received, and the adjusted basis of the property given up.
Figure realized gain, recapture on line 21 (also entered on Form 4797, line 16), the gain for Schedule D or Form 4797 on line 22, deferred gain on line 24 and the basis of property received on line 25.
Enter the number from the upper right corner of the certificate of divestiture, the sale details, and the cost of replacement property purchased within 60 days after the sale. The form says not to attach the certificate.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return, and the instructions say to file it with the return for the year of the transfer.
The instructions say to also file Form 8824 for the 2 years following the year of a related party exchange, completing Parts I and II and Part III only when line 9 or 10 is Yes.
The form says not to file it when a related party sold the replacement property into the exchange and no line 11 exception applies. The disposition is then reported as if the exchange had been a sale.
Line 21 goes on Form 4797, line 16. Line 22 goes on Schedule D or Form 4797 unless the installment method applies. Line 35 goes on Form 4797, line 10.
For Part IV, the form says not to attach a copy of the certificate and to keep it with your records.
4797
182 fields, 2 pages
1040
55 fields, 2 pages
6252
49 fields, 4 pages
8949
202 fields, 2 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
The form is attached to the tax return of the person or entity that made the exchange or sale, and goes to the IRS with that return.
No tool matches that search.
The instructions say that for 2018 and later years, section 1031 like-kind exchange treatment applies only to exchanges of real property held for use in a trade or business or for investment, other than real property held primarily for sale.
For a deferred exchange, the instructions say replacement property is identified within 45 days after the property given up is transferred, and received within 180 days or by the return due date including extensions, whichever is earlier.
The instructions say real property in the United States and real property outside the United States are not like-kind properties.
The instructions say you can file a summary on one Form 8824 and attach your own statement with the information requested for each exchange.
The form says only officers or employees of the executive branch or judicial officers of the federal government, including certain spouses, children and trustees, for section 1043 conflict-of-interest sales.
No. The form says not to attach a copy of the certificate and to keep it with your records.