Items A to E: heading
The organization's name and EIN, the unrelated business activity code, the sequence number of this schedule, and a description of the unrelated trade or business.
990-T
Unrelated Business Taxable Income From an Unrelated Trade or Business
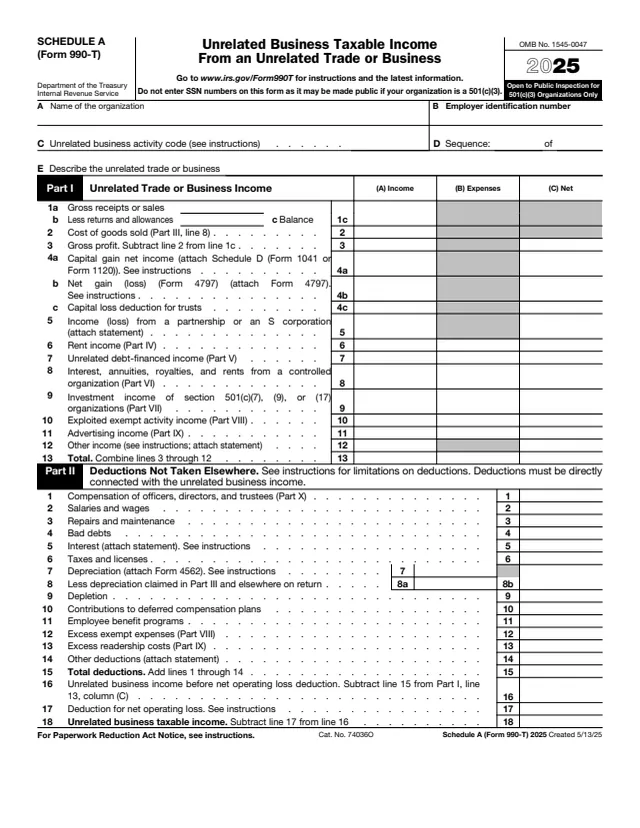
Schedule A (Form 990-T) reports the income and allowable deductions of one unrelated trade or business of a tax-exempt organization. The Instructions for Form 990-T say to complete a separate Schedule A for each separate unrelated trade or business, because unrelated business taxable income (UBTI) is figured separately for each one. Each trade or business is identified by a business activity code based on the two-digit NAICS code that most accurately describes it.
The 2025 schedule has 11 parts. Part I lists income, Part II lists deductions and ends with unrelated business taxable income on line 18, and Parts III to X hold the detail behind certain lines, such as cost of goods sold, rents, debt-financed income, payments from controlled organizations, and advertising income. Part XI is for supplemental information. The instructions say to complete all Schedules A first and attach them to Form 990-T.
The organization or trust that files Form 990-T completes it. You can fill out Schedule A (Form 990-T) free in your browser on this page and download it without an account.
The organization's name and EIN, the unrelated business activity code, the sequence number of this schedule, and a description of the unrelated trade or business.
Lines 1a to 13 in three columns, (A) Income, (B) Expenses, and (C) Net, covering gross receipts, cost of goods sold, capital gains, partnership and S corporation income, rents, debt-financed income, controlled organization payments, investment income, exploited activity income, advertising, and other income.
Lines 1 to 14 for deductions directly connected with the unrelated business income, such as officer compensation, salaries, repairs, interest, taxes, and depreciation, then the net operating loss deduction on line 17 and unrelated business taxable income on line 18.
Part III, Cost of Goods Sold; Part IV, Rent Income from real property and personal property leased with real property; and Part V, Unrelated Debt-Financed Income, with columns A to D for up to four properties.
Part VI covers interest, annuities, royalties, and rents from controlled organizations; Part VII, investment income of a section 501(c)(7), (9), or (17) organization; Part VIII, exploited exempt activity income; Part IX, advertising income; and Part X, compensation of officers, directors, and trustees.
Explanations of the organization's operations and support for amounts reported on the schedule, including any change of business activity code from a prior year.
Enter the same name as on Form 990-T and the EIN from item D of Form 990-T. Item C takes a 6-digit entry: the instructions give the example of entering 450000 when the 2-digit code 45, retail trade, best describes the business.
Enter income in column (A) and expenses in column (B). Lines 2 and 6 to 11 are carried in from the part each line names, such as Part III, line 8, for cost of goods sold on line 2. Line 13 combines lines 3 through 12.
Deduct only expenses directly connected with this trade or business, and don't repeat expenses already reported in Parts III to IX, except excess exempt expenses on line 12 and excess readership costs on line 13. The instructions say line 17 is not more than line 16.
If line 13, column (A), of all Schedules A totals $10,000 or less, the instructions say to complete the heading, the Part I lines that apply, and Part II, lines 15 to 18. Parts III to X are filled only where Part I lines point to them.
List each property's address and check the dual-use box if it is used for both exempt and unrelated activities. In Part V, line 6 divides average acquisition debt by average adjusted basis, and the instructions say the percentage cannot be more than 100%.
For each entry, include the Schedule A part and line number, a brief description, and any amount. An organization that changed its business activity code from a prior year can enter the explanation here.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
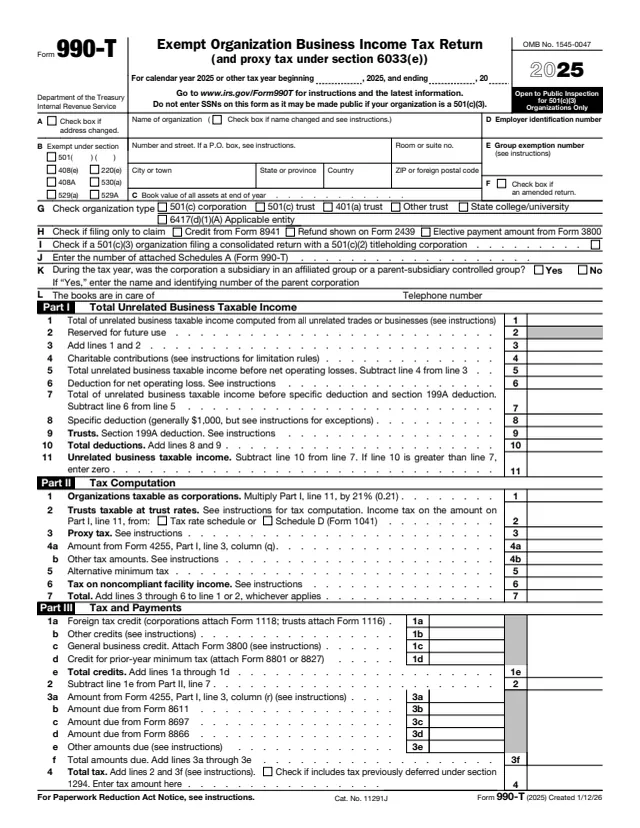
Each Schedule A is completed first and attached to Form 990-T. Form 990-T, Part I, line 1, adds only the positive amounts from every Schedule A, Part II, line 18.
The instructions say an organization or trust defined in section 511 that needs to file Form 990-T is required to file electronically.
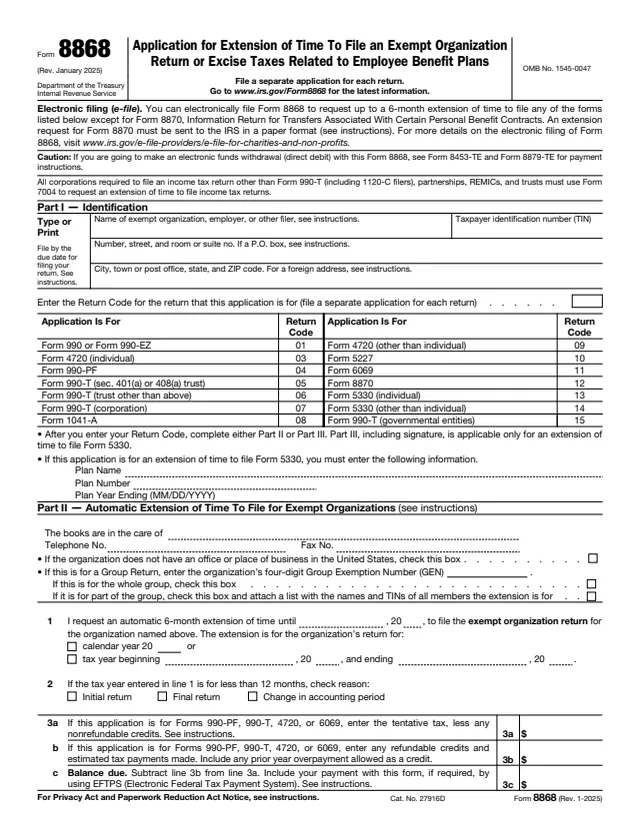
The instructions say employees' trusts, IRAs, Roth IRAs, Coverdell ESAs, and Archer MSAs file Form 990-T by the 15th day of the 4th month after the tax year ends, and all other organizations by the 15th day of the 5th month. Form 8868 requests an extension.
The schedule is marked Open to Public Inspection for 501(c)(3) Organizations Only, and says not to enter SSN numbers because the form may be made public if the organization is a 501(c)(3).
The instructions say each NAICS two-digit code is used only once and kept in later years. A change is reported in an attached statement with the old and new codes, the sequence numbers, and the reason.
990-T
128 fields, 2 pages
8868
47 fields, 2 pages
4562
277 fields, 3 pages
4797
182 fields, 2 pages
8582
205 fields, 3 pages
990
1,075 fields, 12 pages
The Instructions for Form 990-T say organizations with unrelated business taxable income complete Form 990-T and a separate Schedule A (Form 990-T) for each separate unrelated trade or business.
No tool matches that search.
One for each separate unrelated trade or business. The instructions say an exempt organization may not aggregate income and deductions from all its unrelated trades or businesses when calculating UBTI.
No. The instructions say an organization with no unrelated business taxable income that needs to file Form 990-T completes and files Form 990-T only.
If all Schedules A together show $10,000 or less on Part I, line 13, column (A), the instructions say Parts III to X are not required, except where entries there fill lines in Parts I and II.
The instructions say UBTI for any one trade or business is not less than zero for this purpose, and Form 990-T, Part I, line 1, does not include any Schedule A, Part II, line 18 amount that is less than zero.
The schedule header says it is open to public inspection for 501(c)(3) organizations only, and tells filers not to enter SSN numbers on it.
The instructions say a section 501(c)(7) social club reports restaurant and bar receipts from nonmembers on Part I, line 1a, and its investment income on Part I, line 9, and in Part VII.