Heading
The tax year beginning and ending dates, the name of the corporation and its employer identification number.
973
Corporation Claim for Deduction for Consent Dividends
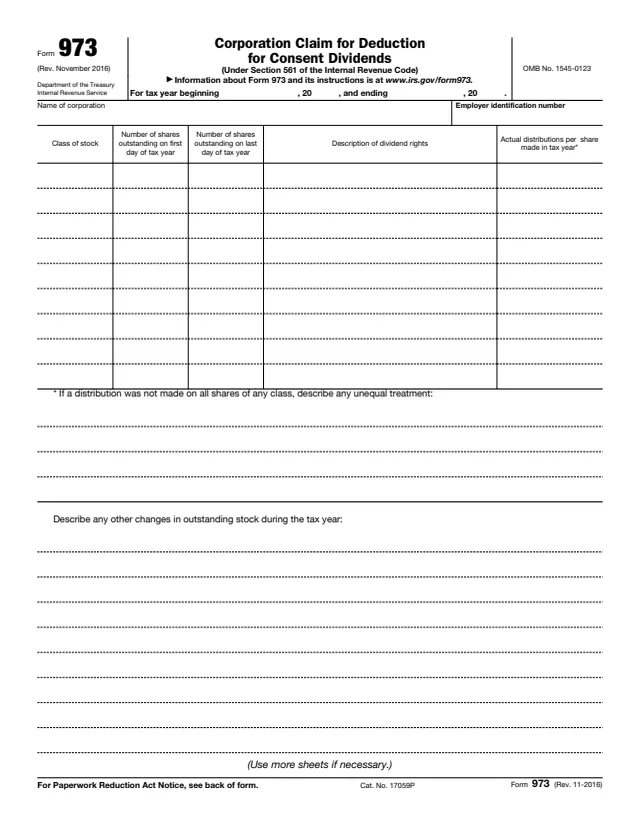
Form 973 is filed by a corporation claiming a consent dividend deduction under section 565 of the Internal Revenue Code. A consent dividend is an amount a shareholder agrees, on Form 972, to treat as a taxable dividend. The corporation reports details about each class of its stock for the tax year and attaches the shareholders' consents.
The instructions say the consent dividend provisions apply to corporations that reasonably believe they are subject to the accumulated earnings tax, personal holding companies, foreign personal holding companies, regulated investment companies and real estate investment trusts. Form 973 is attached to the corporation's income tax return for the tax year the deduction is claimed, together with the signed Form 972 from each consenting shareholder or an unsigned Form 972 with the same information.
This page has the November 2016 revision. You can fill out the PDF free in your browser on this page and download the result without an account.
The tax year beginning and ending dates, the name of the corporation and its employer identification number.
For each class: shares outstanding on the first and last day of the tax year, a description of dividend rights, and actual distributions per share made in the tax year.
If a distribution was not made on all shares of any class, a description of any unequal treatment.
A description of any other changes in outstanding stock during the tax year.
For stock entitled to cumulative dividends, the amount for earlier years unpaid at the beginning of the tax year and the class or classes involved.
Fill in the beginning and ending dates of the tax year, the corporation's name and its employer identification number.
Enter the shares outstanding on the first and last day of the tax year, the dividend rights and the actual distributions per share. The form says to use more sheets if necessary.
Describe any unequal treatment where a distribution was not made on all shares of a class, and any other changes in outstanding stock during the year.
On page 2, show unpaid cumulative dividends from earlier years for any class of stock entitled to them.
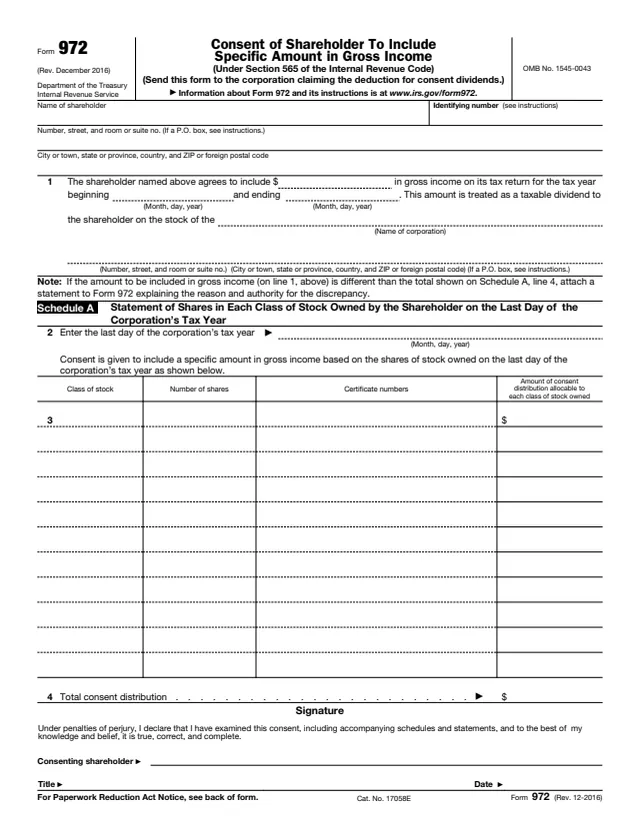
Gather a Form 972 from each shareholder who agreed to treat the consent dividend as a taxable dividend. The deduction may only be taken as to the amounts stated on them.
Attach Form 973 and the Forms 972 to the corporation's income tax return for the tax year the deduction is claimed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 973 to the corporation's income tax return for the tax year the corporation claims the consent dividend deduction.
For each consenting shareholder, the corporation attaches the signed Form 972 or an unsigned Form 972 with the same information. With an unsigned copy, the original signed form stays in its records.
The deduction may only be taken as to the amount stated on Form(s) 972, for consent stock under section 565(f)(1), that is not a preferential dividend and would be a dividend if actually paid.
For a Form 972 from a nonresident alien or other foreign shareholder, the instructions say the corporation pays the withholding tax it would have withheld if the dividend had been actually paid.
The instructions name Form 1042, Form 1042-S and Form 1042-T to report and send the tax withheld.
972
56 fields, 2 pages
1042
134 fields, 2 pages
1042-S
300 fields, 7 pages
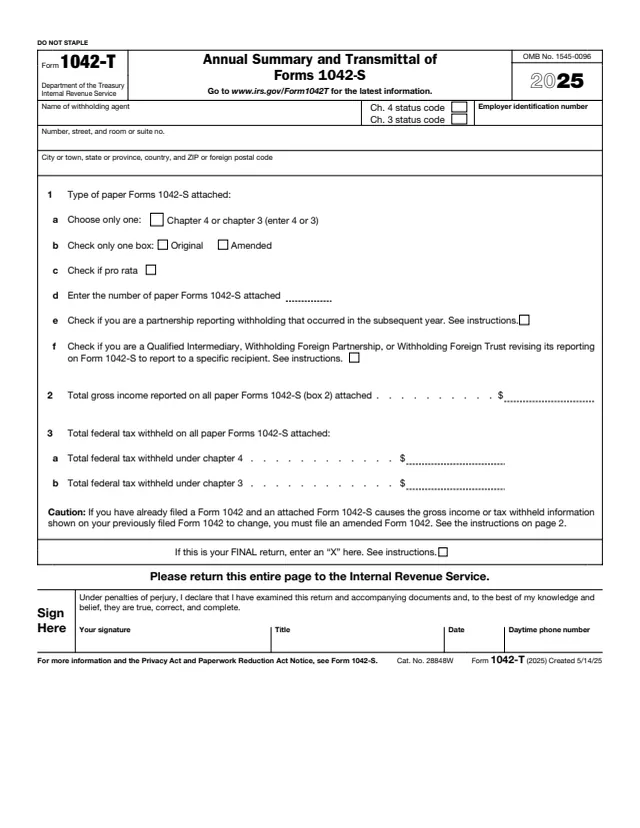
1042-T
19 fields, 2 pages
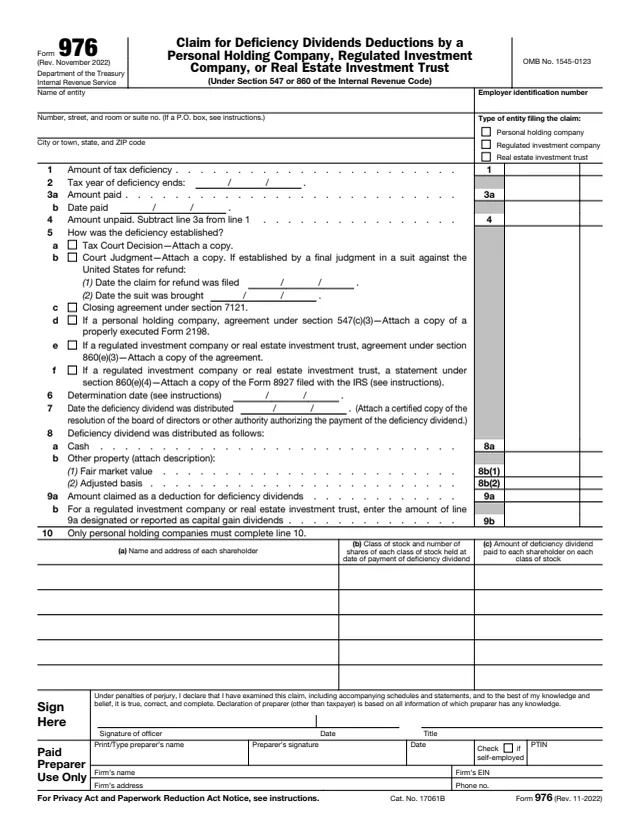
976
70 fields, 2 pages
A corporation files it with its own income tax return. Shareholders do not file Form 973; they sign Form 972 and send it to the corporation.
No tool matches that search.
A corporation claiming a consent dividend deduction under section 565. The instructions list corporations that reasonably believe they are subject to the accumulated earnings tax, personal holding companies, foreign personal holding companies, regulated investment companies and real estate investment trusts.
No. The instructions say to attach it to the corporation's income tax return for the tax year the consent dividend deduction is claimed.
Form 972 is the shareholder's consent, sent to the corporation. Form 973 is the corporation's claim for the deduction, attached to its return together with the Forms 972.
The instructions say it can attach an unsigned Form 972 with the same information as the signed one, and keep the original signed Form 972 in its records.
The instructions say the corporation pays any withholding tax it would have withheld if the dividend had been actually paid, and point to Forms 1042, 1042-S and 1042-T.