Entity information
Name, employer identification number, address, and a box for the type of entity filing the claim: personal holding company, regulated investment company or real estate investment trust.
976
Claim for Deficiency Dividends Deductions by a Personal Holding Company, Regulated Investment Company, or Real Estate Investment Trust
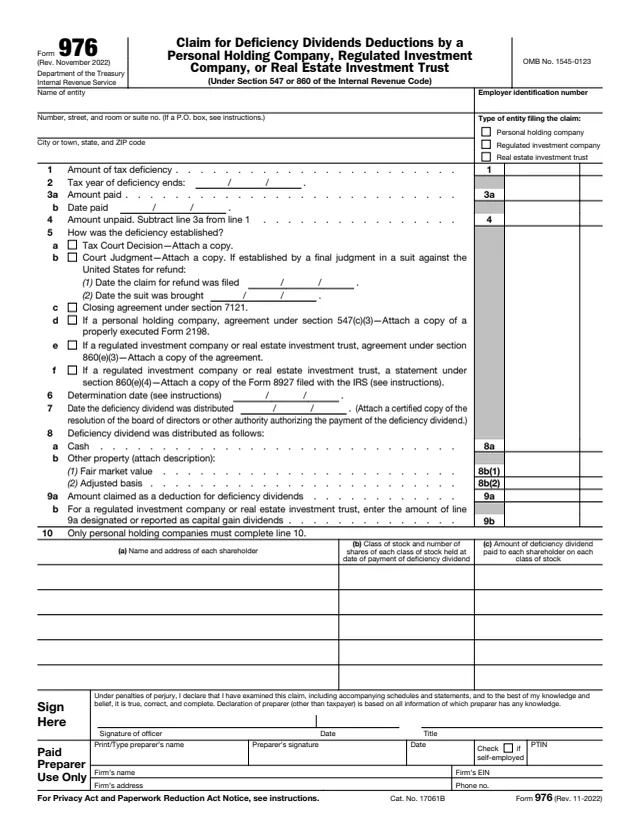
Form 976, Claim for Deficiency Dividends Deductions by a Personal Holding Company, Regulated Investment Company, or Real Estate Investment Trust, is filed under section 547 or 860 of the Internal Revenue Code. The IRS About page says personal holding companies (PHC), regulated investment companies (RIC) and real estate investment trusts (REIT) file this form to claim a deficiency dividend deduction.
The instructions say that if the claim is allowed, taxpayers are relieved, in whole or in part, from the payment of certain taxes, or allowed a credit or refund of certain taxes. A RIC or REIT owes interest on the amount of the deduction allowed, and the IRS notifies it of that amount.
The form reports the tax deficiency, how and when it was established, when and how the deficiency dividend was paid, and the amount claimed. The instructions are printed on page 2. You can fill out Form 976 free in your browser on this page and download the result without an account.
Name, employer identification number, address, and a box for the type of entity filing the claim: personal holding company, regulated investment company or real estate investment trust.
The amount of tax deficiency, the end of the tax year of the deficiency, the amount and date paid, and the amount unpaid.
Six boxes: Tax Court decision, court judgment, closing agreement under section 7121, a section 547(c)(3) agreement, a section 860(e)(3) agreement, or a section 860(e)(4) statement.
The determination date, the date the deficiency dividend was distributed, and whether it was paid in cash or other property, with fair market value and adjusted basis.
The amount claimed as a deduction, the part reported as capital gain dividends for a RIC or REIT, and the shareholder table for personal holding companies.
The officer's signature, date and title under penalties of perjury, and the Paid Preparer Use Only section.
Enter the tax liability established by the determination, without the deficiency dividend deduction. The instructions say to attach a detailed statement showing the computation and explaining each change to the original or amended Form 1120-REIT, Form 1120-RIC or Schedule PH (Form 1120).
Enter the ending date of the tax year for which the deduction is claimed. The instructions say a separate Form 976 is filed for each deficiency dividend deduction claimed. Enter any amount already paid on line 3a.
Check how the deficiency was established and attach the copy the form asks for: the Tax Court decision, the court judgment, Form 2198, the agreement, or the Form 8927 filed with the IRS.
Enter the determination date. The instructions define it by source: the date a Tax Court decision or court judgment becomes final, the date a closing agreement is approved, the registration or postmark date for a mailed agreement, or the date Form 8927 was mailed.
Enter the date the deficiency dividend was distributed and attach a certified copy of the board resolution or other authority for the payment. For other property, attach a description and enter its fair market value and adjusted basis.
Enter the amount claimed on line 9a, and for a RIC or REIT the capital gain dividend part on line 9b. A personal holding company lists each shareholder on line 10. An authorized officer signs and dates the form.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 976 within 120 days after the determination date.
A personal holding company files with the IRS office where the determination of PHC status was made.
A RIC or REIT files with the Internal Revenue Service Center where its income tax return for the year of the determination was filed, unless one of the special cases applies.
For a determination made by a RIC or REIT under section 860(e)(4), the instructions give Internal Revenue Service, P.O. Box 9941, Mail Stop 4912, Ogden, UT 84409, the same address used for Form 8927.
The instructions say deficiency dividends are distributed no later than 90 days after the determination date and before Form 976 is filed.
If allowing the deduction results in an overpayment of tax, the instructions say an amended income tax return is filed in addition to Form 976 to obtain a credit or refund.
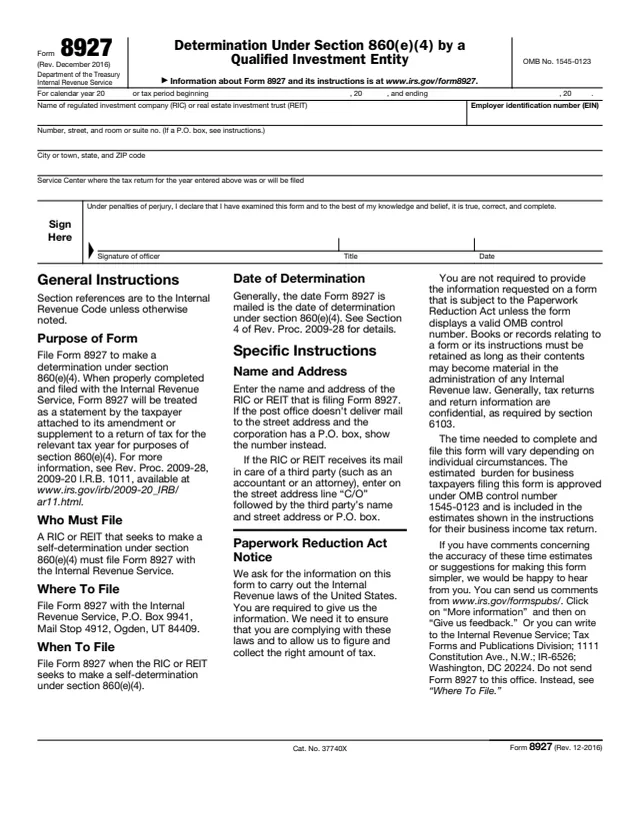
8927
12 fields, 1 page
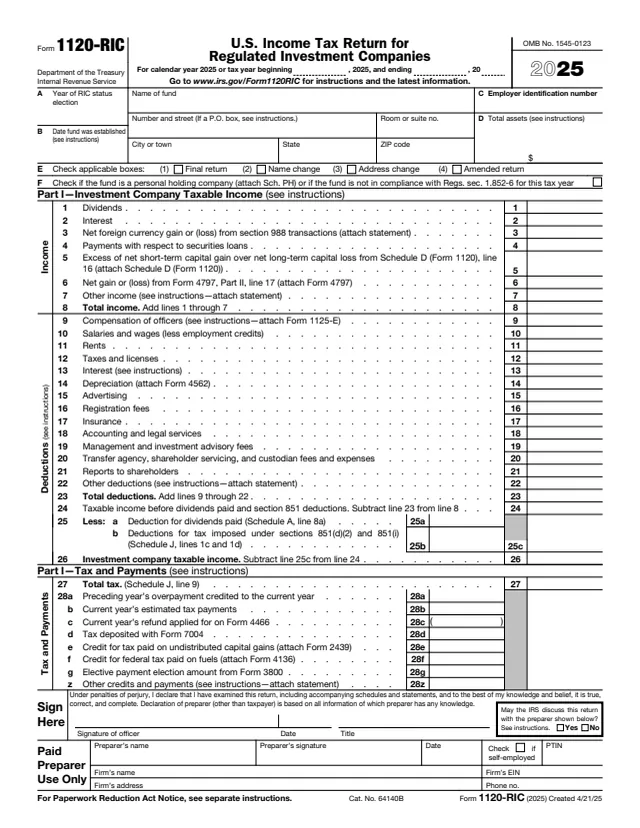
1120-RIC
325 fields, 4 pages
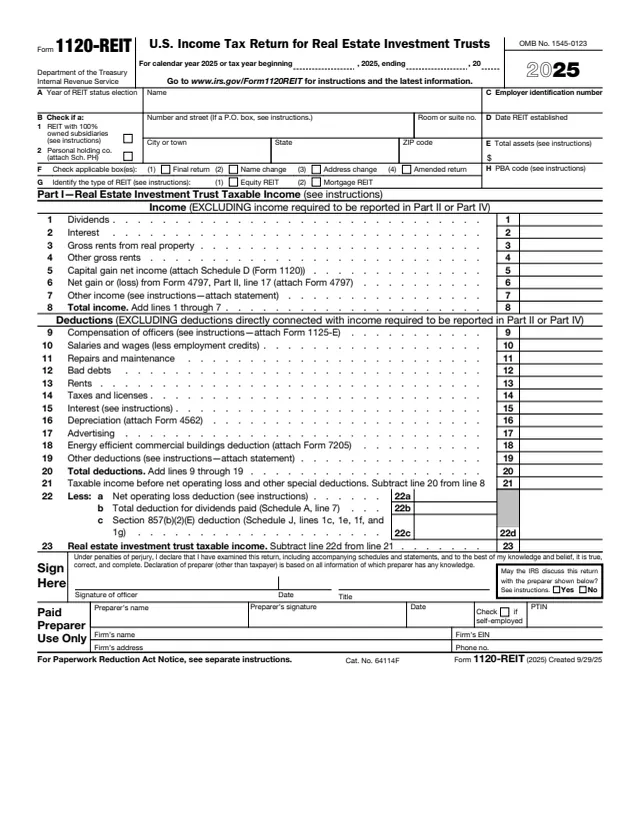
1120-REIT
346 fields, 5 pages
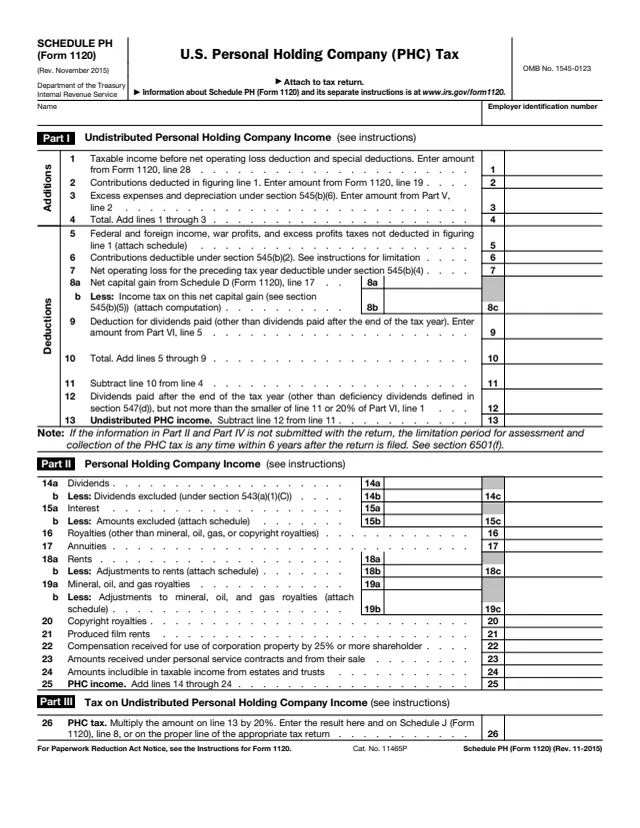
1120
114 fields, 2 pages
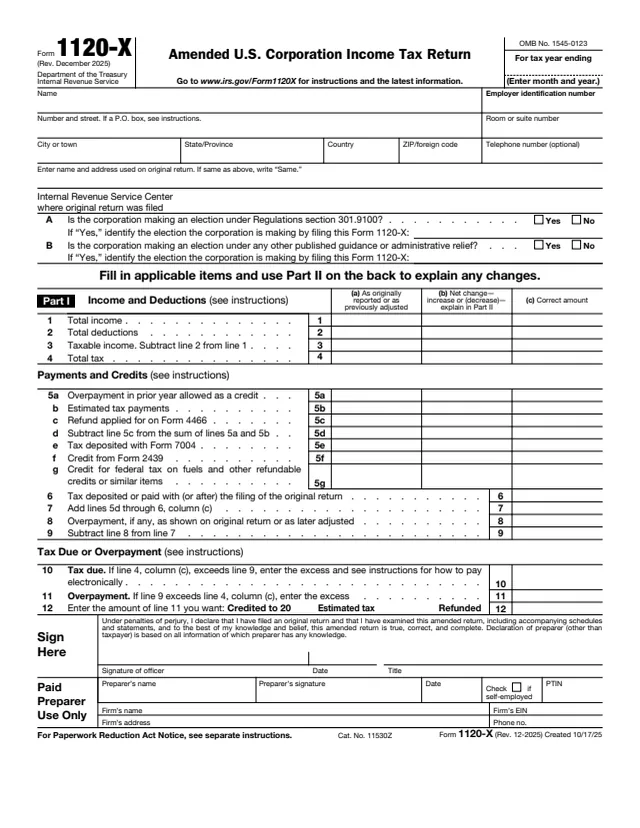
1120-X
70 fields, 2 pages
The form is filed by the company or trust claiming the deduction and signed by one of its officers. It is not an individual's form.
No tool matches that search.
A personal holding company, regulated investment company or real estate investment trust claiming a deficiency dividend deduction under section 547 or 860.
The instructions say within 120 days after the determination date.
No later than 90 days after the determination date and before Form 976 is filed, according to the instructions.
Yes. The instructions say a RIC or REIT owes interest on the amount of the deficiency dividend deduction allowed, and the IRS notifies it of the amount.
No. The instructions say a separate Form 976 is filed for each deficiency dividend deduction claimed.
The instructions describe Form 2198 as the agreement required by section 547(c)(3), jointly signed by a delegate of the Commissioner and a qualified officer of the PHC to establish its tax liability.