Part I: Undistributed PHC Income, lines 1 to 13
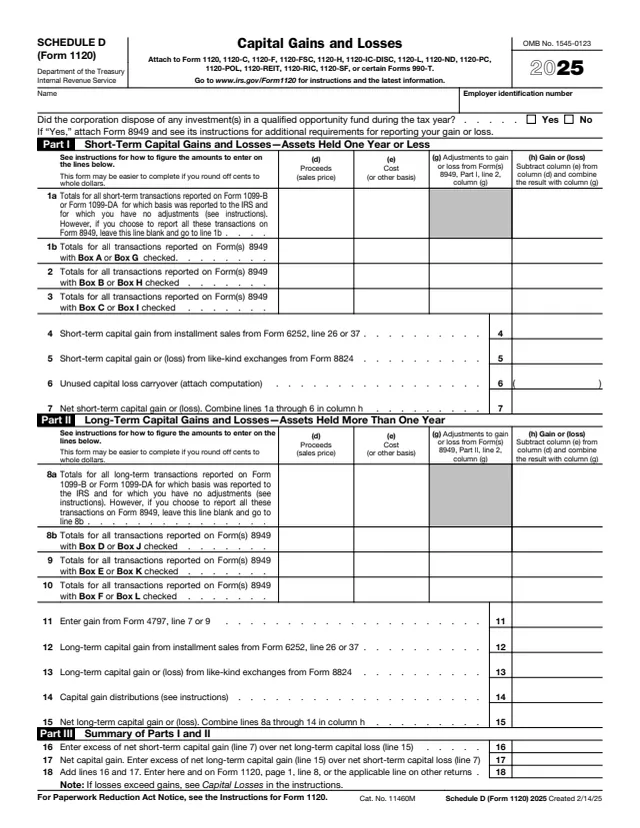
Starts from taxable income on Form 1120, line 28, adds back contributions and excess expenses, then subtracts taxes, contributions, a net operating loss, net capital gain and dividends paid.
1120
U.S. Personal Holding Company (PHC) Tax
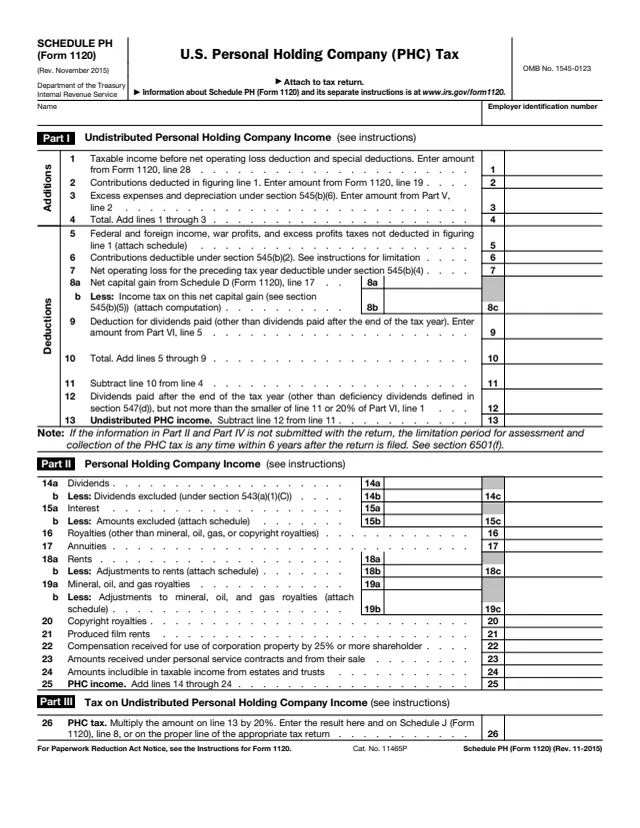
Schedule PH (Form 1120) is used to figure the U.S. personal holding company (PHC) tax. The About page says a corporation that is a personal holding company uses it to figure the PHC tax, and the form says "Attach to tax return."
The instructions say a corporation is generally a PHC if it meets two tests: at least 60% of its adjusted ordinary gross income for the tax year is PHC income, and at any time during the last half of the tax year more than 50% in value of its outstanding stock is directly or indirectly owned by five or fewer individuals. Tax-exempt corporations, banks, life insurance and surety companies, foreign corporations and some others are not PHCs.
The instructions give a tax rate of 20% on undistributed PHC income. This page has the November 2015 revision. You can fill out the PDF free in your browser on this page and download it without an account.
Starts from taxable income on Form 1120, line 28, adds back contributions and excess expenses, then subtracts taxes, contributions, a net operating loss, net capital gain and dividends paid.
Dividends, interest, royalties, annuities, rents, mineral, oil and gas royalties, copyright royalties, produced film rents, compensation from a 25% or more shareholder, personal service contracts and estate or trust income.
The PHC tax, which the form figures as 20% of the undistributed PHC income on line 13.
Names and addresses of the individuals who together owned more than 50% in value of the stock during the last half of the tax year, with their highest percentage of preferred and common shares.
A property-by-property table of cost, depreciation, repairs and other expenses against rent or other compensation. The total excess goes to Part I, line 3.
Taxable dividends paid, consent dividends with Forms 972 and 973 attached, and the dividend carryover. The total goes to Part I, line 9.
The instructions say to complete Part I, then lines 1 to 5 of the Worksheet, then Part II and line 6 of the Worksheet. Line 6 divides Part II, line 25, by adjusted ordinary gross income.
Enter the amount from Form 1120, line 28, on line 1 and contributions from Form 1120, line 19, on line 2. Attach a schedule of the taxes on line 5. Line 12 holds dividends paid after year end that the corporation elects to treat as paid during the year.
Enter each type of PHC income. The instructions explain when rents, mineral, oil and gas royalties, copyright royalties, software royalties and produced film rents can be excluded.
List the shareholders for the stock ownership test, the excess of expenses over rent for each property, and the dividends paid deduction. Attach Forms 972 and 973 for consent dividends.
Multiply line 13 by 20% and enter the result on line 26 and on Schedule J (Form 1120), line 8, or on the proper line of the appropriate tax return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to tax return." The instructions say a corporation that is a PHC files Schedule PH by attaching it to its income tax return.
The form notes that if Part II and Part IV are not submitted with the return, the limitation period for assessment and collection of the PHC tax is any time within 6 years after the return is filed.
For tax years beginning after December 31, 2015, the instructions say a corporation can elect to treat dividends paid before the 16th day of the 4th month after year end as paid during its tax year. Special rules apply to years ending in June.
The instructions say the foreign tax credit is not allowed against PHC tax, but taxes paid to foreign countries and U.S. possessions can be deducted on line 5.

1120
481 fields, 6 pages
972
56 fields, 2 pages
973
74 fields, 2 pages
1120
48 fields, 1 page
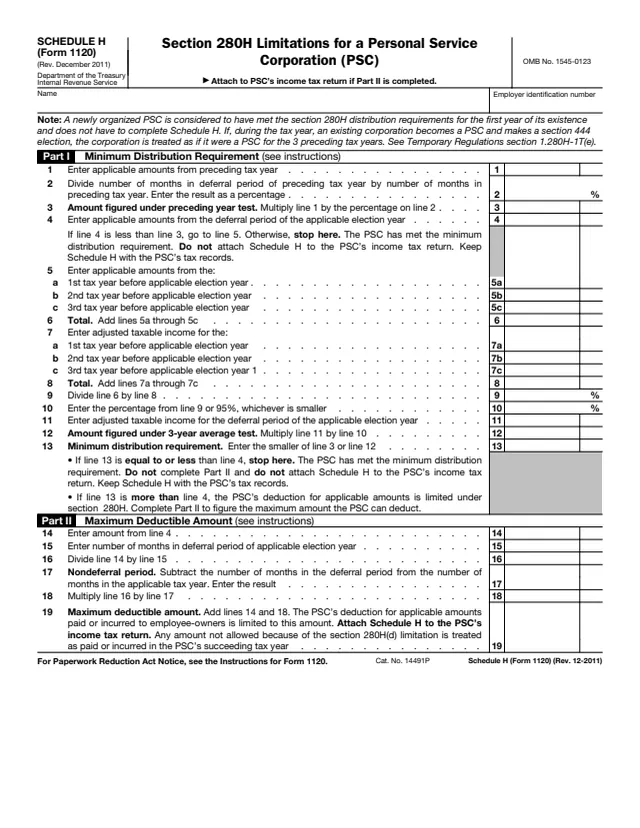
1120
45 fields, 2 pages
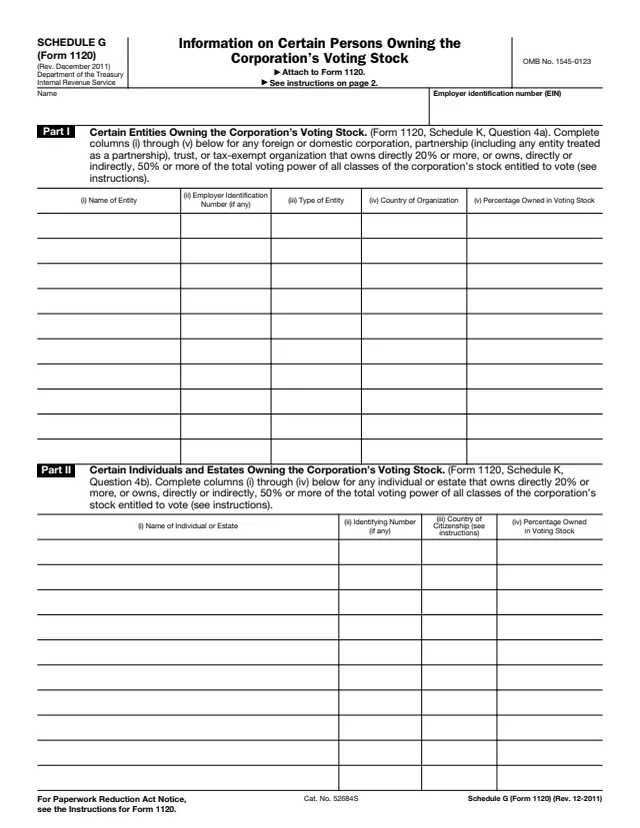
1120 Sch. G
92 fields, 2 pages
The instructions say a corporation that is a PHC files Schedule PH by attaching it to its income tax return. It is a corporate schedule, not a form for individuals.
No tool matches that search.
The instructions say the tax rate on undistributed personal holding company income is 20%. Line 26 multiplies Part I, line 13, by 20%.
The Worksheet in the instructions says that if line 6 is less than 60%, the corporation is not a PHC and does not file Schedule PH.
The instructions list tax-exempt corporations, banks and certain lending or finance companies, life insurance and surety companies, certain small business investment companies, corporations in a title 11 or similar case, and foreign corporations.
The instructions list a qualified pension, profit-sharing or stock bonus plan under section 401(a), a section 501(c)(17) trust, a private foundation under section 509(a), and part of a trust set aside for the purpose in section 642(c).
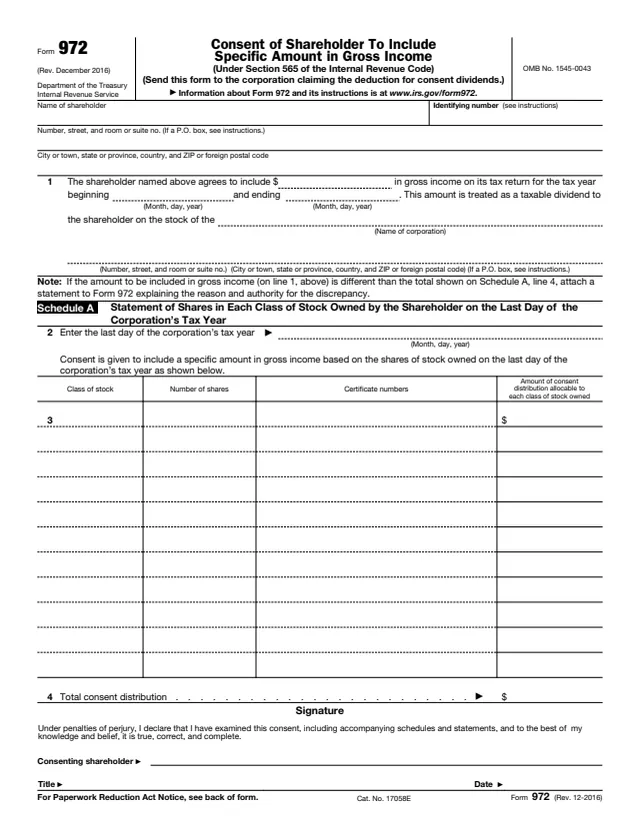
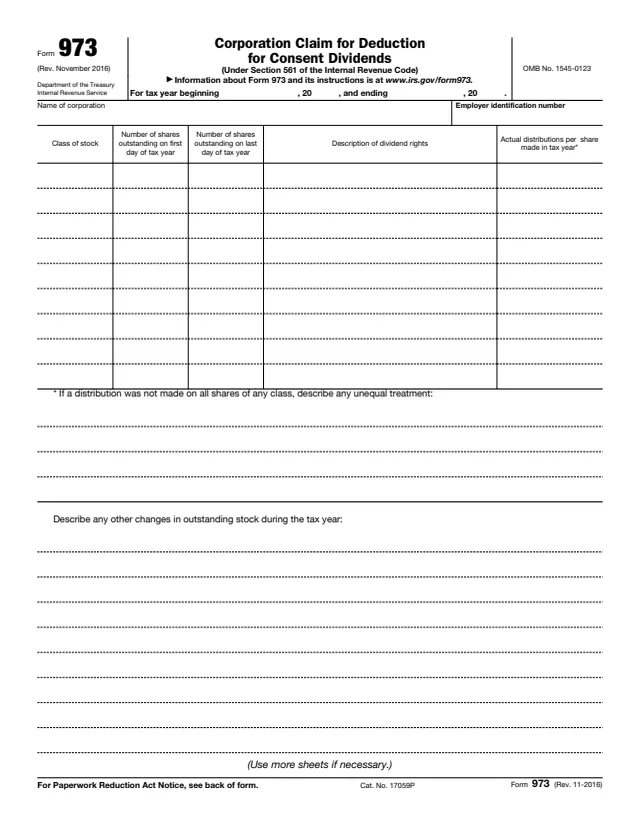
Part VI, line 2 lists consent dividends and says to attach Forms 972 and 973. Form 972 is the shareholder's consent to include a specific amount in gross income, and Form 973 is the corporation's claim for the deduction.
The PDF prints Rev. November 2015. The separate instructions on irs.gov are marked Revised 12/2016.