Shareholder name, number and address
The name of the shareholder, an identifying number, and the street address, city or town, state or province, country and ZIP or foreign postal code.
972
Consent of Shareholder To Include Specific Amount in Gross Income
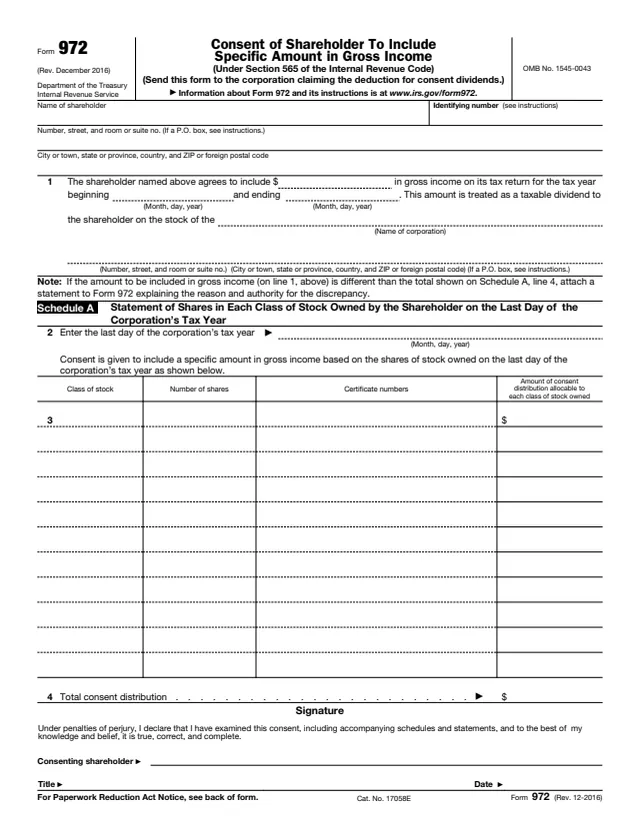
Form 972 is the consent a shareholder gives under section 565 of the Internal Revenue Code to include a specific amount in gross income as a dividend. The instructions say the shareholder reports the consent dividend as taxable income on its own return even though it receives no actual cash distribution of the consented amount. When the shareholder agrees, the corporation may be able to claim a consent dividend deduction, and the shareholder increases its basis in the corporation's stock by the amount it is taxed on.
The IRS describes it this way: a shareholder who agrees to report a consent dividend as taxable income on their own tax return completes the form and sends it to the corporation that will claim the consent dividend as a deduction. The form says to send it to the corporation claiming the deduction for consent dividends. The corporation attaches Form 973 and a copy of each completed Form 972 to its income tax return.
This page has the December 2016 revision. You can fill out the PDF free in your browser on this page and download the result without an account.
The name of the shareholder, an identifying number, and the street address, city or town, state or province, country and ZIP or foreign postal code.
The dollar amount the shareholder agrees to include in gross income, its tax year beginning and ending dates, and the name and address of the corporation.
The last day of the corporation's tax year. The consent is based on the shares of stock owned on that day.
A table with the class of stock, number of shares, certificate numbers and the amount of consent distribution allocable to each class of stock owned.
The total consent distribution. A note on the form asks for an attached statement if the line 1 amount differs from this total.
A declaration under penalties of perjury, with the consenting shareholder's signature, title and date.
Enter the shareholder's name and address. The instructions say to include the room, suite or other unit number, and to show a P.O. box only if the Post Office does not deliver mail to the street address.
Individuals enter their social security number. The instructions say all others enter their employer identification number.
Enter the amount to include in gross income, the shareholder's tax year beginning and ending dates, and the name and address of the corporation.
Enter the last day of the corporation's tax year on line 2, list each class of stock owned on that day on line 3, and enter the total on line 4.
If the amount on line 1 is different from the total on Schedule A, line 4, the form says to attach a statement explaining the reason and authority for the discrepancy.
The signer named in the instructions signs with a title and date. The form then goes to the corporation claiming the deduction.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Send the completed form to the corporation that will claim the consent dividend deduction. The form says to send it to the corporation, and it has no IRS mailing address.
The instructions say to send it to the corporation by the due date of the corporation's tax return for the tax year it will claim the consent dividends as a deduction.
The instructions say the shareholder reports the consent dividend as a taxable dividend in the same tax year the corporation will claim the deduction, and give a fiscal year example.
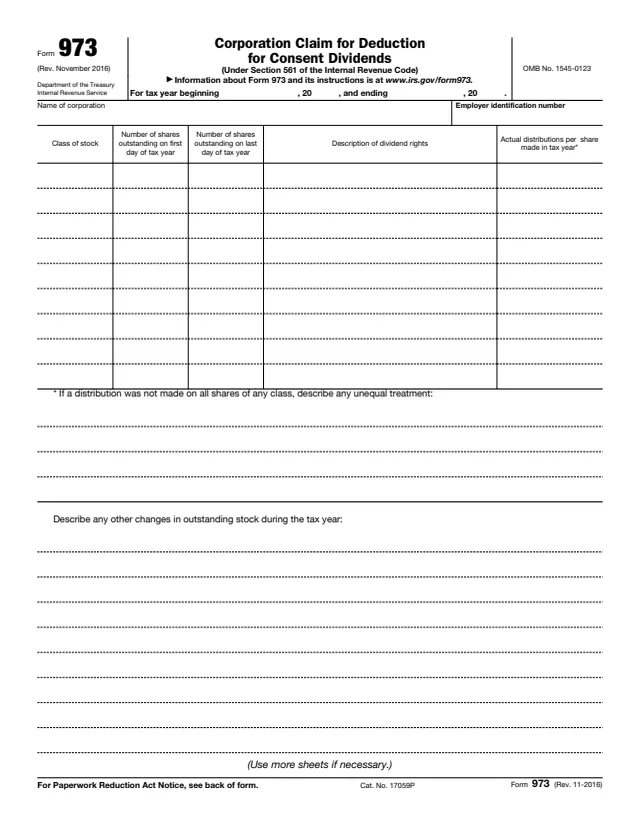
The corporation attaches Form 973, Corporation Claim for Deduction for Consent Dividends, and a copy of each completed Form 972 to its income tax return.
If an attorney or agent signs, the power of attorney accompanies Form 972 unless it was filed before.
The shareholder completes and signs Form 972 and sends it to the corporation. The instructions name who signs for each kind of shareholder.
No tool matches that search.
The form says to send it to the corporation claiming the deduction for consent dividends. The corporation attaches a copy to its income tax return along with Form 973.
The instructions describe a consent dividend as an amount the shareholder reports as taxable income even though it receives no actual cash distribution of the consented amount.
The instructions say the shareholder increases its basis in the corporation's stock by the amount of the consent dividend for which it is taxed.
The president, vice president, treasurer, assistant treasurer, chief accounting officer or another authorized officer, such as a tax officer.
The instructions say by the due date of the corporation's tax return for the tax year in which the corporation will claim the consent dividends as a deduction.
The form says to attach a statement to Form 972 explaining the reason and authority for the discrepancy.