Header
Amended return box, withholding agent's name, EIN, chapter 3 and chapter 4 status codes, address, and a box with the date final income was paid if no future returns are expected.
1042
Annual Withholding Tax Return for U.S. Source Income of Foreign Persons
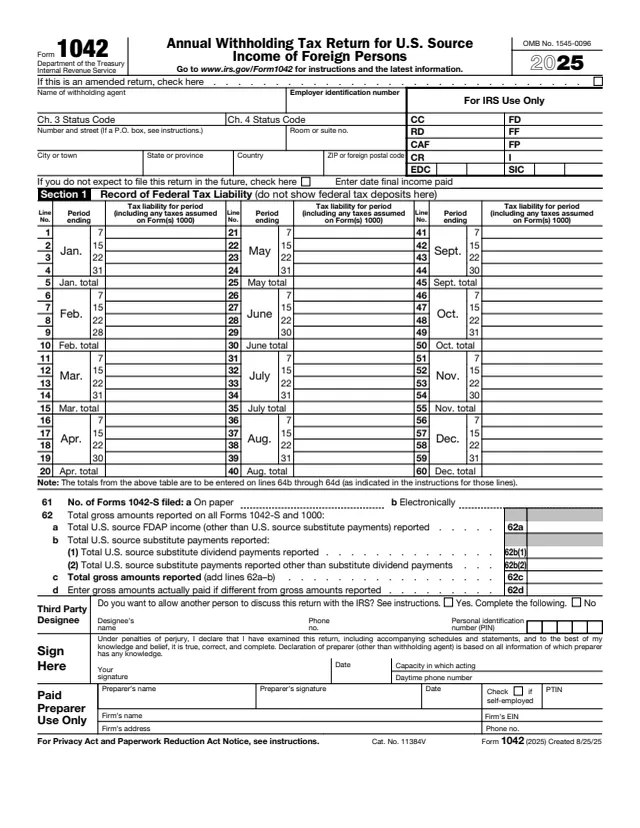
Form 1042 is the Annual Withholding Tax Return for U.S. Source Income of Foreign Persons. The IRS About Form 1042 page says it reports tax withheld under chapter 3 on certain income of foreign persons, tax withheld under chapter 4 on withholdable payments, tax withheld under section 5000C on specified federal procurement payments, and payments reported on Form 1042-S under chapters 3 or 4.
The instructions say every withholding agent or intermediary who receives, controls, has custody of, disposes of, or pays a withholdable payment or an amount subject to withholding files an annual return for the preceding calendar year on Form 1042, unless an exception applies. The form records tax liability by quarter-monthly period, totals the Forms 1042-S, figures the balance due or overpayment, and reconciles U.S. source FDAP income under chapter 4.
This page has the 2025 form. You can fill out Form 1042 free in your browser on this page and download it without an account.
Amended return box, withholding agent's name, EIN, chapter 3 and chapter 4 status codes, address, and a box with the date final income was paid if no future returns are expected.
Lines 1 to 60 record tax liability for each period ending on the 7th, 15th, 22nd and last day of each month, with a total for every month. The form says not to show deposits here.
The number of Forms 1042-S filed on paper and electronically, total gross amounts reported on Forms 1042-S and 1000, and total tax reported as withheld or paid.
Net tax liability under chapters 3 and 4 and on federal procurement payments, deposits, credits, balance due, overpayment and a choice of credit or refund with direct deposit lines.
Lines 1 to 6 reconcile U.S. source FDAP income withheld upon and reportable under chapter 4 with the amounts on all Forms 1042-S, and explain any variance.
Check boxes for payments under a potential section 871(m) transaction and for payments made by a qualified derivatives dealer, with an EIN field for the QDD box.
Enter the EIN, or the QI-EIN, WP-EIN or WT-EIN when filing in that capacity. The instructions say to enter both chapter 3 and chapter 4 status codes from the Form 1042-S code list, whatever payments are reported.
Enter the tax liability for the period in which income was paid, not the tax deposited, and no negative amounts. The instructions say the monthly totals carry to lines 64b through 64d.
Enter the number of Forms 1042-S and the amounts reported on all Forms 1042-S and Forms 1000. The instructions say to reconcile these with the Forms 1042-S to avoid unnecessary correspondence with the IRS.
Split the liability between chapter 3 on line 64b and chapter 4 on line 64c, enter section 5000C tax on line 64d, then deposits and credits. The instructions say not to include interest or penalties on line 69.
The instructions say Section 2 is completed even if no amounts were withheld under chapter 4. If line 5 is not zero, line 6 explains the variance, with an attached sheet if needed.
Check the boxes that apply. If a QI was a QDD, the instructions say to attach Schedule Q (Form 1042) for each QDD. Then sign, and complete the designee and paid preparer areas if used.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to mail Form 1042 by the 15th day of the 3rd month after the end of the calendar year (March 15) to Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409.
The instructions say e-filing is required for a withholding agent that is a financial institution, one required to file 10 or more information returns, or a partnership with more than 100 partners.
The instructions say Form 7004 may be submitted for more time to file, and that Form 7004 does not extend the time for payment of tax.
The instructions say tax withheld is deposited using EFTPS or IRS Direct Pay, and warn not to mail deposits directly to the IRS to avoid a penalty.
The instructions give 5% of the unpaid tax for each month the return is late, up to 25%, and usually one-half of 1% per month for late payment, also capped at 25%.
The instructions give 267-941-1000 (not a toll-free number) from 6:00 a.m. to 11:00 p.m. Eastern time for help completing Form 1042.
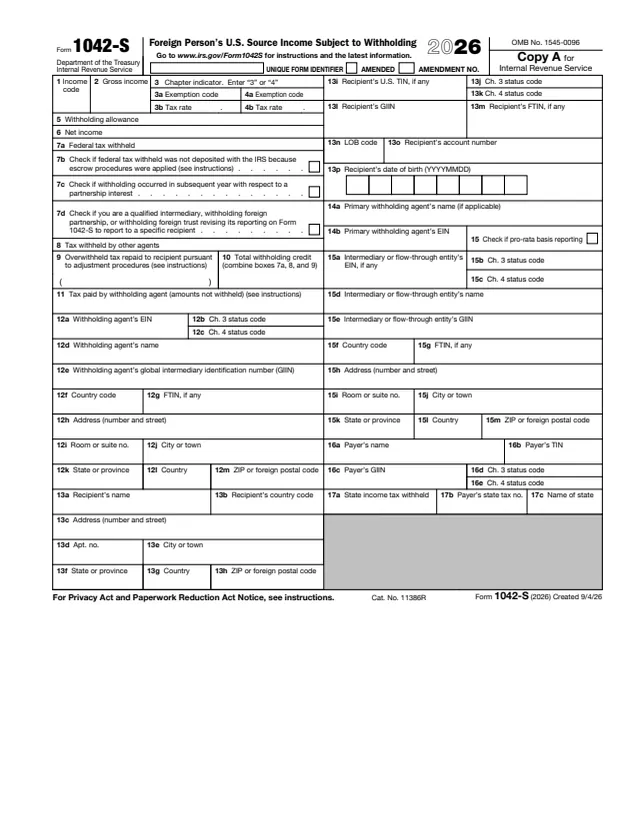
1042-S
300 fields, 7 pages
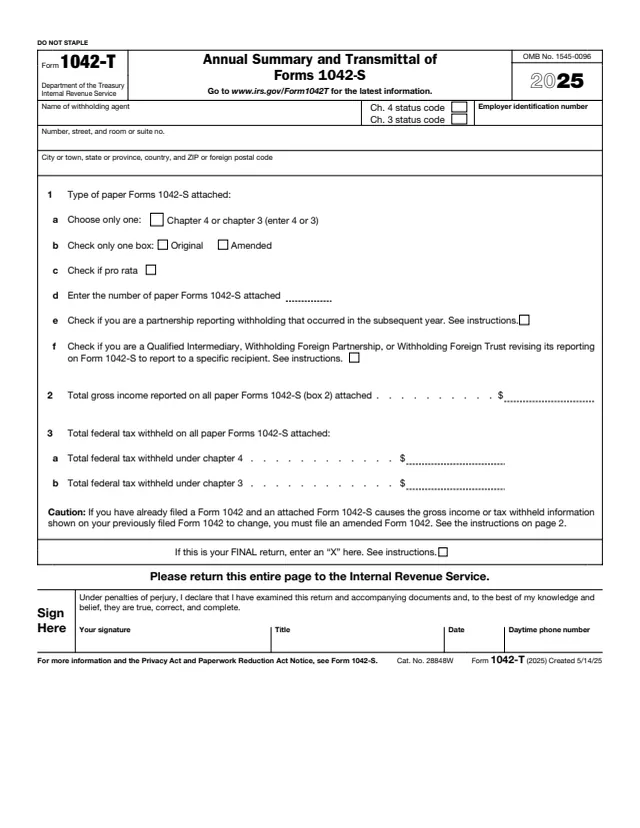
1042-T
19 fields, 2 pages
1042
45 fields, 1 page
1000
14 fields, 2 pages

7004
26 fields, 1 page
945
88 fields, 3 pages
Form 1042 is filed with the IRS by withholding agents and intermediaries, not by the foreign persons who received the income. Recipients get Form 1042-S instead.
No tool matches that search.
The instructions say Form 1042 is used to report the amount of withholding that is paid over, and Form 1042-S is used to report the amount of income and withholding to the payee.
No. It is filed by the withholding agent or intermediary. Recipients receive Form 1042-S showing their income and the tax withheld.
The instructions say by the 15th day of the 3rd month after the end of the calendar year (March 15), or the next business day if that date falls on a Saturday, Sunday or legal holiday.
The instructions say to file only one Form 1042 consolidating all Form 1042-S information, except a separate Form 1042 for each capacity in which the filer acts, such as QI and NQI.
Liability. The form says not to show federal tax deposits in Section 1, and the instructions say to report the tax liability for each period rather than the tax deposited.
The instructions say to use a Form 1042 for the year being amended, check the Amended Return box, complete the entire form, sign it and attach a statement explaining why.
The instructions say a withholding agent or intermediary may designate a partner, a member, an owner, any corporate office authorized to sign, or a fiduciary to sign Form 1042.