Owner of bonds
The owner's name, U.S. identifying number and address, including city or town, state or province, country and ZIP or foreign postal code.
1000
Ownership Certificate
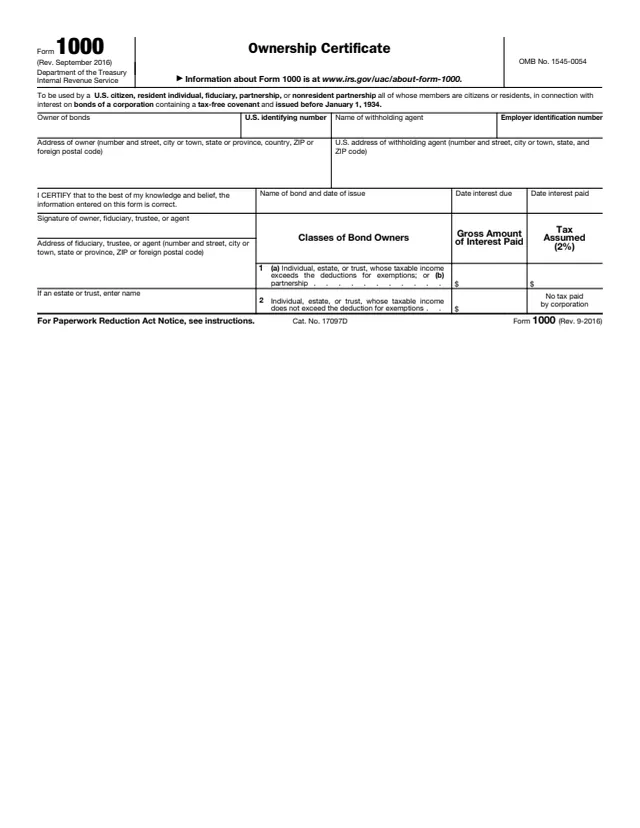
Form 1000 is the IRS Ownership Certificate. The form says it is to be used by a U.S. citizen, resident individual, fiduciary, partnership, or nonresident partnership all of whose members are citizens or residents, in connection with interest on bonds of a corporation containing a tax-free covenant and issued before January 1, 1934.
The certificate goes to the withholding agent, not to the IRS. It lists the owner of the bonds, the withholding agent, the bond issue, the interest dates and the gross amount of interest paid, sorted into two classes of bond owners. Page 2 of the form holds short instructions for the owner, fiduciary, trustee, or agent and for withholding agents.
You can fill out Form 1000 free in your browser on this page and download it without an account.
The owner's name, U.S. identifying number and address, including city or town, state or province, country and ZIP or foreign postal code.
The name, employer identification number and U.S. address of the withholding agent.
A statement that, to the best of the signer's knowledge and belief, the information is correct. Then the signature of the owner, fiduciary, trustee, or agent, that signer's address, and the name of an estate or trust if one applies.
The name of the bond and date of issue, the date interest is due and the date interest is paid.
Line 1 is for (a) an individual, estate, or trust whose taxable income exceeds the deductions for exemptions, or (b) a partnership, with columns for the gross amount of interest paid and the tax assumed (2%). Line 2 is for an individual, estate, or trust whose taxable income does not exceed the deduction for exemptions, marked no tax paid by corporation.
The instructions say to use a separate Form 1000 for each issue of bonds.
Enter the owner's name, U.S. identifying number and full address.
Enter the withholding agent's name, employer identification number and U.S. address.
Enter the name of the bond and its date of issue, the date interest was due and the date it was paid.
Enter the gross amount of interest paid on line 1 or line 2, whichever class of bond owner the form describes for the owner. Line 1 also has a column for the tax assumed at 2%.
The owner, fiduciary, trustee, or agent signs the certification. A fiduciary, trustee, or agent adds their address, and an estate or trust enters its name.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file the form with the withholding agent for interest payments on bonds that have a tax-free covenant and that were issued before 1934.
The instructions for withholding agents say "Do not send Form 1000 to the IRS" and to use Form 1042 to summarize Forms 1000.
If amended certificates are necessary, the instructions say to forward them to the withholding agent by February 1 of the following year.
The withholding agent keeps Form 1000 for at least 4 years after the end of the last calendar year in which the income the form applies to is paid.
If a nonresident foreign corporation with a fiscal or paying agent in the United States issues the obligation, the instructions say to modify the form to show the nonresident debtor corporation's name and address in addition to those of the U.S. fiscal or paying agent.
The form names who uses it and who receives it. The owner side completes and signs it, and the withholding agent keeps it.
No tool matches that search.
No. The instructions say to file it with the withholding agent, and the withholding agent instructions say "Do not send Form 1000 to the IRS."
The form says it is used in connection with interest on bonds of a corporation containing a tax-free covenant and issued before January 1, 1934.
The owner, fiduciary, trustee, or agent, certifying that to the best of their knowledge and belief the information on the form is correct.
No. The instructions say to use a separate Form 1000 for each issue of bonds.
The instructions say the withholding agent uses Form 1042 to summarize Forms 1000 and keeps each one for at least 4 years after the end of the last calendar year in which the income it applies to is paid.
The instructions are printed on page 2 of the form itself, one part for the owner, fiduciary, trustee, or agent and one part for withholding agents.