Receiving corporation
Name, employer identification number, street address with room or suite number, and city or town, state and ZIP code.
952
Consent To Extend the Time To Assess Tax Under Section 332(b)
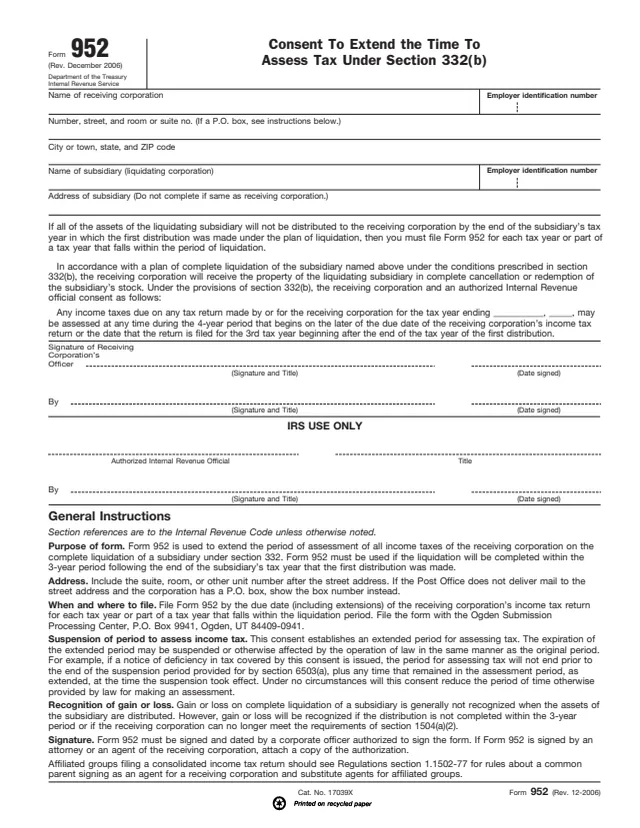
Form 952, Consent To Extend the Time To Assess Tax Under Section 332(b), is used to extend the period of assessment of all income taxes of the receiving corporation on the complete liquidation of a subsidiary under section 332. The IRS says it is used if the liquidation will be completed within the 3-year period following the end of the subsidiary's tax year in which the first distribution was made.
Under the consent printed on the form, income taxes due on the receiving corporation's return for a named tax year may be assessed at any time during a 4-year period that begins on the later of the due date of that return or the date it is filed for the 3rd tax year beginning after the end of the tax year of the first distribution. The receiving corporation and an authorized Internal Revenue official both sign it.
This is the December 2006 revision, a one-page form with its instructions printed below the consent. You can fill out the PDF free in your browser on this page and download it without an account.
Name, employer identification number, street address with room or suite number, and city or town, state and ZIP code.
Name and employer identification number of the subsidiary (liquidating corporation), and its address only if it differs from the receiving corporation's.
The agreement under section 332(b), with a blank for the tax year ending date of the receiving corporation's return that the extended period covers.
Signature and title of the receiving corporation's officer, with the date signed.
Signature, title and date for the authorized Internal Revenue official.
Purpose of form, the address rule, when and where to file, suspension of the assessment period, recognition of gain or loss and signature rules.
Enter the receiving corporation's name, EIN and address. The instructions say to include the suite, room or other unit number, and to show a P.O. box only if the Post Office does not deliver mail to the street address.
Enter the liquidating subsidiary's name and EIN. The form says not to complete the subsidiary's address if it is the same as the receiving corporation's.
In the consent paragraph, enter the date the receiving corporation's tax year ends for the return this consent covers.
An authorized corporate officer signs with their title and the date signed. An attorney or agent who signs attaches a copy of the authorization, the instructions say.
The IRS Use Only section is for the authorized Internal Revenue official's signature, title and date.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 952 by the due date (including extensions) of the receiving corporation's income tax return for each tax year or part of a tax year that falls within the liquidation period.
The instructions say to file it with the Ogden Submission Processing Center, P.O. Box 9941, Ogden, UT 84409-0941.
The instructions say the extended period may be suspended or otherwise affected by operation of law in the same manner as the original period, and that the consent never reduces the period the law otherwise provides.
The instructions say gain or loss on complete liquidation of a subsidiary is generally not recognized, but is recognized if the distribution is not completed within the 3-year period or the receiving corporation can no longer meet section 1504(a)(2).

1120
481 fields, 6 pages
921
11 fields, 2 pages
8838
20 fields, 2 pages
8848
14 fields, 2 pages
872-B
15 fields, 2 pages
7204
18 fields, 1 page
Form 952 is a corporate form, not one an individual files. The receiving corporation completes and signs it, and an authorized Internal Revenue official signs the IRS Use Only section.
No tool matches that search.
The instructions say it extends the period of assessment of all income taxes of the receiving corporation on the complete liquidation of a subsidiary under section 332.
The consent says tax may be assessed during the 4-year period that begins on the later of the due date of the receiving corporation's return or the date it is filed for the 3rd tax year beginning after the end of the tax year of the first distribution.
The form says it is filed for each tax year or part of a tax year in the period of liquidation when all assets won't be distributed by the end of the subsidiary's tax year of the first distribution.
The instructions name the Ogden Submission Processing Center, P.O. Box 9941, Ogden, UT 84409-0941.
A corporate officer authorized to sign for the receiving corporation, and an authorized Internal Revenue official in the IRS Use Only section.
No. Its General Instructions are printed on the form itself, below the signature lines.