Header
EIN and name (not your trade name), one box for the return the credit goes on (Form 941, 943 or 944 series), the calendar year, and a quarter box for Form 941 filers.
8974
Quarterly Small Business Payroll Tax Credit for Increasing Research Activities
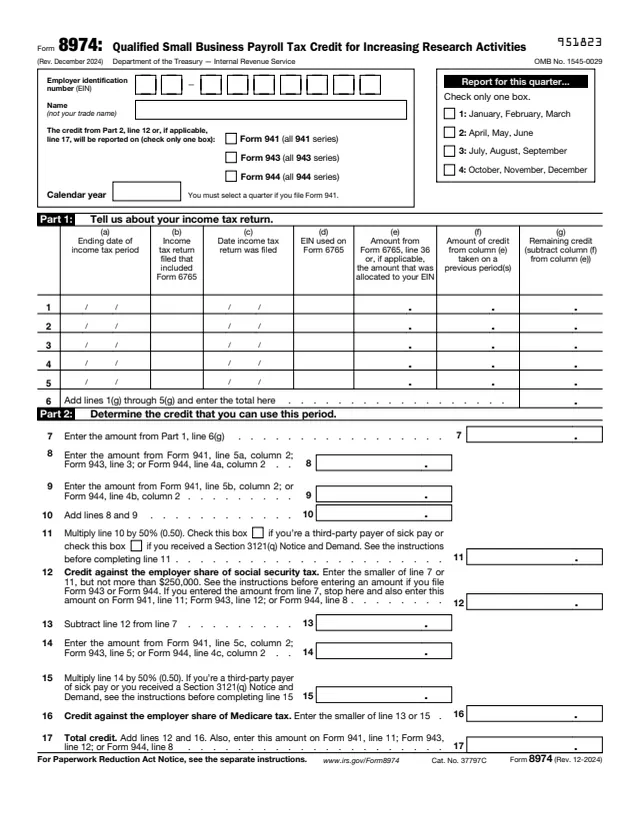
Form 8974, Qualified Small Business Payroll Tax Credit for Increasing Research Activities, is an employer form. The IRS About page says employers use it to determine the amount of the qualified small business payroll tax credit for increasing research activities they can claim on their employment tax return.
The credit starts on the income tax return. The instructions say the election is made on Form 6765, Credit for Increasing Research Activities, attached to an original income tax return that is timely filed (including extensions). Form 8974 then carries that elected amount over to Form 941, Form 943 or Form 944, the return it is attached to. It is not filed on its own.
The form has two parts: Part 1 lists up to five income tax years of elected credit, and Part 2 figures how much of it applies against the employer share of social security tax and then Medicare tax this period. You can fill out Form 8974 free in your browser on this page and download the result without an account.
EIN and name (not your trade name), one box for the return the credit goes on (Form 941, 943 or 944 series), the calendar year, and a quarter box for Form 941 filers.
One row per income tax year: (a) end of the tax period, (b) the return that included Form 6765, (c) the date it was filed, (d) the EIN on Form 6765, (e) the elected amount, (f) credit already taken and (g) the remaining credit.
The total of column (g) for lines 1 to 5, the credit available this period.
The social security portion: social security tax on wages and tips from the employment return, multiplied by 50%, and line 12, the credit against the employer share of social security tax, which the form caps at $250,000.
The Medicare portion: the credit left after line 12, Medicare tax on wages from the employment return multiplied by 50%, and line 16, the credit against the employer share of Medicare tax.
The total credit, lines 12 and 16 added together, which also goes on Form 941, line 11; Form 943, line 12; or Form 944, line 8.
Enter the EIN and name exactly as on the attached Form 941, 943 or 944, check one box for that return, enter the calendar year, and for Form 941 check the one quarter that matches it. On a Schedule R filing, each client's Form 8974 shows the client's EIN.
List each income tax year with an election, earliest on line 1. Enter dates as MM/DD/YYYY. Column (b) names the return Form 6765 was attached to: Form 1040, 1065, 1120, 1120-F or 1120-S. Column (d) is needed only when the EIN on Form 6765 differs.
Column (e) is generally Form 6765, line 36, or for controlled group members the amount allocated to your EIN. The instructions limit it to $250,000 for tax years beginning before January 1, 2023, and $500,000 after December 31, 2022. Subtract column (f) from (e) and total column (g) on line 6.
Copy line 6(g) to line 7 and the social security tax amounts from the employment return to lines 8 and 9. Form 941 filers multiply line 10 by 50%; Form 943 and 944 filers follow the line 11 adjustment in the instructions. Line 12 is the smaller of line 7 or 11, but not more than $250,000.
If line 12 came from line 7, stop there. Otherwise subtract line 12 from line 7, enter Medicare tax on wages on line 14, multiply it by 50% on line 15 (with the instructions' adjustments where they apply) and enter the smaller of line 13 or 15 on line 16.
Add lines 12 and 16 and carry the total to Form 941, line 11; Form 943, line 12; or Form 944, line 8. Attach Form 8974 to that return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Form 8974 is attached to the Form 941, 943 or 944 on which the credit is claimed. The instructions say the credit cannot be claimed on those returns unless the Form 6765 election is made and Form 8974 is attached.
The instructions say the credit is first claimed for the quarter that begins after the income tax return making the election is filed. Their example: a 2024 calendar year return filed March 17, 2025, means the second quarter 2025 Form 941, filed by July 31, 2025.
The instructions say that starting in the first quarter of 2023, the credit first reduces the employer share of social security tax up to $250,000 per quarter, then the employer share of Medicare tax. Any unused credit carries forward to the next quarter (Form 941) or year (Form 943 or 944).
The instructions say the payroll tax credit election on Form 6765 is limited to 5 tax years, which is why Part 1 has five rows. Each year stays on the form until its remaining credit in column (g) reaches zero.
Errors on a filed Form 8974 are corrected on Form 941-X, 943-X or 944-X, with a corrected Form 8974 attached to the amended return.
6765
270 fields, 4 pages
941
116 fields, 3 pages
943
109 fields, 3 pages
944
114 fields, 3 pages
941-X
352 fields, 6 pages
941 Sch. R
828 fields, 2 pages
The instructions say Form 8974 is filed and attached to Form 941, 943 or 944 by an employer that made the election on its income tax return to claim the credit against payroll taxes.
No tool matches that search.
No. The instructions say it is attached to Form 941, 943 or 944, the employment tax return on which the credit is claimed.
From the election on Form 6765, Credit for Increasing Research Activities, made on a timely filed original income tax return. Column (e) of Part 1 generally takes the amount from Form 6765, line 36.
The instructions say up to $250,000 for tax years beginning before January 1, 2023, and $500,000 for tax years beginning after December 31, 2022, under the Inflation Reduction Act of 2022.
The employer share of social security tax first, up to $250,000 per quarter, and then the employer share of Medicare tax. The instructions say this order applies starting in the first quarter of 2023.
The instructions say it carries forward to the next quarter for Form 941 filers, or to the next year for Form 943 and 944 filers.
By filing Form 941-X, 943-X or 944-X, as applicable, with a corrected Form 8974 attached.
No. The instructions say a third-party payer filing an aggregate Form 941 or 943 attaches a Form 8974 for each client taking the credit, and each one shows that client's EIN.