Items A and B
Item A asks whether you are electing the reduced credit under section 280C. Item B asks whether you are a member of a controlled group or business under common control.
6765
Credit for Increasing Research Activities
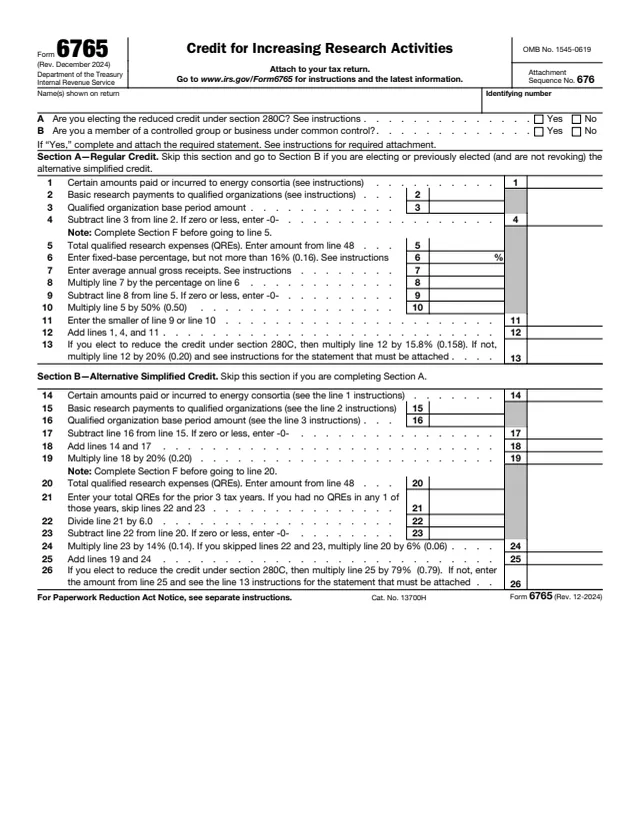
Form 6765, Credit for Increasing Research Activities, is the IRS form used to figure and claim the research credit. The IRS lists three uses: figure and claim the credit for increasing research activities, elect the reduced credit under section 280C, and elect and figure the payroll tax credit.
The instructions describe the credit as generally a percentage of qualified research expenses (QREs) over a base amount. QREs are the sum of in-house research expenses and contract research expenses paid or incurred in carrying on a trade or business. The form offers two ways to figure the credit: the regular credit in Section A or the alternative simplified credit (ASC) in Section B.
The form says "Attach to your tax return." A qualified small business can elect to apply part of the credit against the employer portion of social security tax, which it then claims with Form 8974. You can fill out Form 6765 free in your browser on this page and download the result without an account.
Item A asks whether you are electing the reduced credit under section 280C. Item B asks whether you are a member of a controlled group or business under common control.
Lines 1 to 13: energy consortia payments, basic research payments, a fixed-base percentage of not more than 16% (0.16), average annual gross receipts, and the credit at 20% (0.20) or 15.8% (0.158) with the section 280C election.
Lines 14 to 26 compare current QREs with the prior 3 tax years, multiply the excess by 14% (0.14), or current QREs by 6% (0.06) when lines 22 and 23 are skipped, and apply 79% (0.79) with the section 280C election.
Section C, lines 27 to 32, figures the current year credit and where it is reported. Section D, lines 33a to 36, is the qualified small business payroll tax election, capped on line 34 at $500,000.
Section E, lines 37 to 41, asks for the number of business components, officers' wages, acquisitions and the ASC 730 Directive. Section F, lines 42 to 48, sums wages, supplies, computer rental and contract research.
Pages 3 and 4 list each business component: EIN, activity code, name or identifier, type, software type, information sought, and wages, supplies, computer costs and contract research in columns 50 to 56.
The instructions say Item A is answered Yes or No on the original timely filed return, including extensions. The election cannot be made or changed on an amended return. If you answer Yes on Item B, attach the group credit statement the instructions describe.
The form says to complete Section F before line 5 or line 20. If Section G applies, complete it first and carry its column totals to lines 42 through 45. Line 48 then goes on line 5 or line 20.
Use Section A for the regular credit or Section B to elect the ASC. The instructions say an ASC election applies to the current tax year and all later years, and it can be revoked for a later year by completing Section A on that year's timely filed original return.
Line 30 shows where the credit goes. The form says partnerships and S corporations report on Schedule K, eligible small businesses report on Form 3800, Part III, line 4i, and other filers on Form 3800, Part III, line 1c. Estates and trusts continue to line 31.
Only for a qualified small business making the payroll tax election. Filers other than partnerships and S corporations complete Form 3800 first. Line 36 is entered on the applicable line of Form 8974, Part 1, column (e).
On line 37 enter the total number of business components behind the QREs. The instructions say Section G is optional for tax years beginning before 2026 and required for tax years beginning after 2025, with listed exceptions.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. Partnerships and S corporations report the credit on Schedule K, and other filers carry it to Form 3800.
The instructions say the election is made on or before the due date of the originally filed income tax return, including extensions, and cannot be made for a tax year if an election was made for 5 or more preceding tax years.
The payroll tax credit is claimed on the employment tax return for the first quarter that begins after the return reflecting the election is filed, with Form 8974 attached.
Section G is not required for a qualified small business claiming the payroll tax credit, or when group QREs are $1.5 million or less, average annual gross receipts are $50 million or less, and the credit is reported on an original return.
A research credit claimed on an amended return or an administrative adjustment request (AAR), or increased from the original return, needs the information for a valid research credit claim for refund. The e-file attachment name is Form6765ClaimInformation.pdf.

3800
1,921 fields, 9 pages
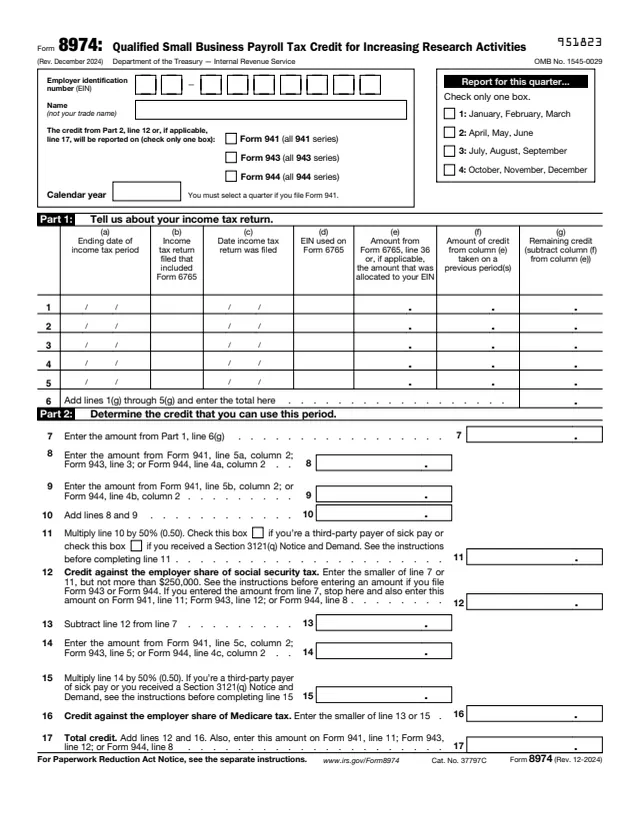
8974
107 fields, 1 page
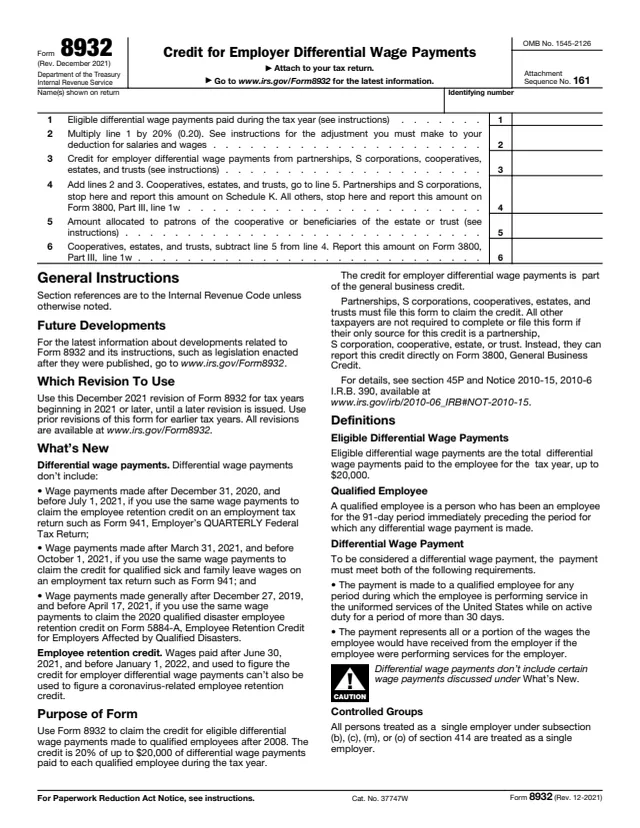
8932
8 fields, 2 pages
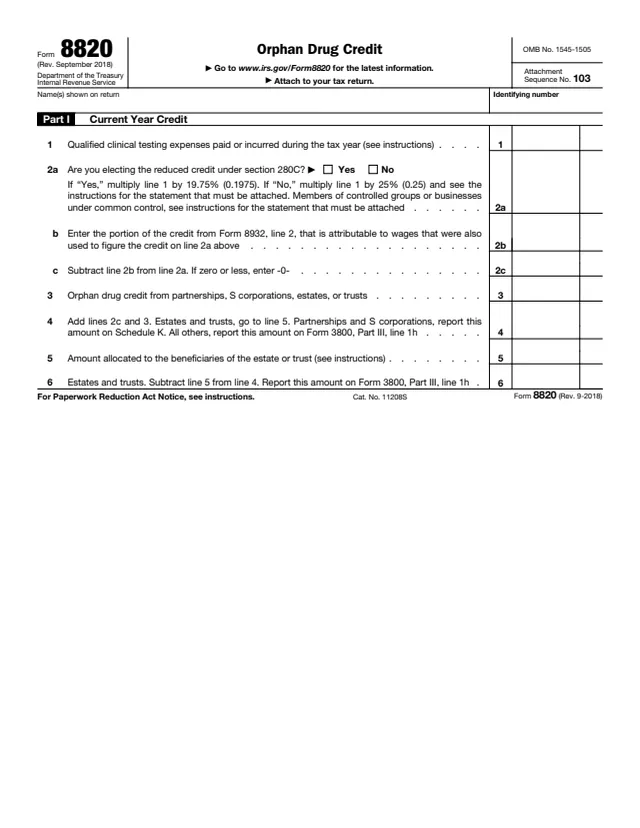
8820
98 fields, 4 pages

1065
111 fields, 1 page
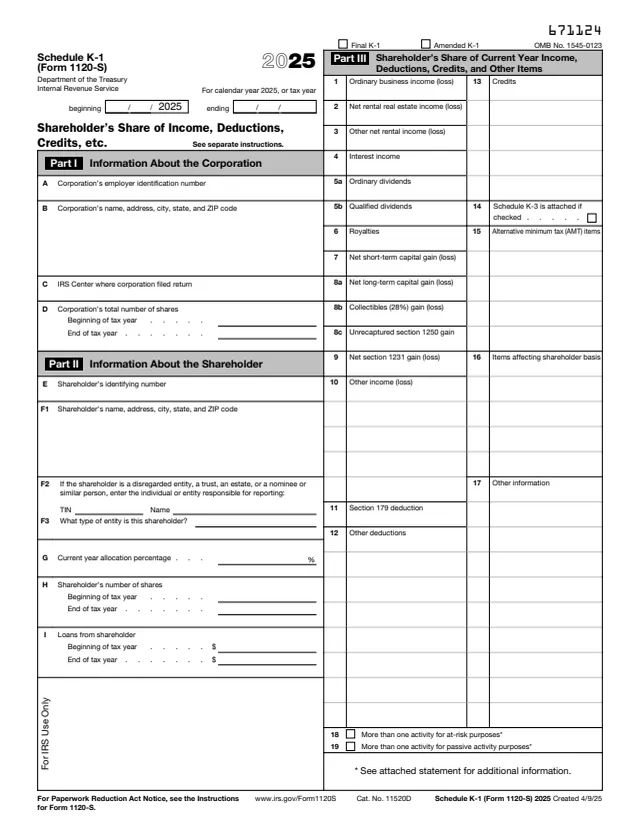
1120-S
114 fields, 1 page
Businesses that conduct qualified research complete Form 6765 with their income tax return. The instructions also say who can skip the form and report a passed-through credit directly on Form 3800.
No tool matches that search.
The instructions say partnerships and S corporations file it to claim the credit. Others whose only source of the credit is a partnership, S corporation, estate, or trust are generally not required to file it and can report the credit on Form 3800.
Section A figures the regular credit using a fixed-base percentage and gross receipts. Section B figures the alternative simplified credit using QREs from the prior 3 tax years.
It is the reduced credit election made on Item A. The instructions say it is made on the original timely filed return, cannot be made or changed on an amended return, and is irrevocable for that tax year once made.
The form says not more than $500,000 on line 34, for a qualified small business. The credit is applied against the employer portion of social security tax using Form 8974.
The instructions say it is optional for all filers for tax years beginning before 2026 and required for tax years beginning after 2025, unless one of the listed exceptions applies.
Yes, with the specific information the instructions require for a valid research credit claim for refund. An ASC election can be made on an amended return only if no research credit was claimed for that year before.