Line 1: qualified clinical testing expenses
The qualified clinical testing expenses paid or incurred during the tax year.
8820
Orphan Drug Credit
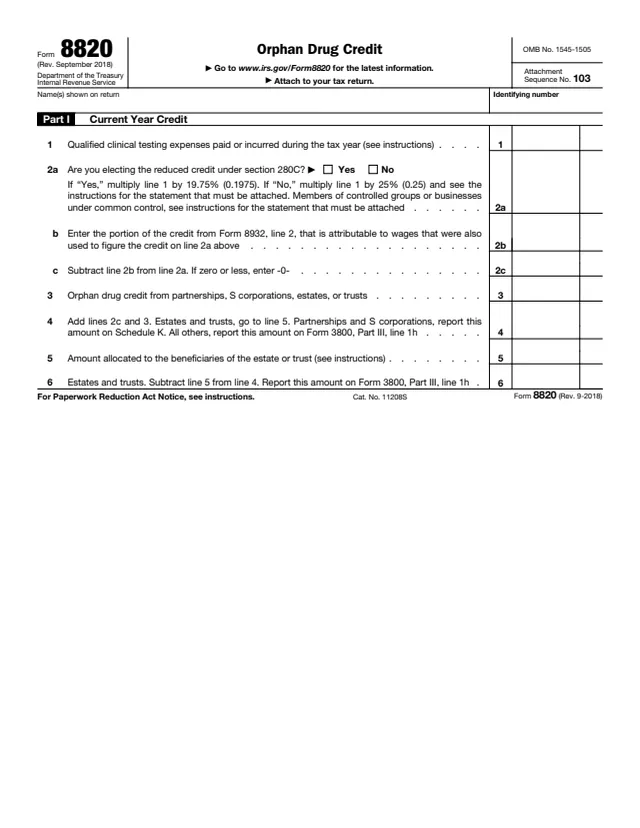
Form 8820 is the IRS form used to figure and claim the orphan drug credit and to elect the reduced credit under section 280C. The form says the credit is 25% of qualified clinical testing expenses paid or incurred during the tax year, and that for tax years beginning after 2017 the credit rate was reduced to 25% and an election for a reduced credit was added. The credit relates to human clinical testing of drugs for a rare disease or condition, as the instructions printed on the form define it.
The form is completed by the taxpayer claiming the credit and attached to its tax return. Partnerships and S corporations report the credit on Schedule K, estates and trusts allocate part of it to beneficiaries, and other filers carry it to Form 3800. The form says taxpayers that are not partnerships, S corporations, estates or trusts, and whose only source of this credit is those pass-through entities, are not required to complete or file it and can report the credit directly on Form 3800.
This page hosts the September 2018 revision, which carries its own instructions on pages 3 and 4. You can fill it out free in your browser on this page and download the result without an account.
The qualified clinical testing expenses paid or incurred during the tax year.
A Yes or No box for the reduced credit. Yes multiplies line 1 by 19.75% (0.1975); No multiplies it by 25% (0.25).
The part of the credit from Form 8932, line 2, that is attributable to wages also used for line 2a, subtracted to give line 2c.
Credit from partnerships, S corporations, estates or trusts, the total on line 4, and the amount allocated to beneficiaries of an estate or trust.
Rows 7a to 7z for the name of each orphan drug, its designation application number and the date the drug was designated (mm/dd/yyyy).
Enter the qualified clinical testing expenses. The instructions say to complete Part II for each orphan drug whose expenses are included on line 1.
Check Yes or No for the reduced credit. The instructions say the election applies only if Form 8820 is filed with the original timely filed return, including extensions, and that once made it is irrevocable for that tax year.
The instructions say to reduce the otherwise allowable deduction for qualified clinical testing expenses by the credit, and to attach a statement listing the reduced amounts and the lines where the reductions were made.
If line 2a includes wages paid to employees and the employer differential wage credit is also claimed on the same wages, enter that part of the credit, for example from line 2 of Form 8932.
Enter credit from partnerships, S corporations, estates or trusts on line 3 and add it on line 4. The instructions say an estate or trust under the passive activity rules uses Form 8582-CR to figure the allowed credit.
For each drug, enter the generic name, the designation application number and the date it was designated under section 526 of the Federal Food, Drug, and Cosmetic Act. Attach as many Part II pages as needed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the tax return. Partnerships and S corporations report line 4 on Schedule K. Other filers report the credit on Form 3800, Part III, line 1h.
To elect the reduced credit, the instructions say Form 8820 is completed even if no orphan drug credits are claimed on the original return, and filed with the original timely filed return, including extensions.
The instructions say the credit is not allowed for clinical testing outside the United States unless there is an insufficient U.S. testing population and the testing is done by a U.S. person or an unrelated person.
The instructions say expenses used for the orphan drug credit cannot also be used for the credit for increasing research activities, but expenses that are also qualified research expenses are included in base period research expenses in a later year.
The instructions say testing conducted inside or outside the United States by a corporation to which section 936 applies is not eligible for the orphan drug credit.

3800
1,921 fields, 9 pages
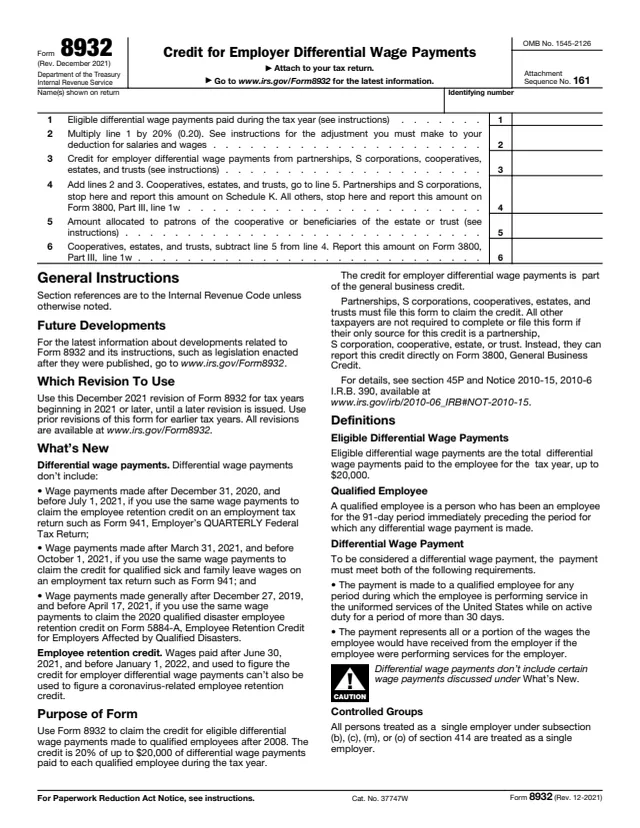
8932
8 fields, 2 pages
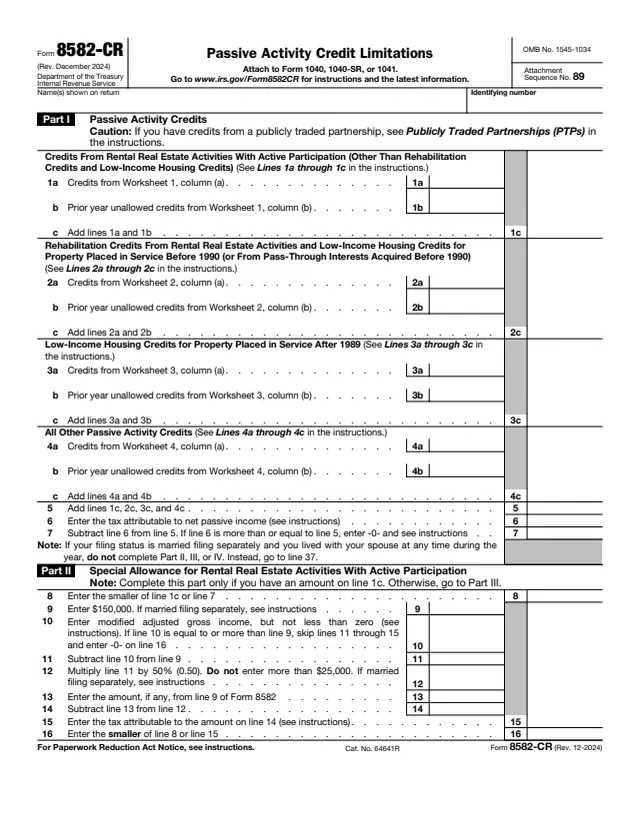
8582-CR
52 fields, 2 pages
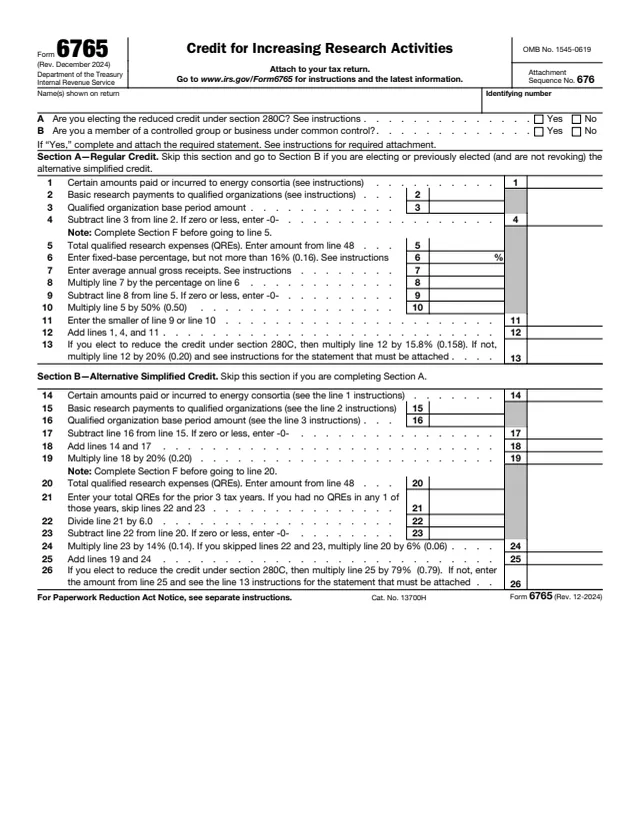
6765
270 fields, 4 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
The taxpayer claiming the credit completes the form and attaches it to its own tax return.
No tool matches that search.
The form says the credit is 25% of qualified clinical testing expenses. With the reduced credit election under section 280C, line 1 is multiplied by 19.75% instead.
The instructions say one that afflicts 200,000 or fewer persons in the United States, or more than 200,000 where there is no reasonable expectation of recovering the cost of developing and making the drug available from U.S. sales.
The form says taxpayers that are not partnerships, S corporations, estates or trusts, and whose only source of the credit is those entities, are not required to file it and can report the credit directly on Form 3800.
No. The instructions say qualified clinical testing expenses used for the orphan drug credit cannot also be used to figure the credit for increasing research activities.
The instructions say that once made, the election is irrevocable for that tax year.
The instructions say qualified clinical testing expenses do not include expenses to the extent they are funded by a grant, contract, or otherwise by a governmental entity or another person.