Header
EIN, name, trade name and address, boxes for an address change and for a final return, and the Aggregate Return Filers Only section.
943
Employer's Annual Federal Tax Return for Agricultural Employees
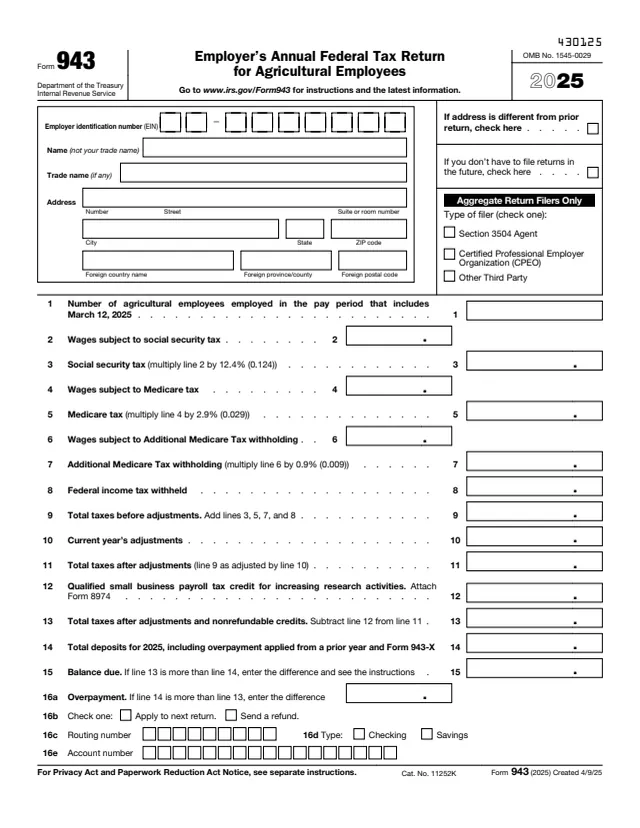
Form 943 is the Employer's Annual Federal Tax Return for Agricultural Employees. The IRS About page says to file it if wages were paid to one or more farmworkers and the wages were subject to federal income, Social Security, and Medicare taxes. This page holds the 2025 form.
The return reports the number of agricultural employees in the pay period that includes March 12, 2025, wages subject to social security and Medicare taxes and the tax on them, Additional Medicare Tax withholding and federal income tax withheld for the year. It then subtracts any qualified small business payroll tax credit for increasing research activities, compares the total with deposits and shows a balance due or an overpayment. Page 2 holds the monthly summary of federal tax liability, the third-party designee, the signature and the paid preparer section.
The PDF also includes Form 943-V, the payment voucher. The PDF can be filled out free in the browser on this page and downloaded without an account.
EIN, name, trade name and address, boxes for an address change and for a final return, and the Aggregate Return Filers Only section.
Number of agricultural employees, wages subject to social security and Medicare taxes and the tax on each, wages subject to Additional Medicare Tax withholding and that tax, and federal income tax withheld.
Total taxes before adjustments, current year's adjustments, total after adjustments, the research payroll tax credit from Form 8974, and total taxes after adjustments and nonrefundable credits.
Total deposits for 2025, balance due, or an overpayment with a choice to apply it to the next return or send a refund, plus the routing number, account type and account number.
Monthly Summary of Federal Tax Liability, January through December, with a total on line 17m that the form says equals line 13.
Third-Party Designee, the signature and Paid Preparer Use Only sections on page 2, and the Form 943-V payment voucher.
Enter the EIN, name and address. The instructions say not to use an SSN or ITIN and to enter the business (legal) name used when applying for the EIN. Check the final return box if no future returns will be filed.
Enter the number of agricultural employees on the payroll in the pay period that included March 12, 2025. The instructions leave out household employees, employees in nonpay status, pensioners and active members of the U.S. Armed Forces.
Enter wages subject to social security tax and multiply by 12.4% (0.124), wages subject to Medicare tax and multiply by 2.9% (0.029), Additional Medicare Tax withholding at 0.9% (0.009), and the federal income tax withheld.
Add lines 3, 5, 7 and 8, enter any adjustment for fractions of cents or third-party sick pay on line 10, and subtract the Form 8974 credit on line 12. The instructions say line 13 can't be less than zero.
Enter total deposits. If line 13 is more, the difference goes on line 15. If line 14 is more, enter the overpayment on line 16a and check one box on line 16b. The instructions say never to make entries on both lines 15 and 16a.
The form says not to complete line 17 or Form 943-A if line 13 is less than $2,500. Otherwise monthly schedule depositors complete line 17 and semiweekly schedule depositors complete Form 943-A. Then sign and date page 2.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file the 2025 Form 943 by February 2, 2026, or by February 10, 2026, if deposits were made on time in full payment of the taxes due for the year.
The instructions say that after the first Form 943, a return is filed for each year, even with no taxes to report, until a final return is filed.
Electronic filing is encouraged. Without a payment, the instructions list Kansas City, MO 64999-0008 or Ogden, UT 84201-0008 by state. With a payment: Internal Revenue Service, P.O. Box 932200, Louisville, KY 40293-2200.
The instructions say that if line 13 is less than $2,500 for the year, the tax can be paid with a timely filed return. At $2,500 or more, deposits are made by EFT on a monthly or semiweekly schedule.
The instructions list EFT, credit card, debit card, check, money order or EFW for line 15 when deposits weren't required. A check or money order is payable to "United States Treasury" and sent with Form 943-V.
The instructions say Forms W-2 go to employees, and Copy A with Form W-3 to the SSA, by February 2, 2026. Lines 2, 4 and 8 of Form 943 should agree with the matching Form W-3 boxes.
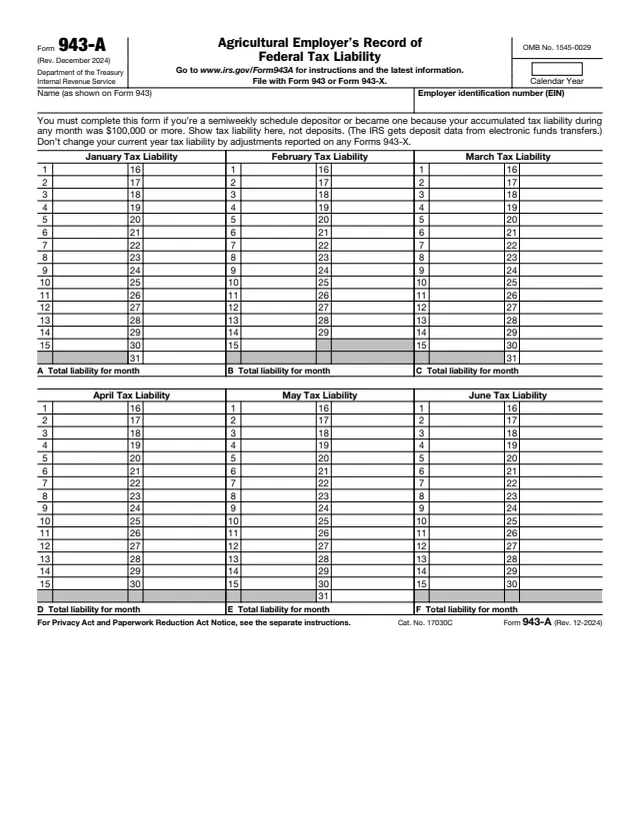
943-A
382 fields, 2 pages
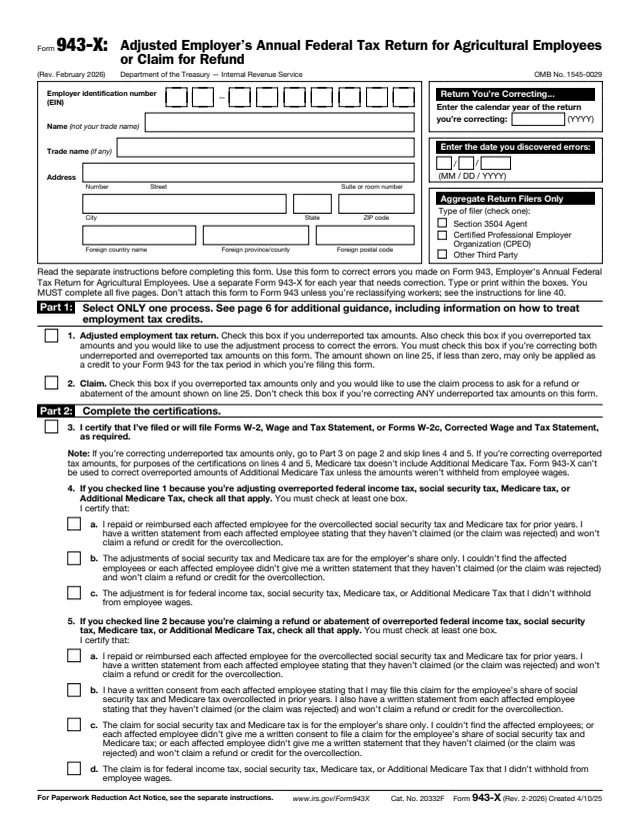
943-X
321 fields, 6 pages
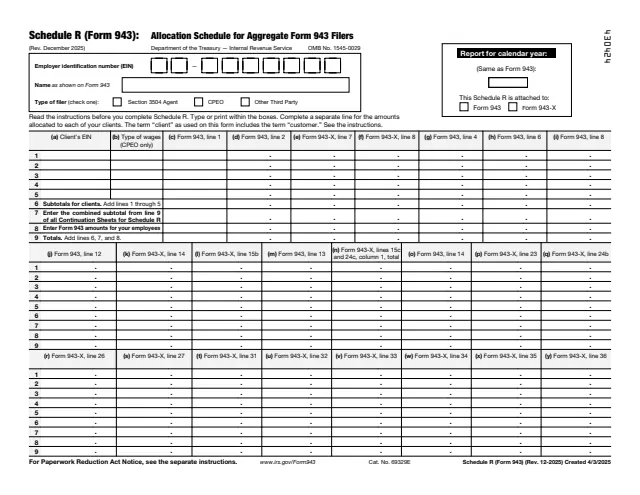
943 Sch. R
856 fields, 2 pages
940
97 fields, 3 pages
8974
107 fields, 1 page
W-2
568 fields, 11 pages
Form 943 is filed by agricultural employers, or by third parties filing aggregate returns for them. Farmworkers do not file it.
No tool matches that search.
The About page says it is filed by an employer that paid wages to one or more farmworkers when the wages were subject to federal income, Social Security, and Medicare taxes.
The instructions say February 2, 2026, or February 10, 2026, if deposits were made on time in full payment of the taxes due for the year.
The instructions say cash wages to farmworkers are covered for a year if an employee is paid $150 or more in cash wages for farmwork, or if total cash and noncash wages to all farmworkers are $2,500 or more.
The instructions say compensation of $600 or more paid to H-2A visa workers goes in box 1 of Form W-2, but compensation for agricultural labor under the visa isn't subject to social security and Medicare taxes and stays off lines 2, 4 and 6.
Neither if line 13 is less than $2,500. Otherwise the form says monthly schedule depositors complete line 17 and semiweekly schedule depositors complete Form 943-A.
The instructions say errors on a previously filed Form 943 are corrected on Form 943-X, which is filed separately from Form 943.
Yes. The instructions say the IRS now issues Form 943 refunds by direct deposit using lines 16c to 16e, or the overpayment can be applied to the next return on line 16b.