Entity information
Name, employer identification number and address of the entity.
8716
Election To Have A Tax Year Other Than a Required Tax Year
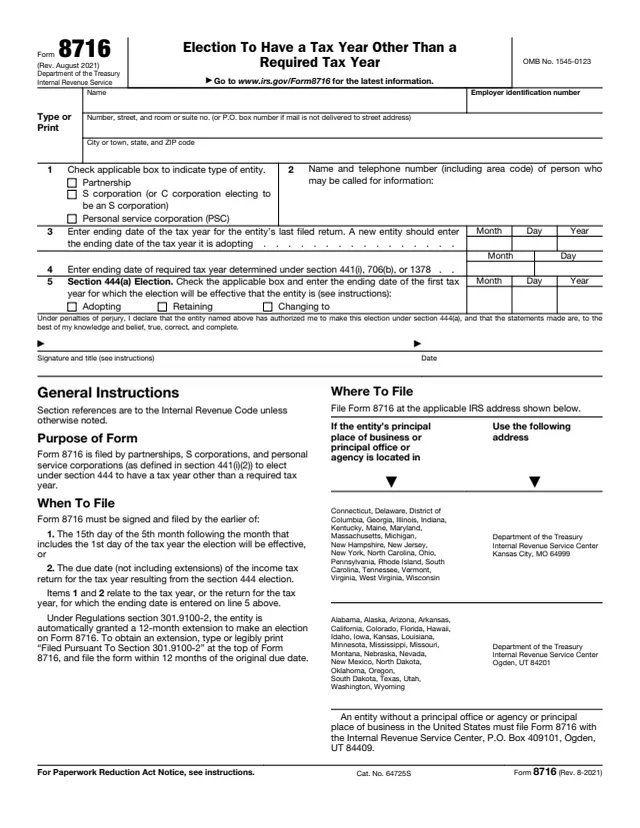
Form 8716 is filed by partnerships, S corporations, and personal service corporations (PSCs) to elect under section 444 to have a tax year other than a required tax year, the instructions say. They also say the required tax year for an S corporation or PSC is a calendar year, and that generally the required tax year for a partnership is the tax year of a majority of its partners.
The election is made only once. It stays in effect until the entity changes to its required tax year or another permitted year, or is penalized for willfully failing to comply with section 280H or 7519. An electing partnership or S corporation files Form 8752 for each year the election is in effect, while an electing PSC follows the minimum distribution requirements of section 280H instead.
You can fill out Form 8716 free in your browser on this page and download it without an account.
Name, employer identification number and address of the entity.
Boxes for partnership, S corporation (or C corporation electing to be an S corporation), or personal service corporation (PSC).
Name and telephone number, including area code, of a person the IRS may call for information.
The ending date of the tax year on the last filed return (or the year a new entity is adopting) and the ending date of the required tax year under section 441(i), 706(b), or 1378.
Boxes for adopting, retaining or changing to, and the ending date of the first tax year for which the election will be effective.
A declaration under penalties of perjury, the signature and title, and the date.
Check the box showing whether the entity is classified for federal income tax purposes as a partnership, an S corporation (or a C corporation electing to be one), or a PSC.
Enter the name and telephone number, including area code, of a person the IRS may call for information needed to process the election.
Enter the ending date of the tax year on the last filed return (a new entity enters the year it is adopting), then the ending date of the required tax year.
Check adopting, retaining or changing to, and enter the ending date of the first effective tax year. The instructions limit the deferral period, generally to not more than 3 months.
The instructions say Form 8716 is not a valid election unless it is signed by the person they name for the entity type.
For a backup section 444 election, type or print "Backup Election" at the top. For the automatic 12-month extension, type or print "Filed Pursuant To Section 301.9100-2" at the top.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
By the earlier of the 15th day of the 5th month following the month that includes the 1st day of the tax year the election will be effective, or the due date (not including extensions) of the return for the tax year resulting from the election.
Kansas City, MO 64999 or Ogden, UT 84201, based on the state of the principal place of business, office or agency. An entity with none in the United States files with the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
The instructions say to also file a copy with the income tax return for the first tax year of the election. To enable electronic filing, an unsigned copy with the same information may be filed.
Under Regulations section 301.9100-2, the instructions say the entity is automatically granted a 12-month extension, with that heading on the form and filing within 12 months of the original due date.
The service center stamps an accepted election "Accepted" and returns a copy. The instructions say to keep that copy for your records.
Electing partnerships and S corporations file Form 8752 for each year the election is in effect, by May 15 following the calendar year in which each applicable election year begins.
8752
53 fields, 1 page
2553
100 fields, 4 pages
1120
45 fields, 2 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages

1120
481 fields, 6 pages
The form is filed by business entities, and signed by a partner, member or corporate officer.
No tool matches that search.
Partnerships, S corporations, and personal service corporations that elect under section 444 to have a tax year other than a required tax year.
By the earlier of the 15th day of the 5th month following the month that includes the 1st day of the election tax year, or the due date (not including extensions) of the return for that year.
To the Kansas City or Ogden service center, based on the state list on the form. Entities without a U.S. office or place of business use P.O. Box 409101, Ogden, UT 84409.
The instructions define it as the number of months between the last day of the elected tax year and the last day of the required tax year. A September 30 year against a calendar year is 3 months.
No. The instructions say an electing PSC should not file Form 8752 and instead follows the minimum distribution requirements of section 280H.
No. The instructions say that if the election is terminated, the entity may not make another section 444 election.