Header and entity information
The base year ending date, then the name of the partnership or S corporation, its EIN and its address.
8752
Required Payment or Refund Under Section 7519
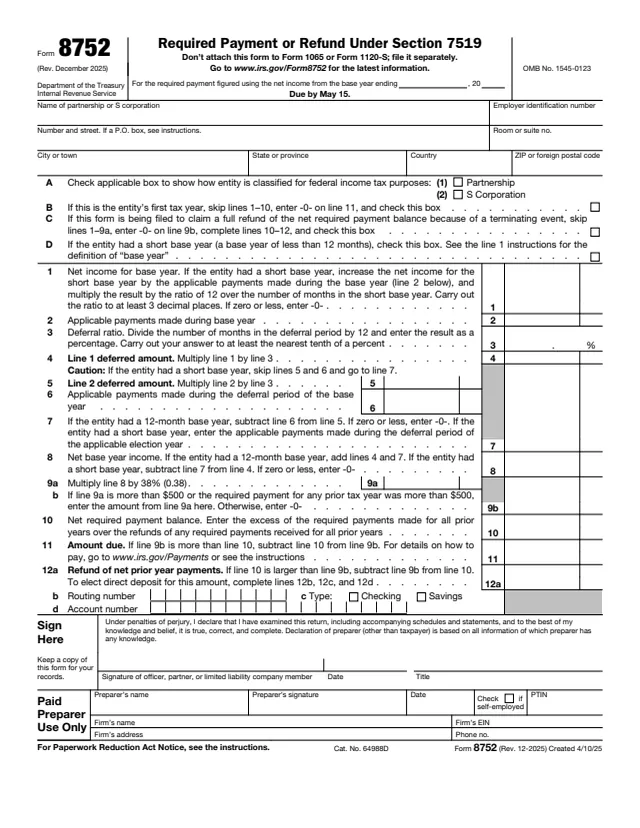
Form 8752 is used by partnerships and S corporations to figure and report the payment required under section 7519 or to obtain a refund of net prior-year payments, the instructions say. They also say section 7519 payments are required of any partnership or S corporation that has elected under section 444 to have a tax year other than a required tax year.
The form starts with the entity's name, EIN and address, its classification, and boxes for a first tax year, a terminating event or a short base year. Lines 1 to 9 work from net income for the base year and applicable payments through a deferral ratio to a required payment at 38%. Lines 10 to 12 compare that with prior payments to show an amount due or a refund, with direct deposit fields. The form says not to attach it to Form 1065 or Form 1120-S, but to file it separately.
You can fill out Form 8752 free in your browser on this page and download it without an account.
The base year ending date, then the name of the partnership or S corporation, its EIN and its address.
Classification as partnership or S corporation, and boxes for a first tax year, a full refund because of a terminating event, and a short base year.
Net income for the base year, applicable payments, the deferral ratio, deferred amounts and payments during the deferral period, ending in net base year income.
Line 8 multiplied by 38% (0.38), carried to line 9b only if it is more than $500 or a prior year's required payment was more than $500.
The net required payment balance, the amount due, and the refund of net prior year payments with routing number, account type and account number.
A declaration under penalties of perjury, the signature, date and title, and the Paid Preparer Use Only area.
Enter the ending date of the base year and check the classification. A first tax year skips lines 1 to 10 and enters -0- on line 11. A terminating event skips lines 1 to 9a, enters -0- on line 9b and completes lines 10 to 12.
Enter net income for the base year and applicable payments. The instructions say applicable payments include officer's compensation, wages and rent paid to a partner or shareholder, but not guaranteed payments.
Divide the months in the deferral period by 12 and enter a percentage to at least the nearest tenth. The instructions' example is an S corporation with a November 1 year, which has a 2 month deferral period.
Multiply lines 1 and 2 by line 3, enter applicable payments for the deferral period, and combine as the form directs. A short base year skips lines 5 and 6.
Multiply line 8 by 38%, apply the $500 test on line 9b, enter the net required payment balance, and figure any amount due. The instructions list EFTPS, check, same-day wire and cash as ways to pay.
If line 10 is larger than line 9b, enter the refund and the direct deposit details. The instructions say the routing number is nine digits and the account number can be up to 17 characters. Then sign and date.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Due by May 15." The instructions say that for applicable election years beginning in 2025, the form is filed and the required payment made on or before May 15, 2026.
Kansas City, MO 64999 or Ogden, UT 84201, based on the state of the principal place of business, office or agency. An entity with none in the United States files with the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
The form says not to attach it to Form 1065 or Form 1120-S, and to file it separately.
The instructions say the entity may have to pay a penalty equal to 10% of the underpayment if the required payment isn't made by the due date, unless the failure was due to reasonable cause and not willful neglect.
The instructions say no refund will be made before the later of April 15, 2026, or 90 days after Form 8752 is filed, and no interest will be paid on the amount refunded.
To correct an error, the instructions say to file an amended Form 8752 and write "Amended Return" across the top.
The form is filed by business entities with a section 444 election in effect, and signed by an officer, partner or limited liability company member.
No tool matches that search.
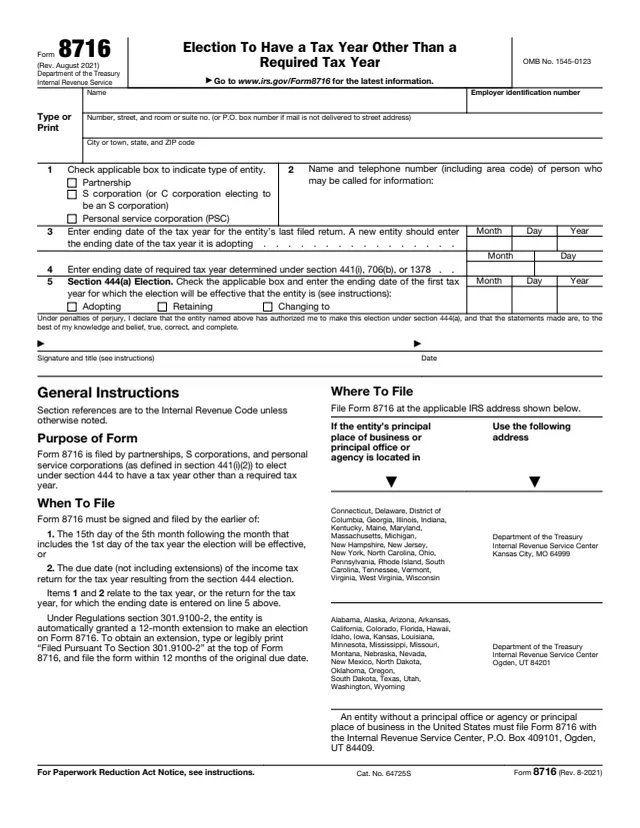
Partnerships and S corporations that made a section 444 election by filing Form 8716 while the election is in effect, and those that terminate the election or liquidate and claim a refund.
Yes. The instructions say it is filed for each year the section 444 election is in effect, even if the required payment for the applicable election year is zero.
No. The form says not to attach it to Form 1065 or Form 1120-S and to file it separately.
The form says by May 15. For applicable election years beginning in 2025, the instructions give May 15, 2026.
The instructions say the base year is the tax year preceding the applicable election year.
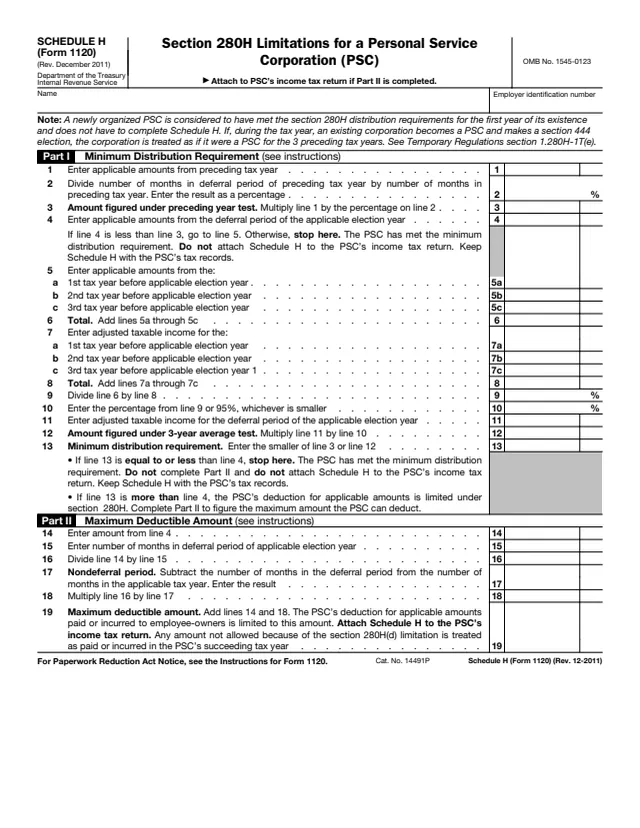
No. The instructions say to file Schedule H (Form 1120) with the corporation's income tax return instead.