8621

Information Return by a Shareholder of a Passive Foreign Investment Company or Qualified Electing Fund

Agency
IRS
Revision
Rev. December 2025
Fillable fields
151
Pages
4
Official source
IRS form page
Checked
October 21, 2026
Fill 8621 online
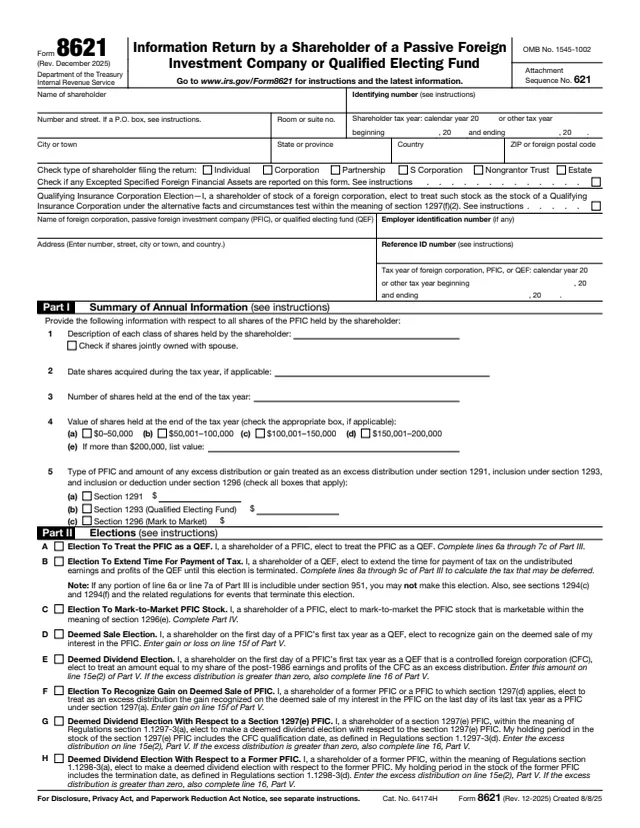
Page 1 of form 8621

Form 8621: Information Return by a Shareholder of a PFIC or Qualified Electing Fund

Form 8621 is the Information Return by a Shareholder of a Passive Foreign Investment Company or Qualified Electing Fund. The About Form 8621 page says a U.S. person that is a direct or indirect shareholder of a passive foreign investment company (PFIC) files it if they receive certain direct or indirect distributions from a PFIC, recognize a gain on a direct or indirect disposition of PFIC stock, are reporting information with respect to a QEF or section 1296 mark-to-market election, are making an election reportable in Part II of the form, or are required to file an annual report under section 1298(f).

The filer can be an individual, a corporation, a partnership, an S corporation, a nongrantor trust or an estate, and the form has a box for each. The instructions say a separate Form 8621 is filed for each PFIC in which stock is held directly or indirectly. The December 2025 revision adds a three-letter currency code entry above line 15a and a new line 15e(2) for the amount in U.S. dollars.

You can fill out the PDF free in your browser on this page and download the result without an account.

What's on Form 8621

Identification

Shareholder name, identifying number, address, tax year and type of shareholder, boxes for excepted specified foreign financial assets and the qualifying insurance corporation election, and the PFIC or QEF name, address, EIN or reference ID number and tax year.

Part I: Summary of Annual Information

Each class of shares, date acquired, number of shares and value at year end, and the type of PFIC with amounts under sections 1291, 1293 and 1296.

Part II: Elections

Elections A to H, including the election to treat the PFIC as a QEF, to extend the time for payment of tax, to mark-to-market PFIC stock, and the deemed sale and deemed dividend elections.

Part III: Income From a QEF

Lines 6a to 7c for the pro rata share of the QEF's ordinary earnings and net capital gain, and lines 8a to 9c for the deferred tax under Election B.

Part IV: Mark-to-Market

Lines 10a to 14c for fair market value, adjusted basis, unreversed inclusions, and stock sold or otherwise disposed of during the year.

Parts V and VI

Part V covers distributions from and dispositions of stock of a section 1291 fund, with the currency code and excess distribution lines 15 and 16. Part VI reports the status of prior year section 1294 elections and their termination.

How to fill out Form 8621

  1. 1

    Shareholder details

    The instructions say individuals enter a Social Security number or a taxpayer identification number issued by the IRS, and all other entities enter an EIN. Check one type of shareholder box.

  2. 2

    PFIC details

    A reference ID number is required only when no EIN is entered for the PFIC. The instructions say it is alphanumeric, has no special characters or spaces, is limited to 50 characters and stays the same from year to year.

  3. 3

    Part I

    Describe each class of shares, the date acquired during the year, the number held and the value at year end. The instructions say periodic account statements provided at least annually may be relied on for value, with stated limits.

  4. 4

    Part II

    Check each election being made. For Election A, the instructions say a separate election is made for each PFIC the shareholder wants to treat as a QEF.

  5. 5

    Parts III and IV

    All QEF shareholders complete lines 6a through 7c, and Election B adds lines 8a through 9c. Under a mark-to-market election, lines 10a to 12 cover stock held at year end and lines 13a to 14c cover stock sold or disposed of.

  6. 6

    Part V

    Complete a separate Part V for each excess distribution and disposition. Enter the three-letter currency code above line 15a, the U.S. dollar amount on line 15e(2), and attach the line 16a statement allocating the amount to each day in the holding period.

Why fill Form 8621 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where to send it and timing

With the tax return

The instructions say to attach Form 8621 to the shareholder's tax return (or partnership or exempt organization return) and file both by the due date, including extensions, at the IRS service center where that return is filed.

No return to file

If no income tax return or other return is required for the year, the instructions say to file Form 8621 directly with the Internal Revenue Service Center, Ogden, UT 84201-0201.

One form per PFIC

A separate Form 8621 is filed for each PFIC, including each PFIC in a chain of ownership in the circumstances the instructions describe.

Part I value exceptions

The instructions describe an exception to completing Part I for a section 1291 fund when the aggregate value of PFIC stock is $25,000 or less ($50,000 for a joint return) and no excess distribution or gain occurs, and a $5,000 exception for indirect stock.

Late elections

Several elections can be made on an amended return within 3 years of the due date of the original return. The instructions point to Form 8621-A when that period has expired.

Form 8938 box

Check the excepted specified foreign financial assets box only if the filer also files Form 8938 and counts this form on line 4 of Part IV of Form 8938.

Who files Form 8621?

  • Individual shareholders

    U.S. persons who hold PFIC stock directly or indirectly. The instructions say shareholders filing a joint return may file a single Form 8621 for a single PFIC in which each joint filer owns an interest.

  • Partnerships, S corporations, trusts and estates

    The instructions list a U.S. partnership, S corporation, U.S. trust or U.S. estate that is a direct or indirect shareholder of a PFIC among the interest holders that file, unless an exception applies.

  • Indirect shareholders

    For example, a 50%-or-more shareholder of a foreign corporation that is not a PFIC and owns PFIC stock, a shareholder of a PFIC that owns another PFIC, or an owner of a pass-through entity that holds PFIC stock.

  • Qualifying insurance corporation election

    A U.S. person that elects to treat stock of a foreign corporation as stock of a qualifying insurance corporation under section 1297(f)(2) files a limited-information Form 8621.

  • Holdings through tax-exempt accounts

    The instructions say a U.S. person that owns PFIC stock through certain tax-exempt organizations or accounts, such as an individual retirement plan, a section 403(b) or 457(b) plan, or a section 529, 530 or 529A program, is not treated as a shareholder of the PFIC.

The instructions say a U.S. person that is a direct or indirect shareholder of a PFIC files Form 8621 for each tax year in the five circumstances the About page lists.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 8621

Is a separate Form 8621 needed for each PFIC?

Yes. The instructions say a separate Form 8621 is filed for each PFIC in which stock is held directly or indirectly.

Where does Form 8621 go if I do not file a tax return?

The instructions say to file it directly with the Internal Revenue Service Center, Ogden, UT 84201-0201.

What makes a foreign corporation a PFIC?

The instructions say it meets the income test (75% or more of gross income is passive income) or the asset test (at least 50% of the average percentage of assets produce, or are held to produce, passive income).

Is there an exception for small holdings?

For Part I, the instructions describe a $25,000 exception ($50,000 on a joint return) for a section 1291 fund when there is no excess distribution or gain, and a $5,000 exception for indirect ownership.

Do PFIC funds held in an IRA count?

The instructions say a U.S. person that owns PFIC stock through an individual retirement plan or annuity, among other listed tax-exempt accounts, is not treated as a shareholder of the PFIC.

What changed in the December 2025 revision?

The instructions list a new three-letter currency code entry above line 15a and a new line 15e(2) that reports the line 15e(1) amount in U.S. dollars.