Part I: Reporting Authority
The amended return box, issuer's name and EIN, a contact person, address, date of issue, name of issue, CUSIP number, and an officer's name, title and phone number.
8038-TC
Information Return for Tax Credit Bonds and Specified Tax Credit Bonds
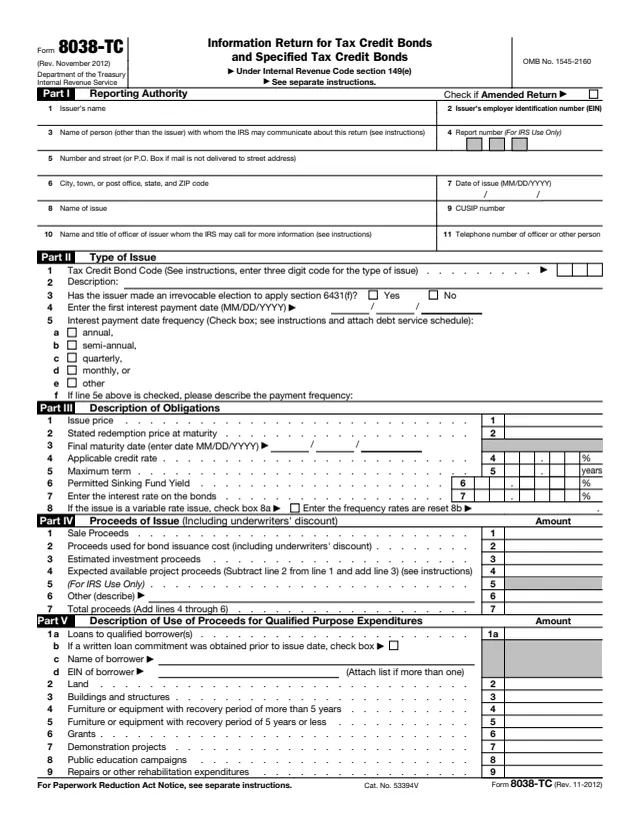
Form 8038-TC, Information Return for Tax Credit Bonds and Specified Tax Credit Bonds, is filed by the issuer of a bond issue. The instructions say issuers use it "to provide the IRS with the information required by section 149(e)." A separate form is filed for each bond issue.
The IRS About page says Form 8038-TC is historical: the Tax Cuts and Jobs Act repealed the authority to issue tax-credit bonds and direct-pay bonds, and the repeal applies to qualified forestry conservation bonds, new clean renewable energy bonds, qualified energy conservation bonds, qualified zone academy bonds and qualified school construction bonds issued after December 31, 2017.
The form has eight parts plus Schedules A to D for specific bond types. The current form is the November 2012 revision and its instructions were revised in September 2018. You can fill out the form free in your browser on this page and download the result without an account.
The amended return box, issuer's name and EIN, a contact person, address, date of issue, name of issue, CUSIP number, and an officer's name, title and phone number.
A three-digit Tax Credit Bond Code, a description, whether the issuer made an irrevocable election to apply section 6431(f), the first interest payment date and the payment frequency.
Issue price, stated redemption price at maturity, final maturity date, applicable credit rate, maximum term, permitted sinking fund yield, interest rate and variable rate details.
Sale proceeds, issuance costs, investment proceeds and total proceeds, then the qualified purpose expenditures, such as loans, land, buildings, equipment and grants, and the percentage of proceeds they use.
The volume cap allocation, arbitrage and other miscellaneous questions, the signature and consent block, and Part VIII on consent to publish certain issue information.
Separate schedules for new clean renewable energy bonds (code 102), qualified energy conservation bonds (103), qualified zone academy bonds (104) and qualified school construction bonds (105).
Enter the name of the entity issuing the bonds, not the entity receiving the financing. Line 4 is for IRS use only. On line 9, enter the CUSIP number of the latest maturity and attach a list of all CUSIP numbers, or write "None."
Enter the three-digit code for the bond type. The instructions list 101 to 106 and 108 for other. If no section 6431(f) election was made, the instructions say to skip lines 4 and 5.
Enter the obligation terms, the proceeds and how they are used. The instructions allow rounding to whole dollars, as long as all amounts are rounded.
Enter the source and amount of any bond limitation allocation and attach a copy of the certificate, as the form asks. Issuers of specified tax credit bonds also attach the debt service schedule described in the Part II instructions.
Complete the schedule for the bond type. The instructions say every attached schedule shows the issuer's name and EIN at the top.
The authorized representative signs and prints their name and title. Part VIII is signed by an officer if the issuer consents; the instructions say it does not apply to issuers that elected direct payment under section 6431(f).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file on or before the 15th day of the 2nd calendar month after the close of the calendar quarter in which the bond was issued, and not before the issue date.
The instructions say the form is filed at least 30 days before the first Form 8038-CP requesting payment for that issue.
File the form and attachments with the Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201.
An extension may be granted under section 3 of Rev. Proc. 2002-48. The instructions say to type "Request for Relief under section 3 of Rev. Proc. 2002-48" at the top and attach a letter explaining the delay.
Check the Amended Return box, report all the original information plus the changes, and attach an explanation titled "Amended Return Explanation."
The instructions name Form 8038-T for arbitrage rebate payments and Form 8038-CP for requesting a direct payment of a refundable credit.
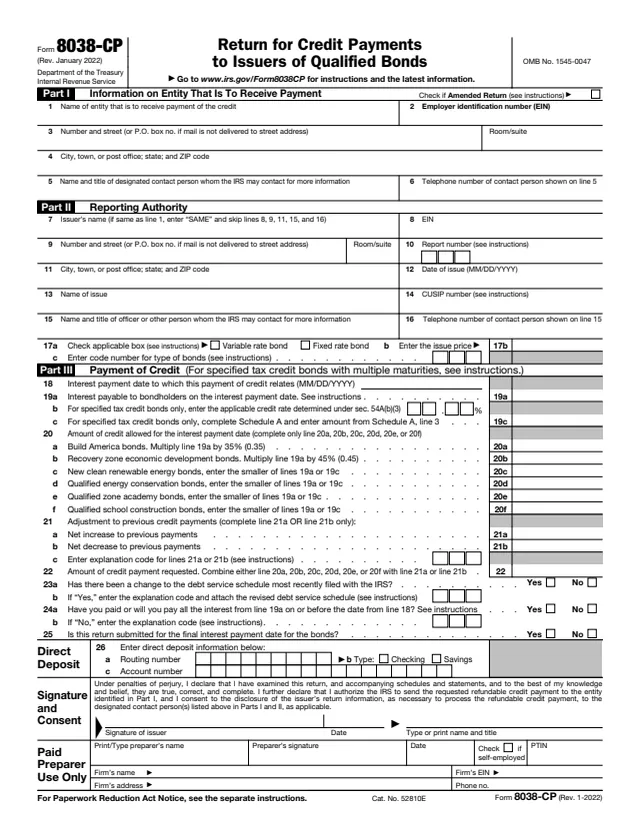
8038-CP
59 fields, 1 page
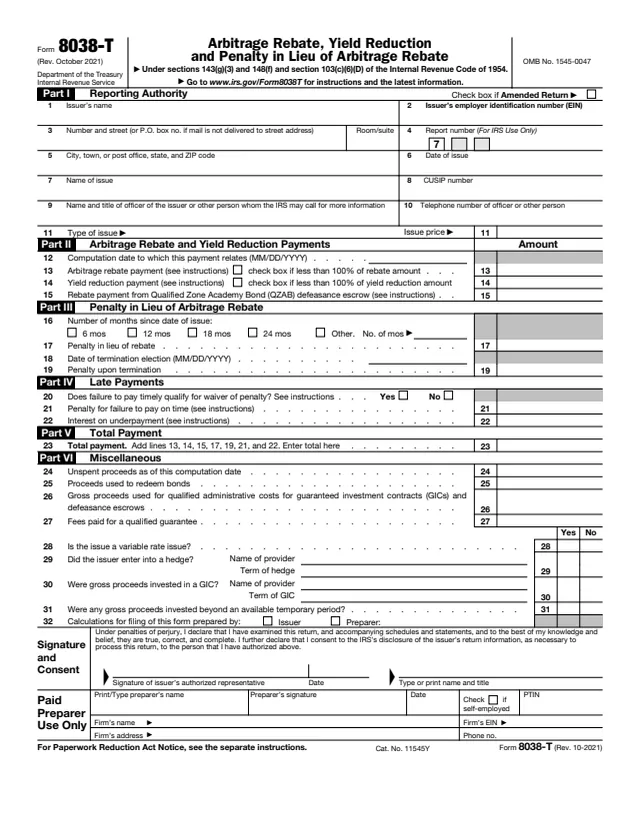
8038-T
60 fields, 1 page
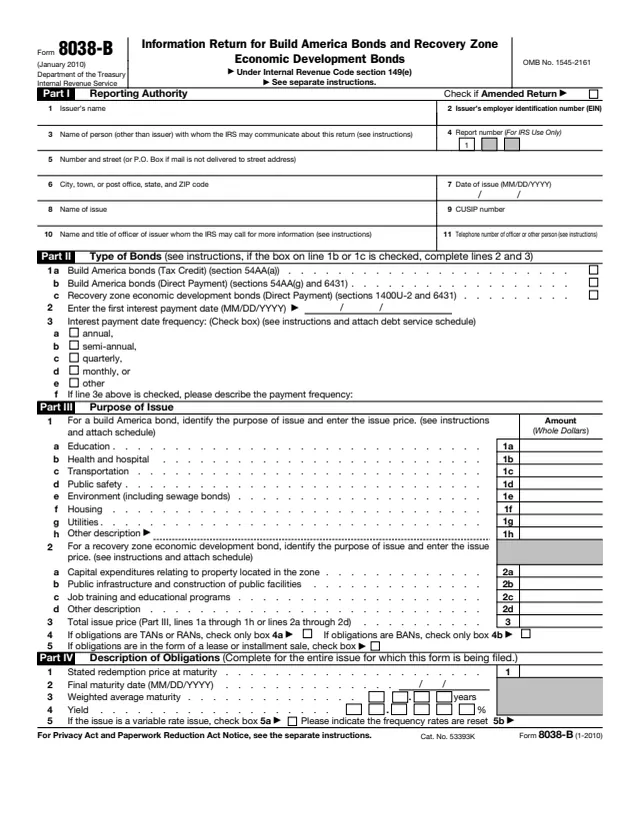
8038-B
92 fields, 2 pages
8912
218 fields, 3 pages
8038-CP Sch. A
259 fields, 2 pages
8038
137 fields, 3 pages
The form is filed by the issuer of the bonds and signed by the issuer's authorized representative. It is not a form an individual bondholder files.
No tool matches that search.
The About page says the form is historical. The Tax Cuts and Jobs Act repealed the authority to issue tax-credit bonds and direct-pay bonds issued after December 31, 2017.
The issuer of the bonds, with a separate form for each issue, signed by the issuer's authorized representative.
On or before the 15th day of the 2nd calendar month after the close of the calendar quarter in which the bond was issued.
With the Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201.
For specified tax credit bonds, the instructions say Form 8038-TC is filed at least 30 days before the first Form 8038-CP for the issue, and only issuers that elected under section 6431(f) may file Form 8038-CP.
The instructions say build America bonds are reported on Form 8038-B.