Part I: Current Year Credit
Lines 1 to 6: credits from Part III and Part IV, carryforward of credits for qualified tax credit bonds and build America bonds, the total credit, and for estates and trusts the amount allocated to beneficiaries.
8912
Credit to Holders of Tax Credit Bonds
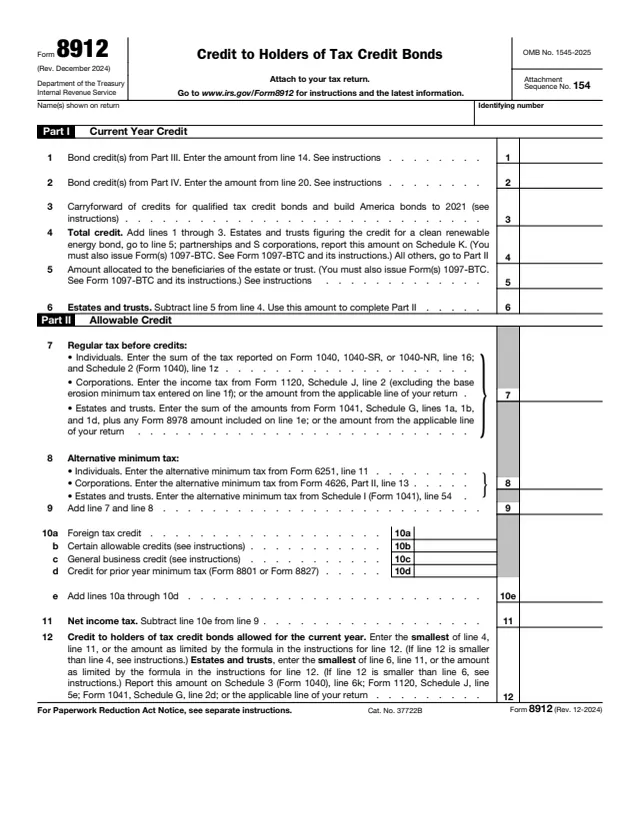
Form 8912, Credit to Holders of Tax Credit Bonds, is attached to a tax return to claim the credit for six kinds of bonds: clean renewable energy bonds (CREBs), new clean renewable energy bonds (NCREBs), qualified energy conservation bonds (QECBs), qualified zone academy bonds (QZABs), qualified school construction bonds (QSCBs) and build America bonds (BABs).
The instructions say the credit compensates the holder for lending money to the issuer and functions as interest paid on the bond. They also say the credit is not available for bonds issued after December 31, 2017, and the form warns not to enter any bond credits for bonds issued after 2017.
The instructions say Form 8912 is no longer updated annually, only when necessary. This page has the Rev. December 2024 edition. You can fill it out free in your browser on this page and download the result without an account.
Lines 1 to 6: credits from Part III and Part IV, carryforward of credits for qualified tax credit bonds and build America bonds, the total credit, and for estates and trusts the amount allocated to beneficiaries.
Lines 7 to 12: regular tax before credits and alternative minimum tax for individuals, corporations or estates and trusts, other credits on lines 10a to 10d, net income tax and the credit allowed for the current year.
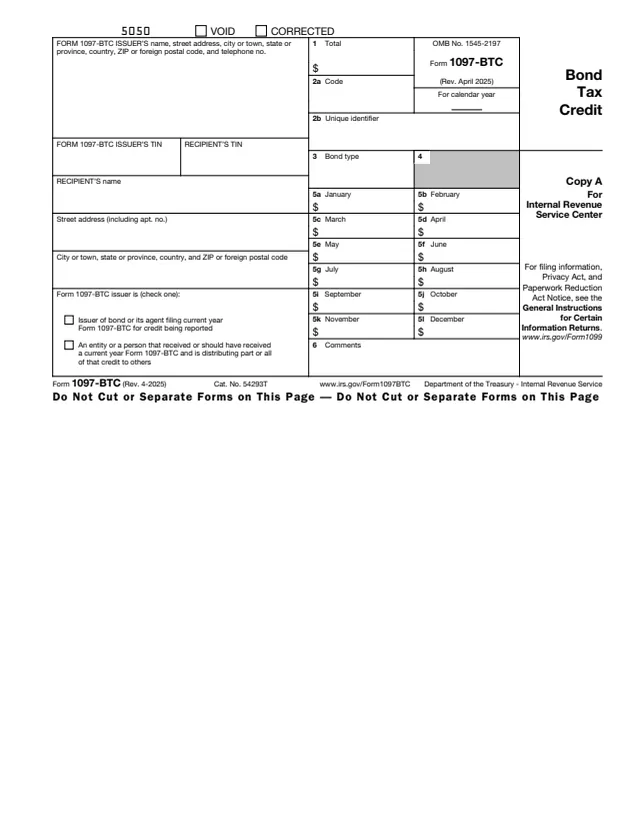
Line 13 lists each issuer of Form 1097-BTC, its identifying number, the unique identifier and the amount reported. Line 14 totals column (c).
Lines 15 to 17 take the issuer's name, location and EIN, the dates issued and maturing, and any date disposed of. Line 18 figures the credit for each bond from CUSIP number, principal, credit rate and percentage.
Line 19 adds column (f). For an NCREB or QECB, line 20 is line 19 multiplied by 70% (0.70); for a CREB, QZAB, QSCB or BAB it is the line 19 amount. Line 20 goes to line 2.
The instructions say to complete Parts III and IV before Parts I and II, and that separate entries are required for each bond with a different issuance date or a different credit rate.
From each Form 1097-BTC, enter the issuer's federal identification number, the unique identifier in box 2b and the amount in box 1. Credits from a pass-through entity on Form 1097-BTC go here, not on line 18.
Enter the CUSIP number, outstanding principal (interest payable for a BAB), credit rate and percentage. The instructions say the BAB credit rate is 35%, and column (e) is generally 25% for each credit allowance date held, or 100% for a BAB or a QZAB issued before October 4, 2008.
Carry line 14 to line 1 and line 20 to line 2. Line 3 is a carryforward for qualified tax credit bonds or BABs; the instructions say credits for a CREB, or a QZAB issued before October 4, 2008, can't be carried forward.
Enter regular tax and alternative minimum tax from the lines the form names for the return type, subtract the credits on lines 10a to 10d, and enter on line 12 the smallest of line 4 (or line 6), line 11 or the limit in the instructions.
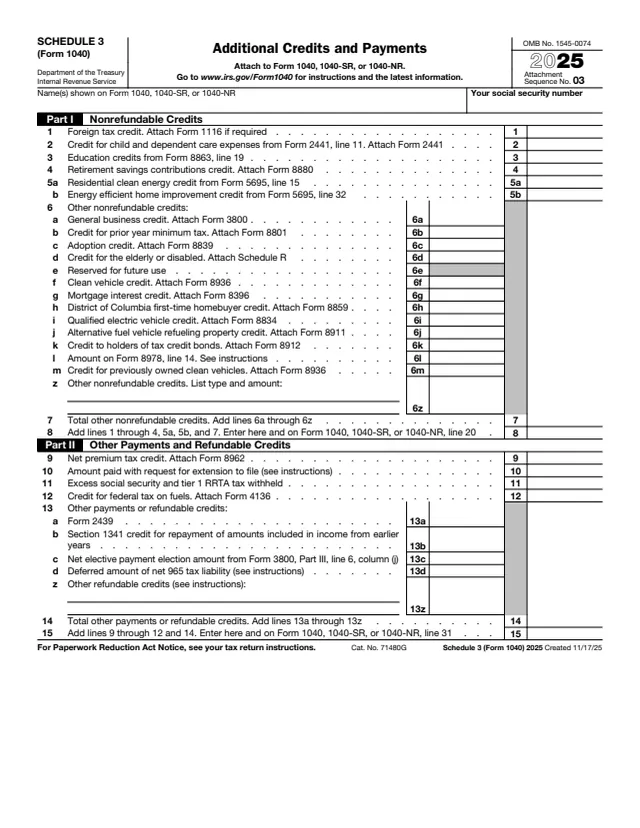
The form says to report line 12 on Schedule 3 (Form 1040), line 6k; Form 1120, Schedule J, line 5e; Form 1041, Schedule G, line 2d; or the applicable line of your return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." Its attachment sequence number is 154.
The instructions say holders of a qualified tax credit bond or a BAB may carry an unused credit to the next tax year, while holders of a CREB, or a QZAB issued before October 4, 2008, can deduct the unused credit instead.
The instructions say the current year credit is treated as taxable interest income paid on the credit allowance date, or for BABs the interest payment date.
The form and instructions say not to enter any bond credits for bonds issued after December 31, 2017.
When a pass-through entity reports the same credit on Form 1097-BTC and on a Schedule K-1, the instructions say to include only the Form 1097-BTC amount, on Part III, line 13.
1097-BTC
55 fields, 3 pages
1040
37 fields, 1 page

1120
481 fields, 6 pages

1041
173 fields, 3 pages

3800
1,921 fields, 9 pages

1065
111 fields, 1 page
The instructions say a taxpayer holding a CREB or qualified tax credit bond on one or more credit allowance dates claims the credit by filing Form 8912 for each tax year in which it holds the bond on a credit allowance date.
No tool matches that search.
The IRS lists CREBs, NCREBs, QECBs, QZABs, QSCBs and build America bonds (BABs).
The instructions say the credit is not available for bonds issued after December 31, 2017, and the form says not to enter bond credits for bonds issued after 2017.
The form says to complete Part IV for a bond credit not reported on Form 1097-BTC. The instructions say to use one Part IV for each bond held directly or through a nominee, or for each credit passed through without a Form 1097-BTC.
The instructions say the current year credit is deemed a payment of qualified stated interest and is treated as taxable interest income paid on the credit allowance date, or for BABs the interest payment date.
The instructions list March 15, June 15, September 15 and December 15, plus the last day on which the qualified tax credit bond is outstanding.
No. The instructions say Form 8912 and its instructions will no longer be updated annually and will only be updated when necessary.