Issuer and recipient boxes
The issuer's name, address and telephone number, the issuer's TIN, and the recipient's TIN, name and street address.
1097-BTC
Bond Tax Credit
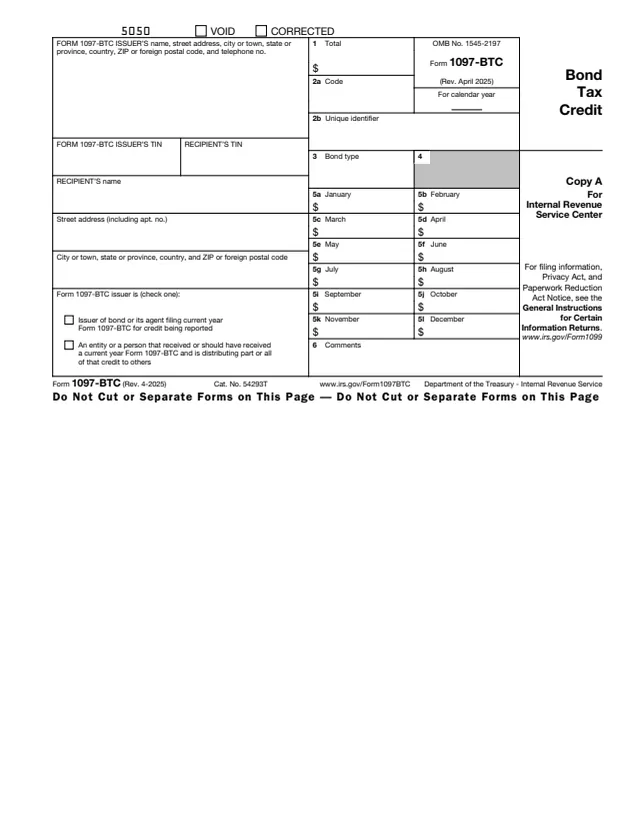
Form 1097-BTC, Bond Tax Credit, is an information return. The IRS About page says issuers of certain tax credit bonds (or their agents) and recipients of Form 1097-BTC from the bond issuer or agent, such as mutual funds or partnerships, who are further distributing the credit file this form for each tax credit distributed.
The form shows the amount of tax credit the recipient is allowed for each month of the calendar year, in boxes 5a to 5l, with the yearly total in box 1. The instructions list the bonds it covers: new clean renewable energy bonds, qualified energy conservation bonds, qualified zone academy bonds, qualified school construction bonds, clean renewable energy bonds and build America bonds (Tax Credit).
Copy A goes to the IRS and Copy B goes to the recipient. The instructions say this revision is a continuous use revision for tax year 2025 and later years until a superseding revision is issued. You can fill out Form 1097-BTC free in your browser on this page and download the result without an account.
The issuer's name, address and telephone number, the issuer's TIN, and the recipient's TIN, name and street address.
Two boxes: the issuer of the bond or its agent filing the current year form, or an entity or person that received a current year form and is distributing part or all of that credit to others.
Box 1 is the total of credits allowed for the calendar year. Box 2a is a code for the kind of identifier, and box 2b is the unique identifier itself, limited to 39 alphanumeric characters.
Box 3 holds the bond type code: 101 for clean renewable energy bonds and 199 for other bonds. Box 4 is reserved.
One box for each month from January to December, showing the amount of credit allowed for that month.
Space for any additional information the form issuer provides.
Enter the entity's true name and the address of its principal office, not the address of a registered agent. The issuer's TIN is never truncated. The recipient's TIN may be truncated only on the statement to the recipient, not on the form filed with the IRS.
Check the first box when filing as the issuer of the bond or its agent. Check the second box when distributing part or all of a credit received on another Form 1097-BTC.
Enter C for a CUSIP number, A for an account number or O for any other identifier. The instructions say a bond issuer or its agent starts box 2b with the CUSIP number when one is available.
Enter 101 for clean renewable energy bonds issued under section 54 and 199 for all other bonds. The instructions say credits from clean renewable energy bonds go on a separate Form 1097-BTC.
Enter the credit for each month, figured with STEP 1 and STEP 2 in the instructions. For new clean renewable energy bonds and qualified energy conservation bonds, the instructions say to report the credit after the 70% limit is applied.
Enter the total of boxes 5a to 5l. The instructions say box 1 is filled in only on Copy A and on the annual statement to the recipient. On the statements for the first 3 quarters, box 1 is left blank and box 6 is optional.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions list the furnishing dates as May 15, August 15, November 15 and February 15 for the four quarters, and note that dates may change due to weekends or holidays. There is no separate 4th quarter report: those amounts go on the annual statement.
The instructions point to the current General Instructions for Certain Information Returns for filing due dates. A filer qualified to file on paper sends the black-and-white Copy A printed from the IRS website with Form 1096. Others follow the electronic filing procedures.
The recipient statement can be Copy B or the filer's own substitute statement with the same information. The statements for the first 3 quarters may be furnished electronically. Pub. 1179 has the rules for substitute statements.
If amounts furnished for the first 3 quarters need to be corrected, the instructions say to report the correct amounts on the annual filing and explain the correction to the recipient. No explanation is required for the IRS filing.
The instructions say there are penalties for failure to file correct information returns by the due date and for failure to furnish correct payee statements, and refer to part O of the General Instructions for Certain Information Returns.
The instructions say the tax credit allowed to holders is treated as interest included in gross income and is reported as interest income on Form 1099-INT or Form 1099-OID, as applicable.
1099-INT
127 fields, 7 pages
1099-OID
111 fields, 7 pages
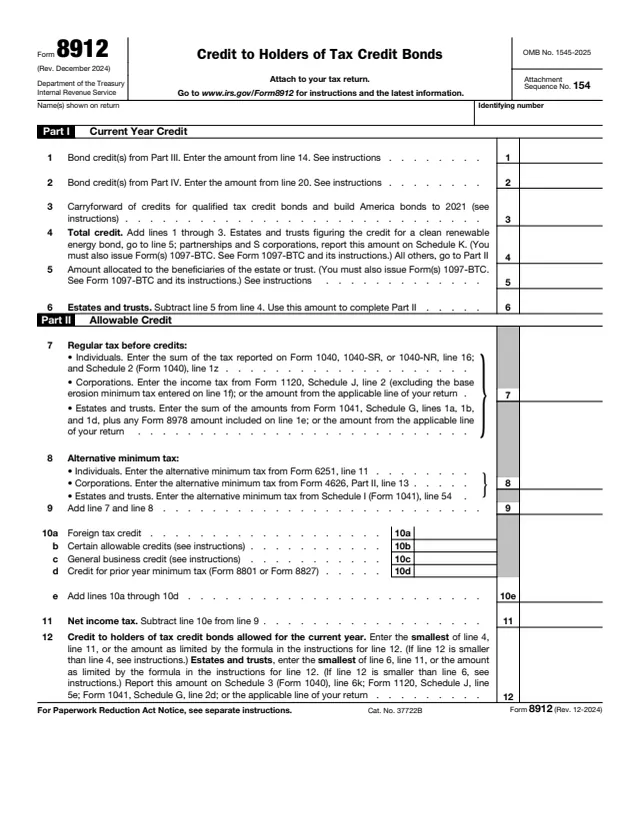
8912
218 fields, 3 pages
1096
55 fields, 3 pages
SS-4
89 fields, 2 pages
The form is filed by bond issuers, their agents, and the entities that pass the credit on. The person who holds the bond receives Copy B and does not file this form.
No tool matches that search.
Issuers of certain tax credit bonds or their agents, and entities such as brokers, nominees, mutual funds or partnerships that received the form and further distribute the credit.
The instructions say each person allowed a credit of at least $10 during the calendar year as a holder, directly or indirectly, of a tax credit bond or stripped credit coupon is issued the form.
Quarterly for the first 3 quarters, then an annual statement that also covers the 4th quarter. The Copy B text says the annual statement is furnished on or before the 15th day of the 2nd calendar month after the close of the calendar year.
Copy B says the first 3 quarters on the annual report repeat amounts reported earlier, and that the credit amount from each quarter is taken only once.
Code 101 is for clean renewable energy bonds and code 199 is for all other bonds covered by the form.
Copy B says the form may show only the last four digits of the recipient's TIN for protection, while the issuer has reported the complete TIN to the IRS.
Copy B says the holder may be entitled to claim a credit against income tax, subject to certain limitations under section 54A(c), and refers to Form 8912 for more information.