Part I: Reporting Authority
Lines 1 to 10b: issuer's name and EIN, another contact person, address, date of issue, name of issue, CUSIP number, and the officer or employee the IRS may call. A box at the top marks an amended return.
8038
Information Return for Tax-Exempt Private Activity Bond Issues
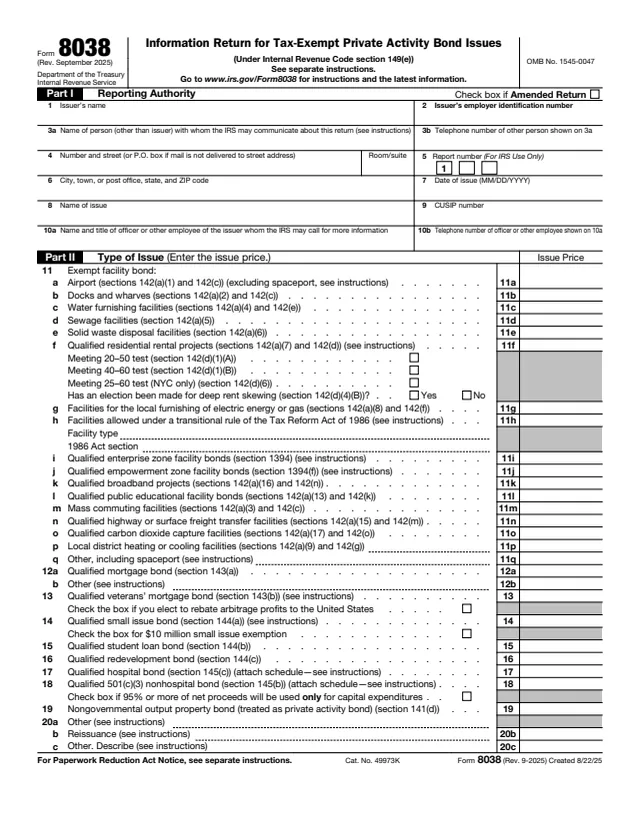
Form 8038, Information Return for Tax-Exempt Private Activity Bond Issues, is filed under Internal Revenue Code section 149(e). The instructions say issuers of tax-exempt private activity bonds use it to provide the IRS with the information required by section 149 and to monitor compliance with the requirements of sections 141 through 150.
The form reports one bond issue: the issuer and its contacts, the type of bond and its issue price, the maturity and yield, how the proceeds are used, the property financed, any bonds being refunded, hedges and investment contracts, public approval, and the volume cap allocated to the issue. An authorized representative of the issuer signs it.
Tax-exempt bonds other than private activity bonds are reported on Form 8038-G or Form 8038-GC instead. You can fill out Form 8038 free in your browser on this page and download the result without an account.
Lines 1 to 10b: issuer's name and EIN, another contact person, address, date of issue, name of issue, CUSIP number, and the officer or employee the IRS may call. A box at the top marks an amended return.
Lines 11 to 20: the issue price entered next to the bond type, from exempt facility bonds to mortgage, small issue, student loan, redevelopment, hospital, 501(c)(3), output property and reissued bonds.
Line 21: final maturity date, issue price, stated redemption price at maturity, weighted average maturity and yield.
Lines 22 to 30: accrued interest, issuance costs including underwriters' discount, credit enhancement, reserve or replacement funds, refunding of prior bonds, and nonrefunding proceeds.
Lines 31 to 36: land, buildings, equipment and other property financed, the NAICS codes of the projects, and the maturity and dates of any bonds being refunded.
Lines 37 to 52: approving governmental unit, arbitrage and hedge items, guaranteed investment contracts, written procedures, reimbursements, the primary private user and volume caps, then signature and consent.
Enter the issuer's name, EIN and address. Line 5 is for IRS use only. On line 9 enter the CUSIP number of the bond with the latest maturity, or "None." The instructions say to complete lines 10a and 10b even if lines 3a and 3b are completed.
Enter the issue price in the box for the type of bond. The instructions say elections referred to in Part II are made on the original bond documents, not on this form. Lines 12b and 20a are for IRS use only.
Complete line 21 for the entire issue. The instructions say to write "VR" as the yield of a variable rate issue and otherwise carry the yield out to four decimal places.
Enter the proceeds used for each purpose. If no proceeds paid bond issuance costs, the instructions say to enter zero on line 24 and not leave it blank. Line 30 subtracts line 29 from line 23.
The form says not to complete Part V for qualified student loan, qualified mortgage or qualified veterans' mortgage bonds. Line 32 takes six-digit NAICS codes, with a separate sheet for more than four projects. Part VI is only for refunding bonds.
On line 37 enter the governmental unit approving the issue with the approval dates, or "No approval needed" with the exception. Attach the state certification called for on lines 47 and 52. The authorized representative signs and dates the form.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file by the 15th day of the 2nd calendar month after the close of the calendar quarter in which the bond was issued. It may not be filed before the issue date and is completed based on the facts as of the issue date.
The instructions give Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201 for Form 8038 and any attachments.
An extension may be granted under section 3 of Rev. Proc. 2002-48 if the failure is not due to willful neglect. The instructions say to print "Request for Relief under section 3 of Rev. Proc. 2002-48." at the top and attach a letter explaining the delay.
Check the Amended Return box. The amended return gives all the information on the original plus the new or corrected information, with an explanation of the reason attached.
Line 39 marks the election for a construction issue. The instructions say the penalty is payable with Form 8038-T and no payment is made with this form.
Certain IRS-designated private delivery services can be used to meet the timely mailing as timely filing rule. The instructions point to IRS.gov/PDS for the current list.
8038-G
72 fields, 2 pages
8038-GC
35 fields, 3 pages
8038-T
60 fields, 1 page
8328
34 fields, 2 pages
SS-4
89 fields, 2 pages
8038-R
40 fields, 3 pages
The instructions say issuers file a separate Form 8038 for each issue of tax-exempt private activity bonds issued after 1986. Line 1 names the entity issuing the bonds, not the entity receiving the benefit of the financing.
No tool matches that search.
The issuer of tax-exempt private activity bonds. The instructions say a separate Form 8038 is filed for each issue issued after 1986.
The instructions say by the 15th day of the 2nd calendar month after the close of the calendar quarter in which the bond was issued, and not before the issue date.
The instructions say tax-exempt bonds other than private activity bonds go on Form 8038-G or Form 8038-GC.
The instructions describe relief under section 3 of Rev. Proc. 2002-48 when the failure is not due to willful neglect, with a statement typed at the top and a letter explaining why it was late.
By filing an amended return for the same date of issue with the Amended Return box checked, all the original information plus the changes, and an attached explanation.
The instructions say the issuer's name is the name of the entity issuing the bonds, not the name of the entity receiving the benefit of the financing.