Part I: entity to receive payment
Lines 1 to 6: name, EIN and address of the entity that is to receive the credit, and a contact person and telephone number. A box marks an amended return.
8038-CP
Return for Credit Payments to Issuers of Qualified Bonds
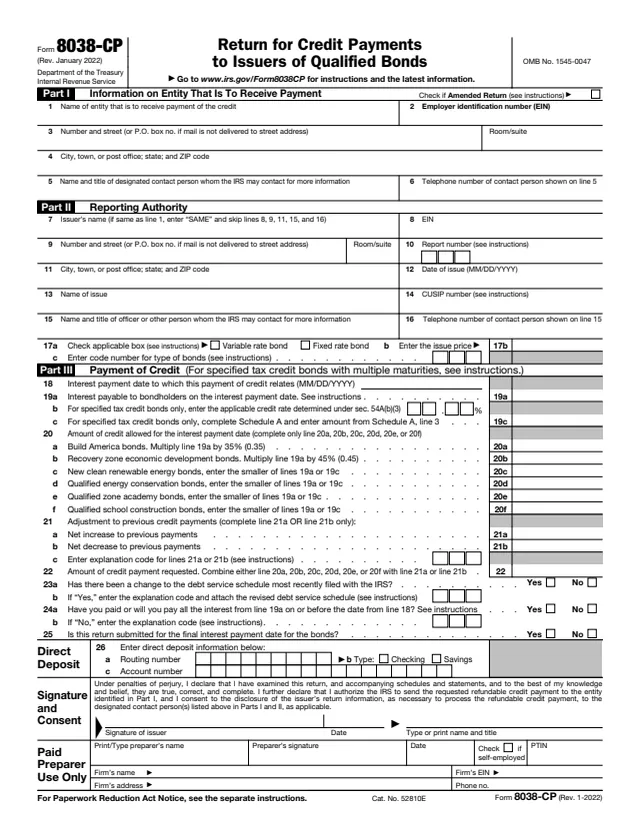
Form 8038-CP is the return bond issuers file to request a direct payment from the federal government. The IRS says issuers of build America bonds, recovery zone economic development bonds and specified tax credit bonds submit it to request a payment equal to a percentage of the interest payments on these bonds.
The instructions say only issuers of build America bonds and recovery zone economic development bonds issued before January 1, 2011, and specified tax credit bonds issued before January 1, 2018, that elected to receive a refundable credit under former section 6431 may file it. Each payment request relates to one interest payment date on a single bond issue, and each type of bond is reported on a separate Form 8038-CP. Specified tax credit bonds also need Schedule A (Form 8038-CP).
You can fill out the PDF free in your browser on this page and download it without an account.
Lines 1 to 6: name, EIN and address of the entity that is to receive the credit, and a contact person and telephone number. A box marks an amended return.
Lines 7 to 17: the issuer's name, EIN and address, report number, date of issue, name of issue, CUSIP number, contact person, rate type, issue price and bond type code.
The interest payment date, the interest payable to bondholders, and the credit allowed. Line 20a multiplies line 19a by 35% for build America bonds and line 20b by 45% for recovery zone bonds.
Adjustments to previous payments, the credit payment requested on line 22, and Yes or No questions on the debt service schedule, interest paid and the final interest payment date.
Routing number, account type and account number if the payment is to be deposited directly.
The issuer's signature, date and printed name and title, followed by the Paid Preparer Use Only area.
Enter the name and EIN of the entity that is to receive the payment. The instructions say they should match Form 8038-B or Form 8038-TC, Part I, when the issuer is that entity.
Enter SAME on line 7 if the issuer is the line 1 entity. On line 10 enter the report number the issuer assigned, in the range 401 to 450, and on line 14 the nine-character CUSIP number or None.
Check one rate box, enter the issue price from Form 8038-B or Form 8038-TC, and enter the bond type code, for example 109 for build America bonds or 110 for recovery zone bonds.
Enter the interest payment date and interest payable, complete only one of lines 20a to 20f, use line 21a or 21b to correct prior payments, and combine them on line 22. The instructions say to enter cents.
Answer the Yes or No questions. A Yes on line 23a or a No on line 24a needs an explanation code, and line 23b also needs a revised debt service schedule.
Complete line 26 for direct deposit, or leave it blank for a check to the Part I entity. An officer with authority to bind the issuer signs and prints a name and title.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file no later than 45 days before the relevant interest payment date and not earlier than 90 days before it.
When the interest amount is not known 45 days ahead, the instructions say to aggregate payments quarterly and file in arrears no later than 45 days after the last interest payment date in the quarter.
The instructions say a filer required to file at least 10 returns of any type during the calendar year files Form 8038-CP electronically starting in 2024. Others may file electronically voluntarily.
Paper returns go to Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0050, as the instructions list.
The line 22 payment is sent by check to the Part I entity, or deposited to the account on lines 26a and 26c. The instructions say an offset against other taxes or obligations can reduce it.
The instructions say to use the January 2022 version of Form 8038-CP and the December 2022 version of Schedule A.
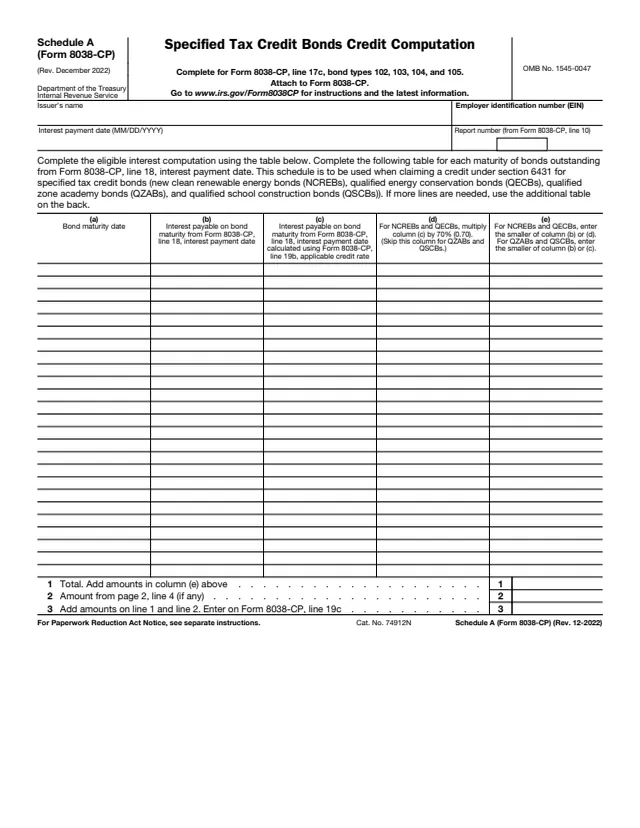
8038-CP Sch. A
259 fields, 2 pages
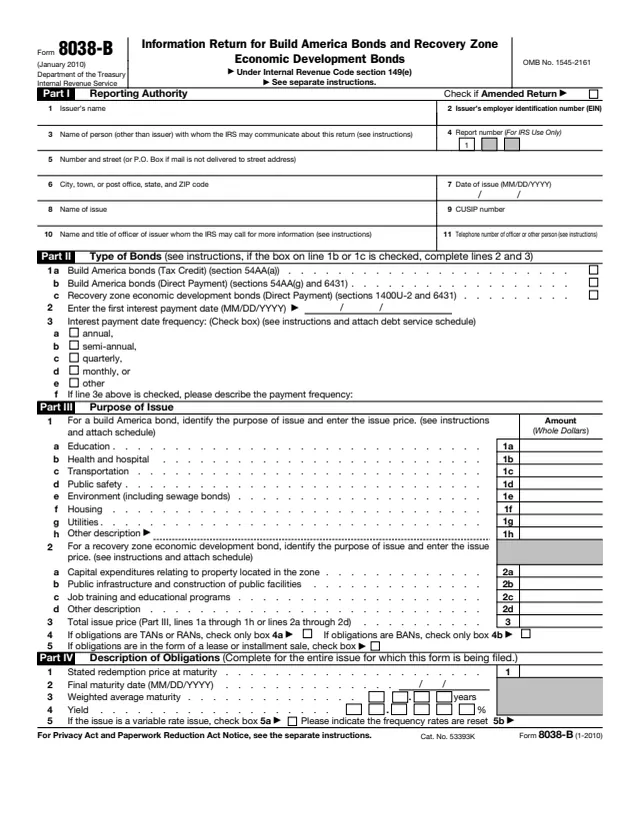
8038-B
92 fields, 2 pages
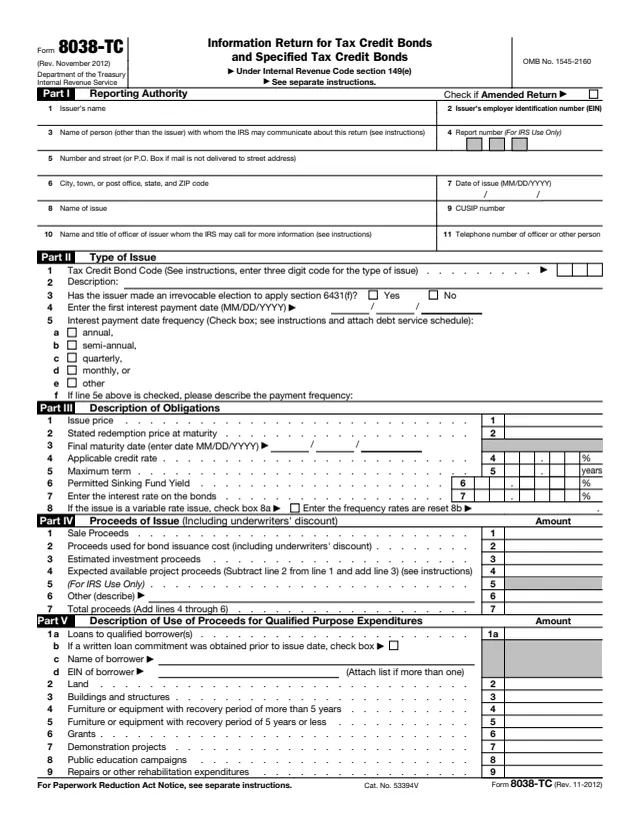
8038-TC
225 fields, 5 pages
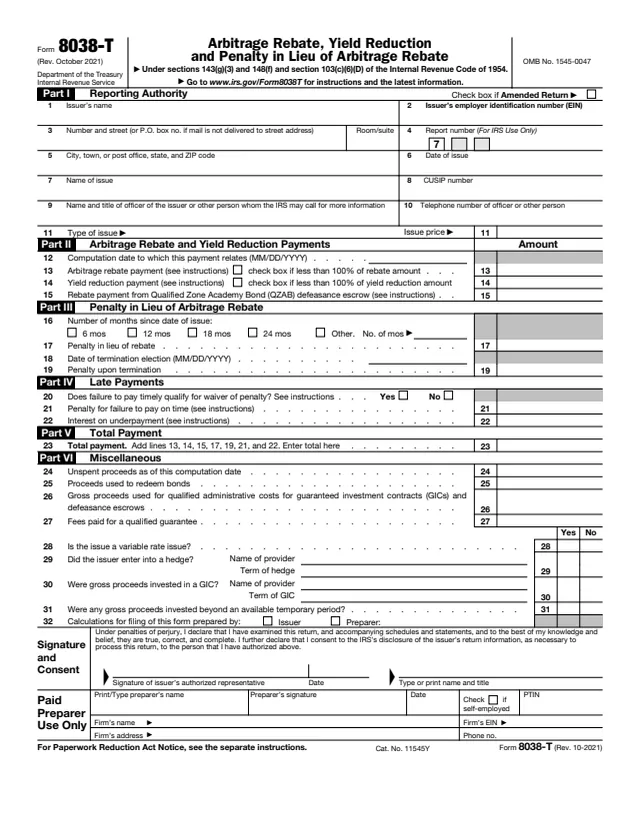
8038-T
60 fields, 1 page
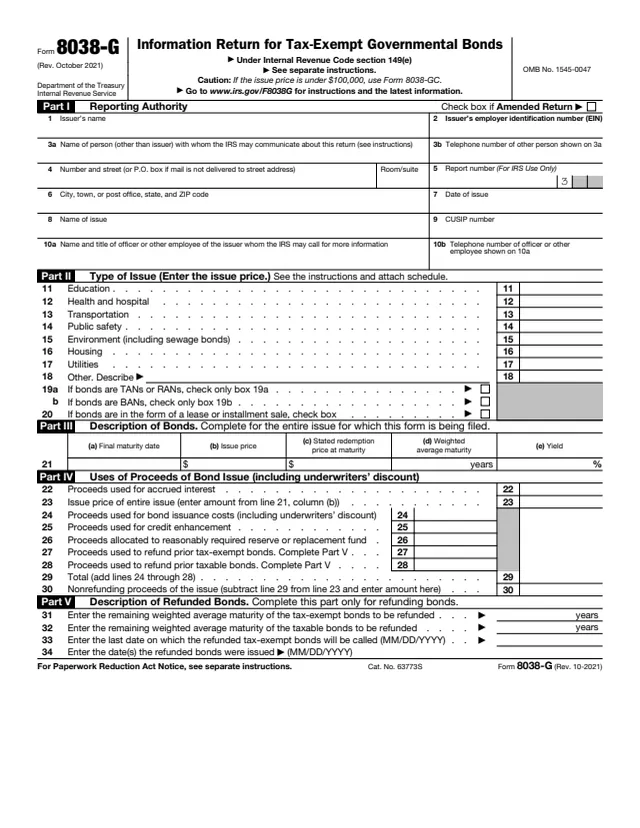
8038-G
72 fields, 2 pages
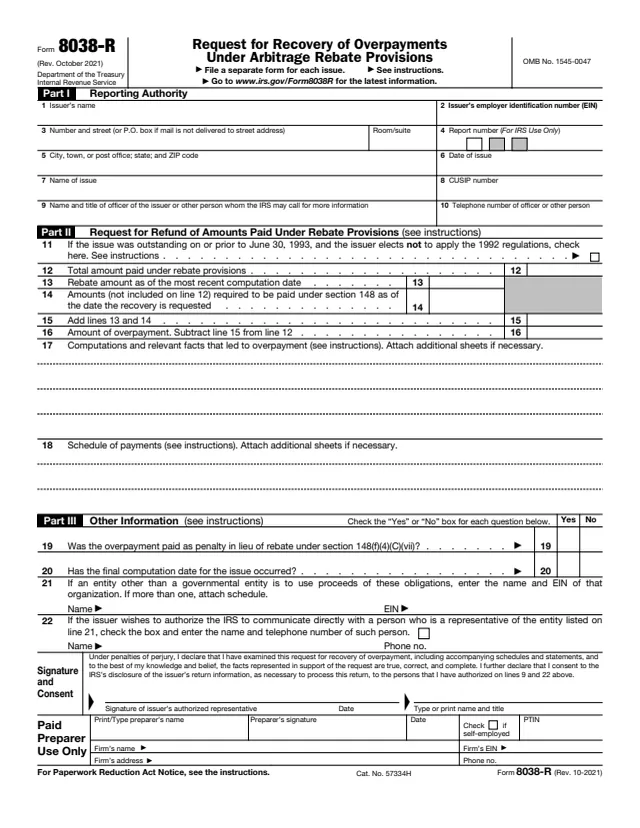
8038-R
40 fields, 3 pages
The issuer of the bonds files it, and an officer of the issuer with authority to bind the issuer signs it. It is not a form for individual bondholders.
No tool matches that search.
The IRS says issuers of build America bonds, recovery zone economic development bonds and specified tax credit bonds submit it to request a direct payment equal to a percentage of the interest payments on these bonds.
The instructions say only issuers of build America bonds and recovery zone bonds issued before January 1, 2011, and specified tax credit bonds issued before January 1, 2018, that elected a refundable credit under former section 6431 may file it.
The instructions say Schedule A is submitted for all new clean renewable energy bonds, qualified energy conservation bonds, qualified zone academy bonds and qualified school construction bonds. Line 19c takes the amount from Schedule A, line 3.
No. The instructions say each type of bond, and fixed rate and variable rate bonds of the same issue, are reported on separate Forms 8038-CP with separate report numbers.
The instructions say issuers assign a permanent three-digit report number in the range 401 to 450 to each separately reported bond and keep using it on every future Form 8038-CP for those bonds.
The instructions say an amended return can only be filed to correct errors in Part III on a previously filed final return. Other corrections use line 21a or 21b on a later return.