Line A: emissions and DOE number
The facility's emissions value or rate for each hydrogen production process, and the Department of Energy control number if applicable.
7210
Clean Hydrogen Production Credit
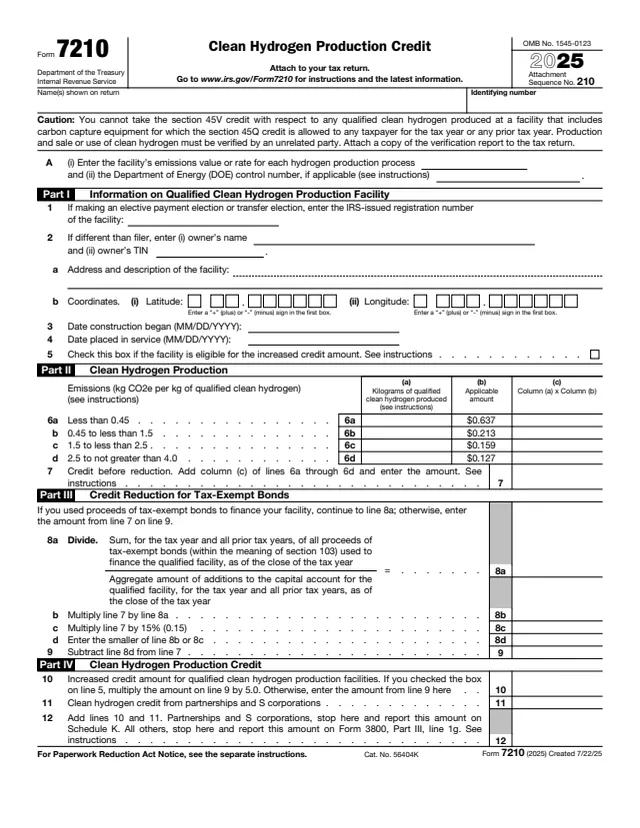
Form 7210 is the form a business uses to claim the section 45V credit for producing qualified clean hydrogen. The About page says the credit is for qualified clean hydrogen produced after 2022 at a qualified clean hydrogen production facility during the 10-year period beginning on the date the facility is originally placed in service. The form is attached to the tax return.
The instructions say to file a separate Form 7210 for each facility. The credit is the kilograms of qualified clean hydrogen produced multiplied by an applicable amount that depends on the lifecycle greenhouse gas emissions rate. For 2025 the form lists four amounts, from $0.637 down to $0.127 per kilogram. The form also says production and sale or use of the hydrogen must be verified by an unrelated party, with a copy of the verification report attached.
The instructions note that Public Law 119-21 eliminates the credit for facilities beginning construction after 2027. This page hosts the 2025 form. You can fill it out free in your browser on this page and download it without an account.
The facility's emissions value or rate for each hydrogen production process, and the Department of Energy control number if applicable.
Lines 1 to 5: the IRS-issued registration number, the owner if different from the filer, address, description and coordinates, construction and placed-in-service dates, and the increased credit box.
Lines 6a to 6d list four emissions bands with applicable amounts of $0.637, $0.213, $0.159 and $0.127. Kilograms produced times the amount gives column (c), totaled on line 7.
Lines 8a to 9 reduce the credit when tax-exempt bond proceeds financed the facility, using the smaller of line 7 times the bond fraction or line 7 times 15% (0.15).
Line 10 multiplies line 9 by 5.0 if the line 5 box is checked, line 11 adds credit from partnerships and S corporations, and line 12 is the total.
Enter the lifecycle greenhouse gas emissions value or rate in kg of CO2e per kg of qualified clean hydrogen for each production process, and the DOE control number if applicable.
Enter the pre-filing registration number if making an elective payment or transfer election. If the owner differs from the filer, add the owner's name and TIN, then the facility address, name or description, and coordinates.
Enter the date construction began and the date the facility was originally placed in service. Check line 5 only for the increased credit amount, which the instructions tie to Form 7220 and an attached statement.
Enter the kilograms of qualified clean hydrogen produced in the row for its emissions band, multiply by the applicable amount, and add column (c) on line 7. The instructions say to use only one emissions rate per process.
If tax-exempt bonds financed the facility, figure the bond fraction and reduction on lines 8a to 8d. Otherwise, the form says to enter the line 7 amount on line 9.
Apply the 5.0 multiplier if line 5 is checked, add any credit from Schedule K-1 (Form 1065) box 15 or Schedule K-1 (Form 1120-S) box 13 code Y on line 11, and total on line 12.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." A separate Form 7210 is filed for each qualified clean hydrogen production facility.
The form says partnerships and S corporations report line 12 on Schedule K, and all others report it on Form 3800, Part III, line 1g. The instructions describe exceptions for payment and transfer elections.
The form says production and sale or use of clean hydrogen must be verified by an unrelated party, and a copy of the verification report is attached to the return.
The instructions say a pre-filing registration for each facility is completed before filing the return when making an elective payment election or transfer election on Form 3800.
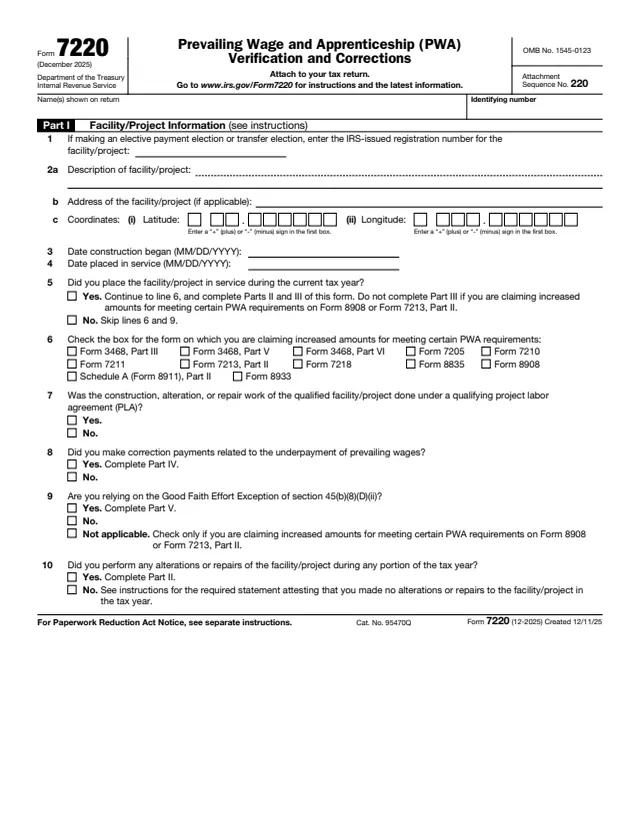
The instructions say claiming the increased credit for meeting the prevailing wage and apprenticeship requirements involves completing and attaching Form 7220.
The instructions say Public Law 119-21 eliminates the section 45V credit for facilities beginning construction after 2027.

3800
1,921 fields, 9 pages
7220
653 fields, 5 pages
990-T
128 fields, 2 pages
4255
646 fields, 5 pages

1065
111 fields, 1 page
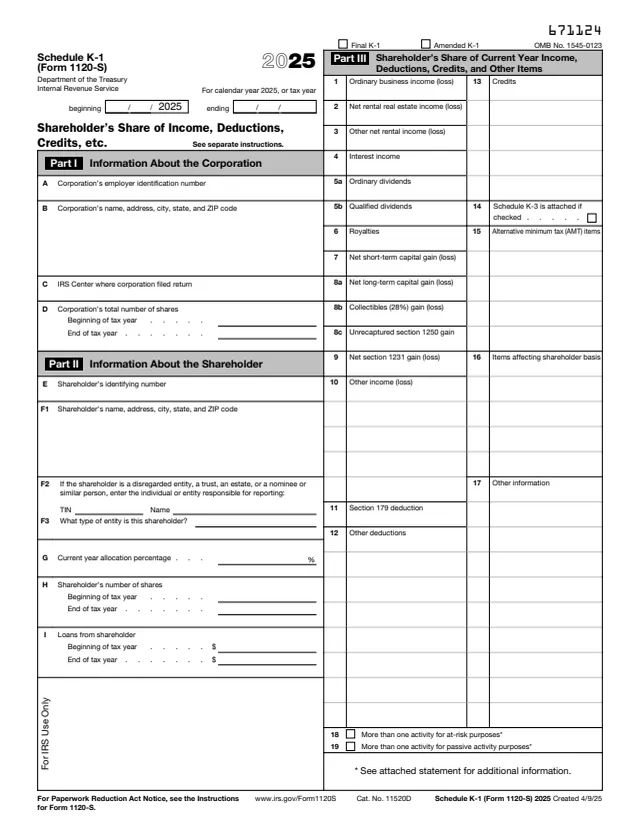
1120-S
114 fields, 1 page
The form is filed by businesses and other entities that produce qualified clean hydrogen at a facility they own, not by individuals reporting wages.
No tool matches that search.
The About page says it is used to claim the section 45V credit for qualified clean hydrogen produced after 2022 at a qualified facility during its 10-year credit period.
The instructions say they generally are not required to if their only source of the credit is a partnership or S corporation. They can report it directly on Form 3800.
The form lists $0.637 per kilogram for emissions less than 0.45, $0.213 for 0.45 to less than 1.5, $0.159 for 1.5 to less than 2.5, and $0.127 for 2.5 to not greater than 4.0.
The instructions say when the facility meets the prevailing wage and apprenticeship requirements, or began construction before January 29, 2023 and meets certain prevailing wage requirements.
No. The instructions say to file a separate Form 7210 for each qualified clean hydrogen production facility.
The form says no section 45V credit is allowed for hydrogen produced at a facility with carbon capture equipment for which the section 45Q credit is allowed to any taxpayer.