Preparer or promoter information
Name, identifying number, the address the statements of notice and demand were mailed to, the IRS office that sent them, and the preparer's address on the returns if different.
6118
Claim for Refund of Tax Return Preparer and Promoter Penalties
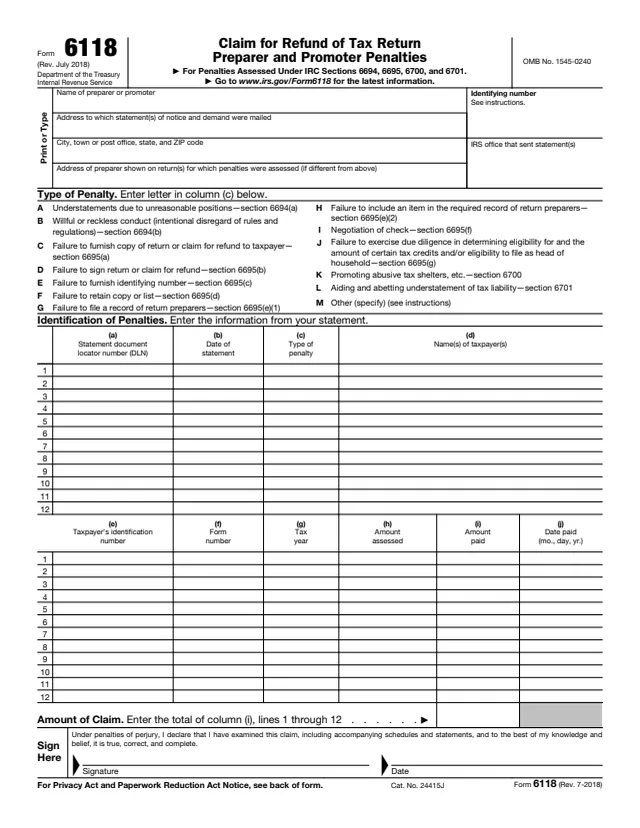
Form 6118, Claim for Refund of Tax Return Preparer and Promoter Penalties, covers penalties assessed under IRC sections 6694, 6695, 6700 and 6701. The IRS says tax return preparers and promoters file this form to claim a refund of preparer or promoter penalties they paid but believe were incorrectly charged.
The first page identifies the preparer or promoter, lists up to 12 penalties from the IRS statements of notice and demand, and totals the amount of the claim. The back of the form holds the instructions and a space for the reasons for claiming a refund, with each penalty identified by its line number.
The form says that for tax years beginning after 2017, the section 6695(g) penalty (type J) was expanded to include failure to exercise due diligence in determining eligibility to file as head of household. You can fill out Form 6118 free in your browser on this page and download it without an account.
Name, identifying number, the address the statements of notice and demand were mailed to, the IRS office that sent them, and the preparer's address on the returns if different.
Thirteen letters, from A (understatements due to unreasonable positions, section 6694(a)) through the section 6695 penalties to K and L (sections 6700 and 6701) and M for other penalties.
For each of up to 12 lines: the statement document locator number (DLN), date of statement, penalty letter and the names of the taxpayers.
The taxpayer's identification number, form number, tax year, amount assessed, amount paid and date paid, then the total of column (i) as the amount of the claim.
Page 2 holds the instructions and a space to explain the reasons for each penalty claimed. Extra sheets carry the name and identifying number.
Enter the preparer or promoter's name and identifying number (SSN or EIN as the instructions describe), the address where the statements were mailed and the IRS office that sent them.
Copy the DLN and date from each statement, enter the penalty letter in column (c) and the taxpayer names. For item M, the form says to enter the name of the penalty and its IRC section.
Enter the taxpayer's identification number, form number, tax year, amount assessed, amount paid and date paid. The form says only columns (b), (c) and (g) to (j) are needed for sections 6700 and 6701.
Total column (i) for lines 1 to 12. On page 2, explain the reasons for each penalty, identified by line number. The form says a copy of the penalty statements may be attached.
Sign and date under penalties of perjury in the Sign Here area at the bottom of page 1.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to file Form 6118 with the IRS service center or IRS office that sent the statement(s).
The form says claims under sections 6700 and 6701 are filed within 2 years, and claims under sections 6694 and 6695 within 3 years, from the date the penalty was paid in full.
The form says a person assessed a penalty under section 6700, 6701 or 6694 may file a claim upon paying 15% of the penalty if done within 30 days from the date of notice and demand.
The form says G and H can be combined when billed on the same statement, and C, D, E and F when imposed by the same IRS office or service center, with each statement's penalties grouped together.
The form says penalties from different IRS offices cannot be combined, and A, B, I, J, K, L and M each take a separate Form 6118, even for two or more of the same type.
The form is filed by the tax return preparer or promoter who paid the penalty, not by the taxpayers whose returns are listed on it.
No tool matches that search.
The form says it is for penalties assessed under IRC sections 6694, 6695, 6700 and 6701, listed as types A to L, plus M for other penalties named by the filer.
Only some. The form says G and H can be combined if billed on the same statement, and C, D, E and F if imposed by the same IRS office or service center. Penalties A, B, I, J, K, L and M each take a separate form.
To the IRS service center or IRS office that sent the statement(s) of notice and demand, the form says.
The form says 2 years from full payment for sections 6700 and 6701, and 3 years from full payment for sections 6694 and 6695. A claim can also follow payment of 15% of a section 6700, 6701 or 6694 penalty within 30 days of notice and demand.
Yes. The form asks for the reasons for claiming a refund for each penalty listed, identified by line number, in the space on page 2 or on attached sheets.
The form says a self-employed preparer or promoter, or one employed by another, enters a social security number. An employer of other preparers or promoters enters its employer identification number.