Reason checkboxes
One box at the top for the reason for filing, grouped under Tax, Penalty, Interest and Other, with an Other (specify) line.
843
Claim for Refund and Request for Abatement
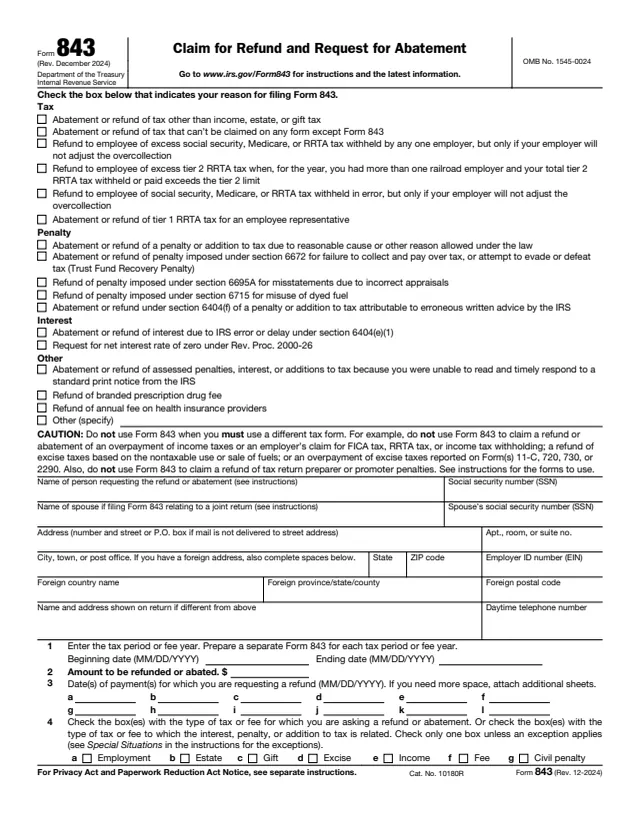
Form 843 is the Claim for Refund and Request for Abatement. The IRS says it is used to claim a refund or request an abatement of certain taxes, interest, penalties, fees, and additions to tax. The form opens with a list of reasons, such as an employee's refund of excess social security, Medicare, or RRTA tax when the employer will not adjust the overcollection, penalty relief for reasonable cause, or abatement of interest due to IRS error or delay.
Form 843 is not for every refund. The form's caution says not to use it for an overpayment of income taxes, an employer's claim for FICA tax, RRTA tax, or income tax withholding, certain excise tax refunds, or tax return preparer or promoter penalties. The instructions point to forms such as Form 1040-X, Form 941-X, Form 8849 and Form 6118 for those cases.
This page hosts the December 2024 revision. You can fill out Form 843 free in your browser on this page and download the result without an account.
One box at the top for the reason for filing, grouped under Tax, Penalty, Interest and Other, with an Other (specify) line.
Name and SSN, a spouse's name and SSN for a joint return, address, EIN, foreign address spaces, the name and address on the return if different, and a daytime phone number.
The tax period or fee year, the amount to be refunded or abated, and the dates of payments for which a refund is requested.
The type of tax or fee, such as employment, estate, gift, excise, income, fee or civil penalty, and the return or fee it relates to, such as Form 706, 941, 1040 or 1120.
The Internal Revenue Code section for a penalty, and the reason: IRS errors or delays, erroneous written advice, reasonable cause, or none of these.
An explanation of why the claim should be allowed and how the line 2 amount was computed, then signatures, Identity Protection PIN boxes and the paid preparer area.
Check one box at the top. The instructions say not to check more than one, and to use Other (specify) only when no listed reason fits and no other form is required.
Enter the name and SSN or ITIN of the person requesting the refund or abatement, and the spouse's from a related joint return. An entity enters its EIN.
Enter the tax period, the dollar amount and the date of each payment. The form says to prepare a separate Form 843 for each tax period or fee year.
Check the type of tax or fee and the related return, generally one box each. For a penalty, enter the Code section, which the instructions say is generally on the Notice of Assessment.
Check the reason on line 7, or box d if a, b and c do not apply. On line 8, explain the reasons in detail, show the computation and attach supporting evidence.
Sign and date. Both spouses sign for a joint return claim. If the IRS sent an Identity Protection PIN, enter it in the box beside the signature.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say a Form 843 filed in response to an IRS notice about certain taxes or fees goes to the return address from which the notice was sent.
A claim for refund in a Form 706 or 709 matter goes to Internal Revenue Service, Attn: E&G, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915.
For penalties or other reasons not listed separately, the instructions say to use the service center where a current year return for that tax would be filed. Net interest rate of zero requests go to the service center of the most recent return.
The instructions say a claim for credit or refund is generally filed within 3 years from the date the original return was filed or 2 years from the date the tax was paid, whichever is later.
Generally, a separate Form 843 is filed for each tax period or fee year or type of tax or fee, with exceptions described under Special Situations in the instructions.
The instructions say that after an IRS notice about a change, interest, a penalty, or an addition to tax, the notice instructions apply, and Form 843 may not be needed.
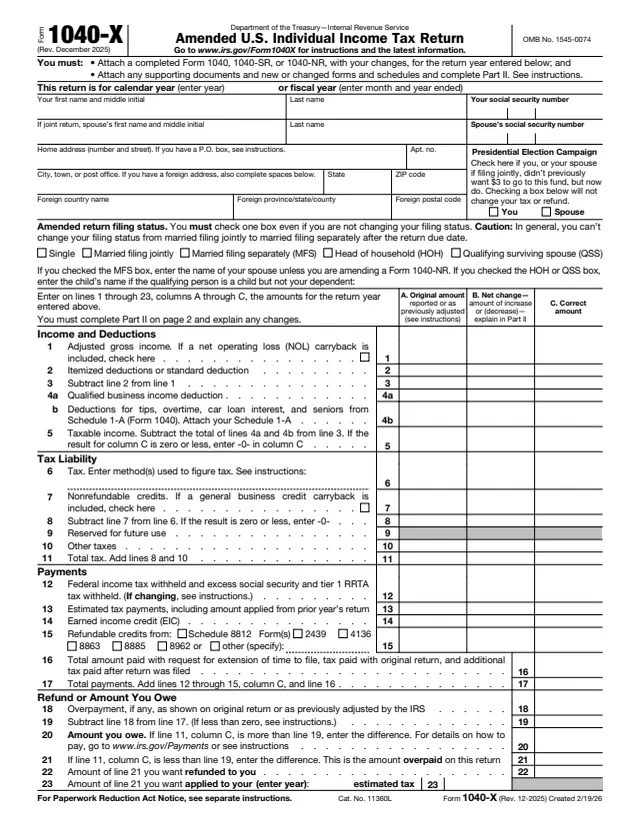
1040-X
166 fields, 2 pages
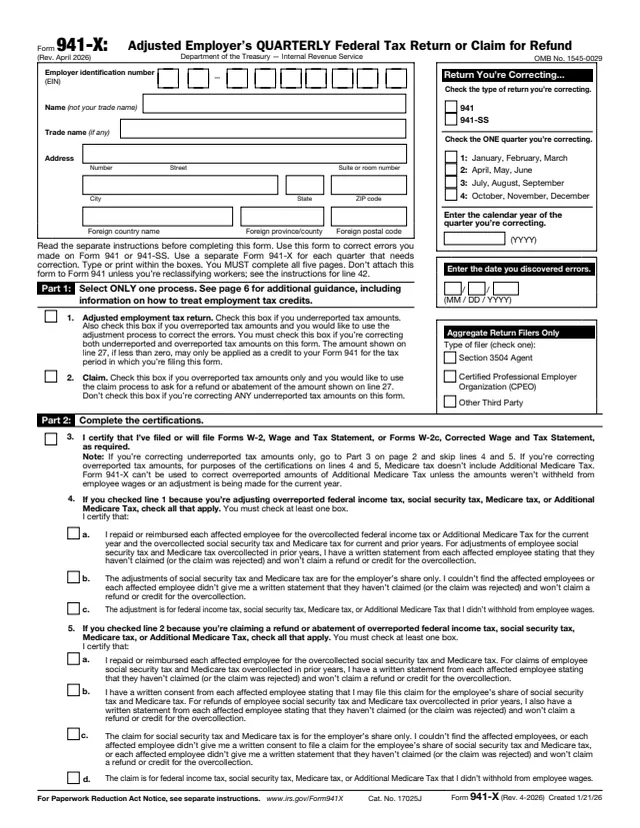
941-X
352 fields, 6 pages
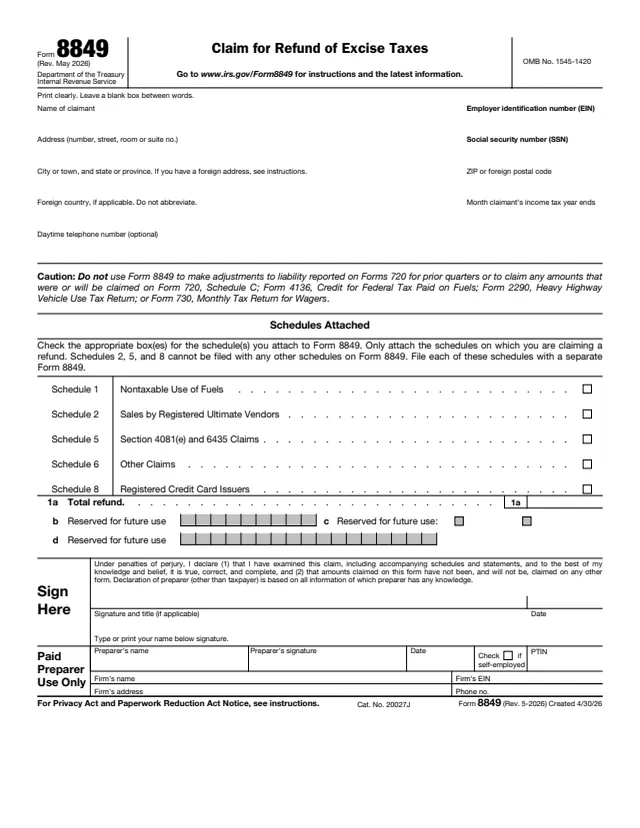
8849
27 fields, 4 pages
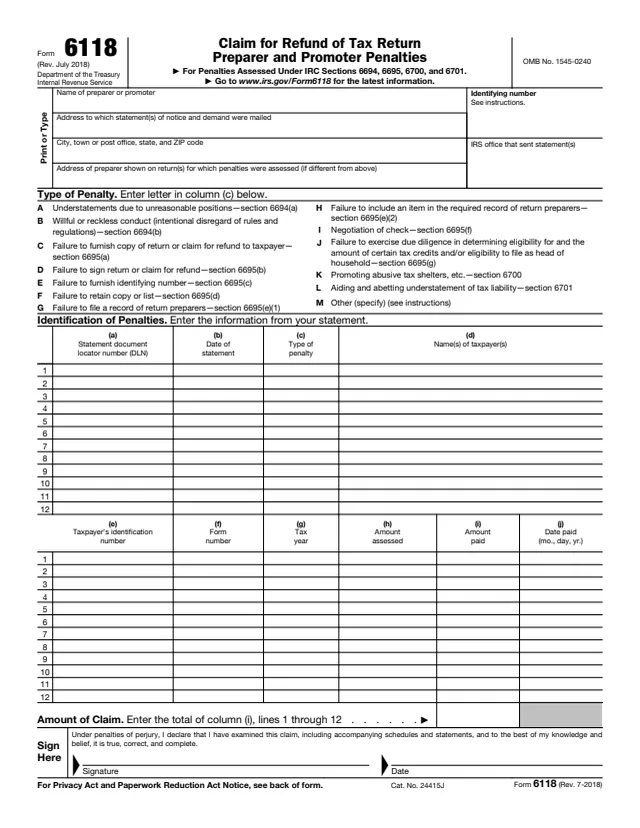
6118
129 fields, 2 pages

2848
92 fields, 2 pages
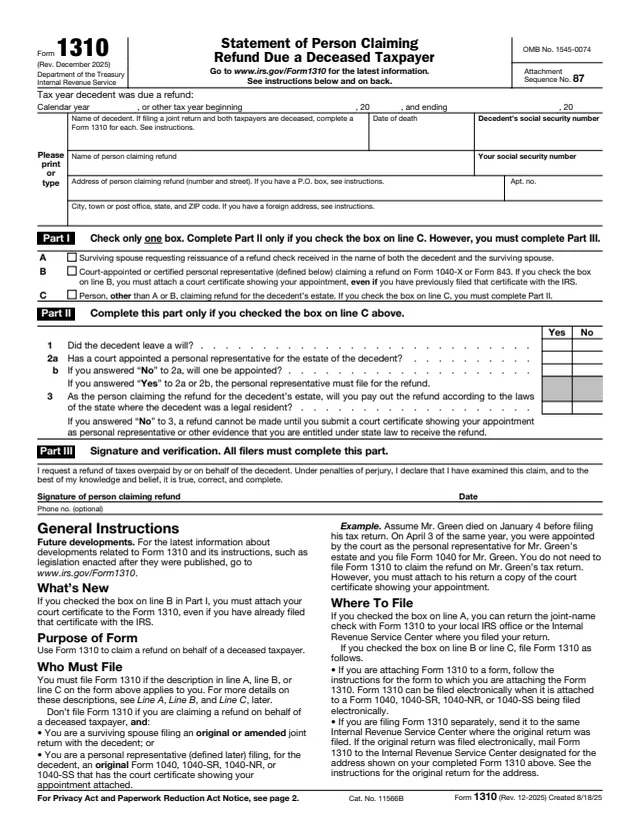
1310
25 fields, 2 pages
The person requesting the refund or abatement files it, or an authorized representative files it for them. The filer can be an individual, spouses on a joint return, a corporation, an estate or a trust.
No tool matches that search.
The IRS says it is used to claim a refund or request an abatement of certain taxes, interest, penalties, fees, and additions to tax. The reasons are listed as checkboxes at the top of the form.
No. The instructions say not to use Form 843 to request a refund of income tax or to amend an income tax return. Form 1040-X is used to change amounts reported on Form 1040.
The instructions say employers cannot use it for FICA tax, RRTA tax or income tax withholding, and use the correcting form for the return they filed, such as Form 941-X.
Yes. One checkbox covers abatement or refund of a penalty or addition to tax due to reasonable cause or other reason allowed under the law. Line 6 asks for the Code section and line 7, box c, covers reasonable cause.
The instructions say a claim for credit or refund is generally filed within 3 years from the date the original return was filed or 2 years from the date the tax was paid, whichever is later.
Yes. The instructions say an authorized representative can file it with Form 2848 attached, and a paid preparer who files it signs and completes the preparer area.
Yes. The form says both spouses sign when the refund or abatement relates to a joint return.