Header and benefit boxes
Taxpayer name and TIN, preparer name and PTIN, and four boxes for the benefits claimed: EIC, CTC/ACTC/ODC, AOTC and HOH.
8867
Paid Preparer's Due Diligence Checklist
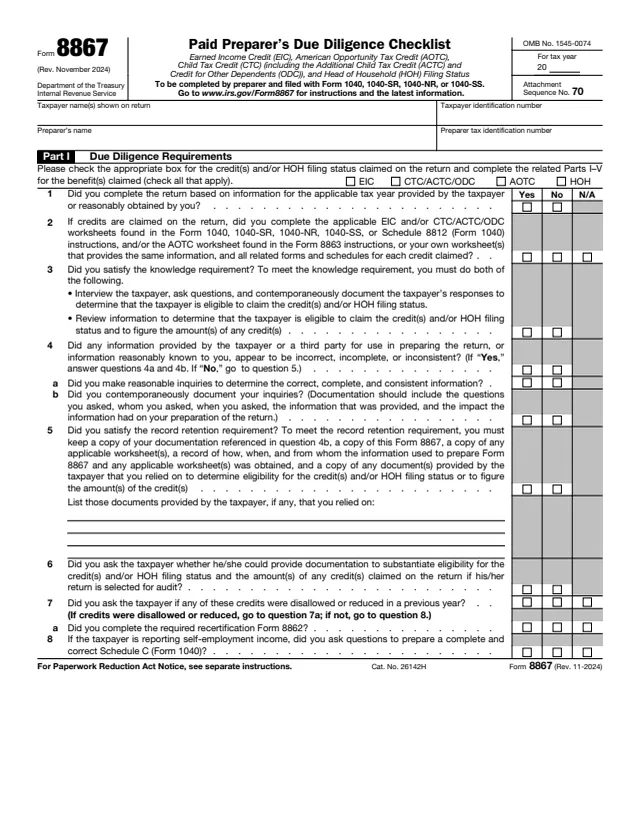
Form 8867 is a checklist completed by a paid tax return preparer, not by the taxpayer. The IRS says paid preparers of federal income tax returns or claims involving the earned income credit (EIC), child tax credit (CTC) and additional child tax credit (ACTC), credit for other dependents (ODC), American opportunity tax credit (AOTC) and head of household (HOH) filing status have due diligence requirements for deciding eligibility and the amount of each benefit.
The form says it is completed by the preparer and filed with Form 1040, 1040-SR, 1040-NR, or 1040-SS. The instructions say only paid tax return preparers should complete it, and it is filed with the taxpayer's return or amended return that claims one of these benefits.
The questions ask whether the preparer interviewed the taxpayer, documented the answers, completed the credit worksheets and kept the required records. A preparer can fill out Form 8867 free in the browser on this page and download the result without an account.
Taxpayer name and TIN, preparer name and PTIN, and four boxes for the benefits claimed: EIC, CTC/ACTC/ODC, AOTC and HOH.
Questions 1 to 8 cover tax year information, the credit worksheets, the knowledge requirement, reasonable inquiries, record retention, audit documentation, prior disallowance with Form 8862, and Schedule C income.
Questions 9a to 9c ask about eligibility for the number of qualifying children, whether the child lived with the taxpayer over half the year, and the tiebreaker rules.
Questions 10 to 12 cover citizenship or residency of each qualifying person, the over half the year rule, and the rules for children of divorced or separated parents, including Form 8332.
Question 13 asks whether the taxpayer gave substantiation such as Form 1098-T or receipts. Question 14 asks about marital status and keeping up a home for a qualifying person.
Lists the four steps that meet the due diligence requirements and the five records to keep, then question 15 asks the preparer to certify the answers are true, correct and complete.
Enter the taxpayer's name as it appears on the return and the TIN (the primary TIN on a joint return). Enter the name and PTIN of the preparer who decided eligibility, even if that preparer does not sign the return.
Check every box for a benefit claimed on the return. The instructions say to check all benefits for which the preparer determined the taxpayer is eligible.
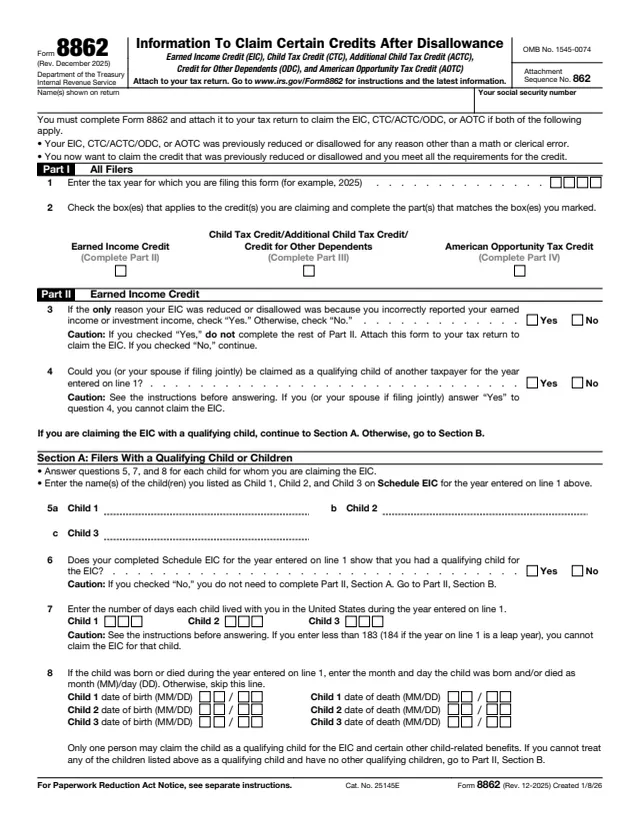
Answer Yes, No or N/A for each benefit. List any taxpayer documents relied on under question 5. If a credit was disallowed or reduced before, question 7a asks about Form 8862.
Complete only the parts for the benefits claimed. Each part says where to go next when the return does not claim that benefit.
Read the certification items and answer question 15, which asks whether all answers are true, correct and complete to the best of the preparer's knowledge.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
A signing preparer who e-files sends it electronically with the return. One who mails the return for the taxpayer mails it with the return. Otherwise the preparer gives it to the taxpayer to file with the return.
For a paper return, all Forms 8867 are attached. The instructions say e-file accepts transmission of up to four Forms 8867 for one return.
The form lists five records, including a copy of Form 8867, the worksheets and the taxpayer documents relied on. The instructions say to keep them for 3 years from the latest of the dates they list.
The instructions give an example of $650 for each failure, or $2,600 for all four benefits, for a return filed in 2026. They say the amount is adjusted for inflation each year.
8862
109 fields, 3 pages

1040
199 fields, 2 pages
1040
41 fields, 2 pages
8863
77 fields, 2 pages
8332
11 fields, 2 pages
1040
105 fields, 2 pages
The instructions say only paid tax return preparers should complete this form. The taxpayer does not fill it out.
No tool matches that search.
No. The instructions say only paid tax return preparers should complete this form. The taxpayer's name and TIN appear at the top.
The instructions say it is filed with a return or amended return claiming the EIC, the CTC/ACTC/ODC, the AOTC or head of household filing status that a paid preparer prepared.
Yes. Each paid preparer responsible for a claimed benefit completes one. The instructions say e-file accepts up to four for one return.
The instructions say 3 years from the latest of the return's due date, the filing date, the date it was presented for signature, or the date a nonsigning preparer handed over their part.
The instructions give $650 for each failure for a return filed in 2026, adjusted for inflation each year, with the current amount posted on IRS.gov/Form8867.