Filer and line 1
The name shown on Form 941 or other employment tax return, EIN, trade name and address, and on line 1 the client organization when a third-party payer files.
5884-D
Employee Retention Credit for Certain Tax-Exempt Organizations Affected by Qualified Disasters
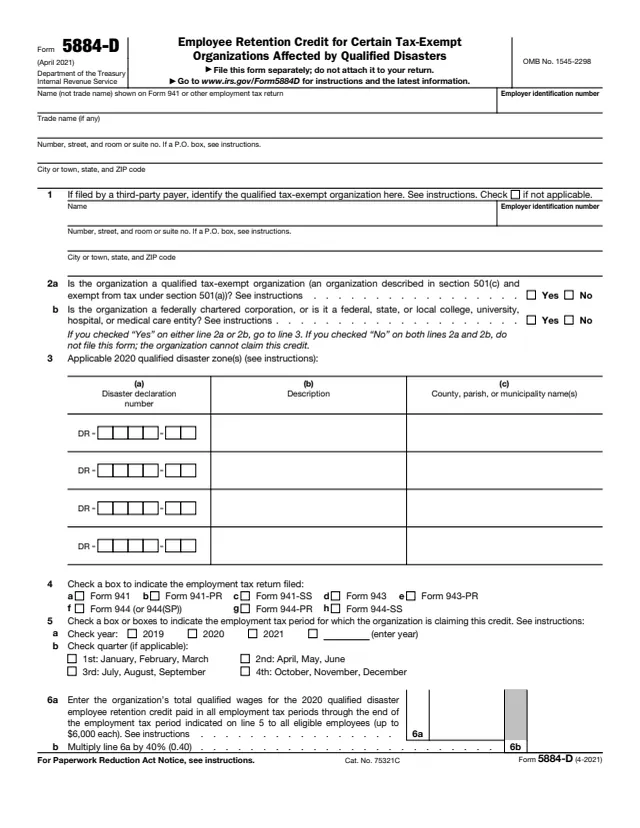
Form 5884-D is the form qualified tax-exempt organizations use to claim the employee retention credit for employers affected by qualified disasters. The instructions say an organization, including certain governmental entities, that continued to pay or incur wages after its activities became inoperable because of damage from a qualified disaster may be able to use it to claim the 2020 qualified disaster employee retention credit against certain payroll taxes.
The instructions compare it to the credit businesses claim against income taxes on Form 5884-A. The credit is equal to 40% of up to $6,000 of qualified wages paid to or incurred for each eligible employee, and is claimed against the employer portion of social security tax on wages paid to all employees during an employment tax period. The form is filed separately, after the employment tax return for the period, and the IRS refunds the amount on line 12.
This page hosts the April 2021 edition. The instructions end with a list of the 2020 qualified disaster zones and their DR numbers. You can fill out the PDF free in your browser on this page and download it without an account.
The name shown on Form 941 or other employment tax return, EIN, trade name and address, and on line 1 the client organization when a third-party payer files.
Yes or No questions on qualified tax-exempt status and governmental entities, and a table of disaster declaration numbers, descriptions and county, parish or municipality names.
The employment tax return filed, such as Form 941, 943 or 944, and the year and quarter of the period claimed.
Total qualified wages up to $6,000 each, times 40% (0.40), the number of eligible employees, and credits claimed on earlier Forms 5884-D.
Taxable social security wages and tips times 6.2% (0.062), less Form 5884-C credits and the research payroll tax credit, then the refund on line 12 or the amount owed on line 13.
The officer's signature, title, date and daytime phone number, and the Paid Preparer Use Only section.
Enter the filer's details. A third-party payer enters its own name and EIN at the top and the client organization on line 1. Others check the box showing line 1 is not applicable.
Answer lines 2a and 2b. On line 3 enter the DR number, a brief description and the local jurisdiction of each disaster. With more than four, the instructions say to enter "See attached" in column (b) of the fourth row and attach a list.
Check the return and period, then enter total qualified wages paid through the end of that period, up to $6,000 per eligible employee, and multiply by 40% (0.40).
Enter the number of eligible employees and prior credits, then the taxable social security wages and tips from the return, such as Form 941 lines 5a and 5b column 1, and the reductions on lines 11b and 11c.
Enter the smaller of line 9 or line 11d on line 12, or the amount owed on line 13 if line 8 is greater than line 6b. An authorized officer signs and the form is mailed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to send Form 5884-D to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201. It is filed separately and not attached to a return.
After the employment tax return for the period claimed, starting with the first period in which qualified wages were paid, and for each later period in which the cumulative credit changes.
The instructions say it is filed within 2 years from the date the tax reported on the employment tax return was paid, or 3 years from the date the employment tax return was filed, whichever is later.
The instructions say the IRS cannot process it until the original employment tax return for the same period has been processed, and to allow 8 to 12 weeks.
The instructions say the organization may reduce its required deposits for a period by the anticipated credit, and that a resulting system-generated balance due notice will be abated when the credit is applied.
The instructions say that for 2019 qualified wages can be only in the 4th calendar quarter, and for 2021 only in the 1st and 2nd calendar quarters.
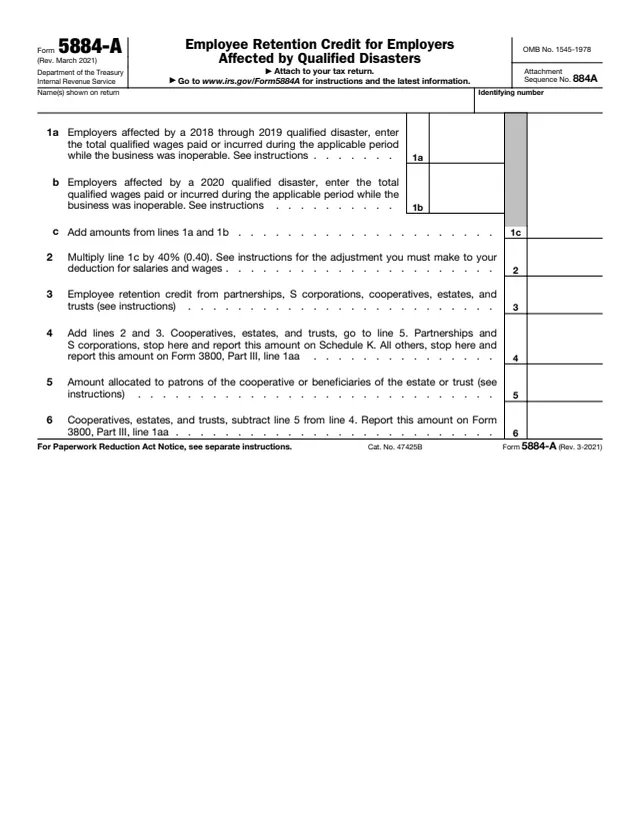
5884-A
10 fields, 1 page
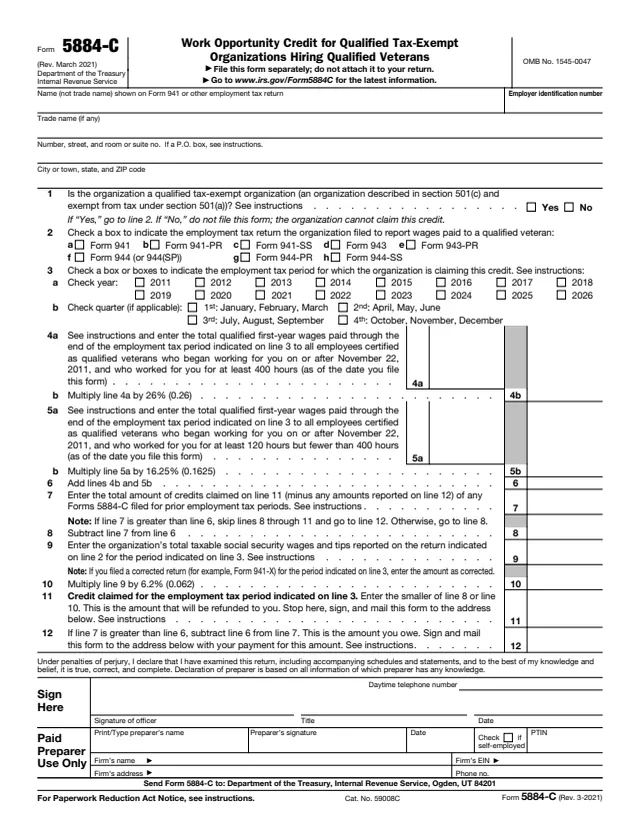
5884-C
55 fields, 4 pages
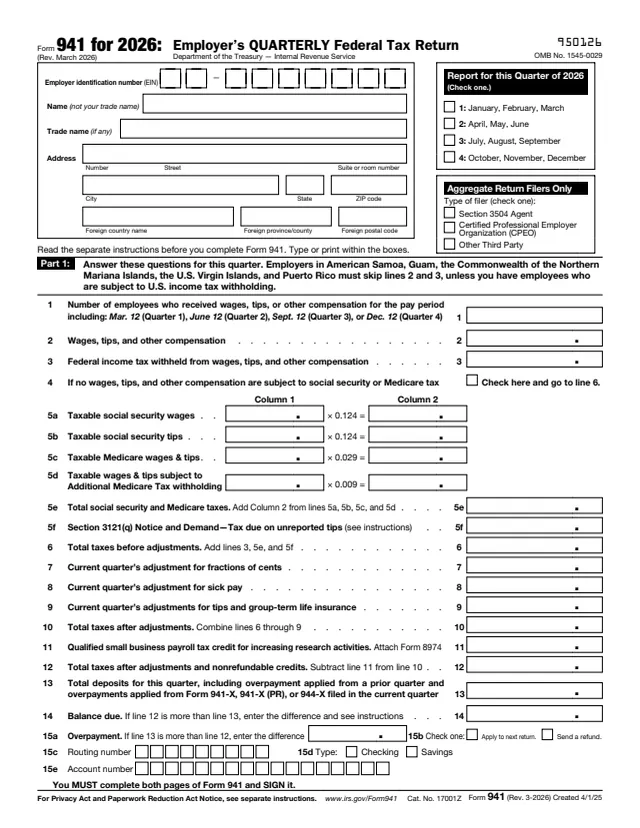
941
116 fields, 3 pages
941-X
352 fields, 6 pages
943
109 fields, 3 pages
944
114 fields, 3 pages
The filer is a tax-exempt employer or a third-party payer filing for one, not an individual. The form says that if both lines 2a and 2b are No, the organization does not file this form and cannot claim this credit.
No tool matches that search.
The instructions say Form 5884-D claims the 2020 qualified disaster employee retention credit against certain payroll taxes, similar to the credit businesses claim against income taxes on Form 5884-A.
The instructions say it is equal to 40% of up to $6,000 of qualified wages paid to or incurred for each eligible employee.
No. The form says to file it separately and not attach it to the return.
The instructions say a third-party payer that files an aggregate employment tax return files a single separate Form 5884-D for each client organization per period, naming the organization on line 1.
The instructions say to allow 8 to 12 weeks, and that it cannot be processed until the original employment tax return for the same period has been processed.
At the end of the instructions, under 2020 Qualified Disaster Zones, with each disaster's DR number, incident period and the counties, parishes or municipalities in the zone.