Organization details
Name shown on Form 941 or other employment tax return, employer identification number, trade name and address.
5884-C
Work Opportunity Credit for Qualified Tax-Exempt Organizations Hiring Qualified Veterans
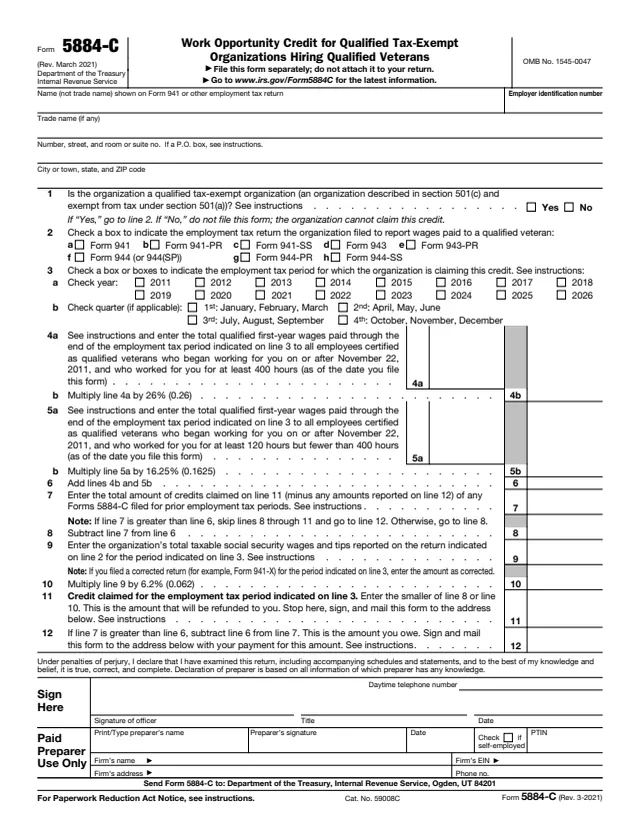
Form 5884-C is the form qualified tax-exempt organizations use to claim the work opportunity credit for qualified first-year wages paid to qualified veterans. The form defines a qualified tax-exempt organization as an organization described in section 501(c) and exempt from tax under section 501(a).
The instructions say the credit is claimed against the employer portion of social security tax on wages paid to all employees during the 1-year period beginning on the day a qualified veteran begins working for the organization, and does not apply to the employer portion of Medicare tax. Each veteran is certified by the state workforce agency (SWA). The organization files Form 5884-C separately, after its employment tax return for the period, and the IRS refunds the amount on line 11.
This page hosts the March 2021 revision, which describes veterans who begin working on or after November 22, 2011, and before January 1, 2026. The instructions are printed on pages 2 to 4 of the form. You can fill out the PDF free in your browser on this page and download it without an account.
Name shown on Form 941 or other employment tax return, employer identification number, trade name and address.
Whether the organization is a qualified tax-exempt organization, the employment tax return filed, and the year and quarter of the period claimed.
Qualified first-year wages for veterans who worked at least 400 hours, times 26% (0.26), and for those who worked at least 120 hours but fewer than 400 hours, times 16.25% (0.1625).
The cumulative credit, credits claimed on earlier Forms 5884-C, taxable social security wages and tips for the period, and that amount times 6.2% (0.062).
The credit claimed for the period, which the form says will be refunded, or the amount owed when prior claims exceed the cumulative credit.
The officer's signature, title, date and daytime phone number, and the Paid Preparer Use Only section.
Answer the qualified tax-exempt organization question, check the employment tax return filed, and check the year (and quarter, if applicable) for the period claimed.
Enter qualified first-year wages by hours worked as of the filing date. The form caps them at $6,000, $12,000, $14,000 or $24,000 per veteran, depending on the certification.
Add lines 4b and 5b, then subtract credits claimed on line 11 of earlier Forms 5884-C, minus amounts reported on line 12.
Enter total taxable social security wages and tips from the employment tax return for the period, such as Form 941 lines 5a and 5b column 1, and multiply by 6.2% (0.062).
Enter the smaller of line 8 or line 10 on line 11. If line 7 is greater than line 6, line 12 shows the amount owed instead.
An authorized officer signs and dates the form, and it is mailed to the address printed at the bottom of page 1.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to send Form 5884-C to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201. It is filed separately and not attached to a return.
After the organization files its employment tax return for the period claimed, for each employment tax period in which it paid qualified first-year wages to a qualified veteran. The form says generally no more than one Form 5884-C per period.
The form says it is filed within 2 years from the date the tax reported on the employment tax return was paid, or 3 years from the date the employment tax return was filed, whichever is later.
The form says the IRS cannot process it until the original employment tax return for the same period has been processed, and to allow 8 to 12 weeks.
The form says the credit does not affect the tax liability on the employment tax return, so the organization should not reduce its required deposits in anticipation of the credit.
The form lists EFTPS as the preferred method, plus credit or debit card, or a check or money order payable to "United States Treasury" showing the EIN, "Form 5884-C" and the year and quarter.
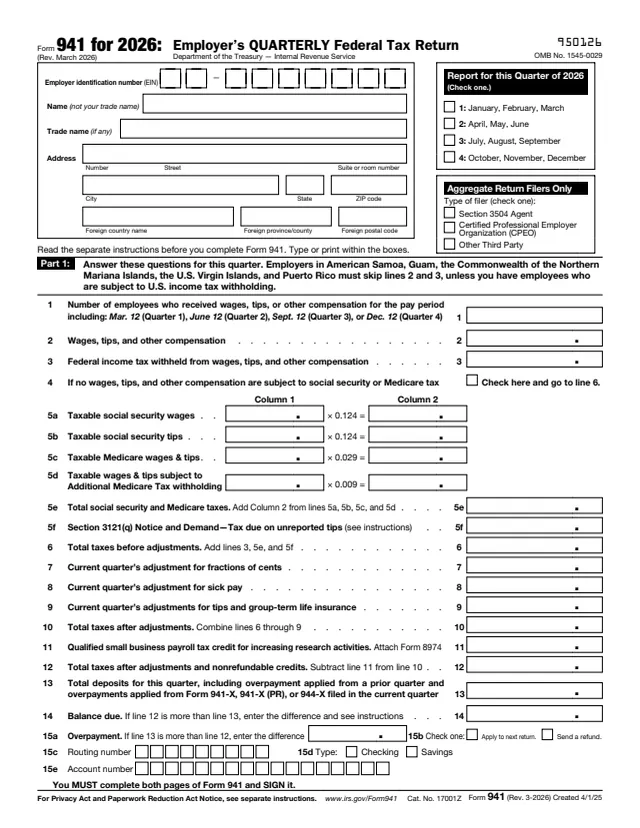
941
116 fields, 3 pages
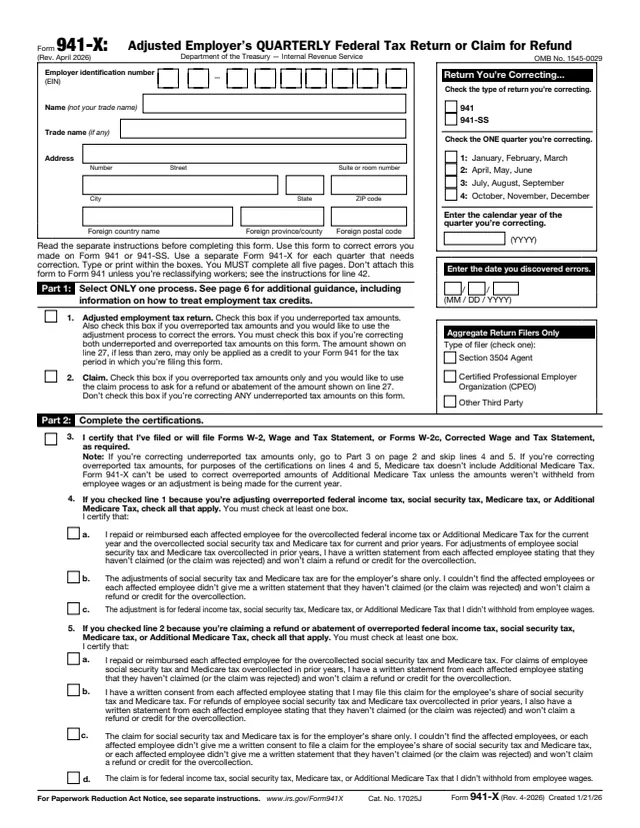
941-X
352 fields, 6 pages
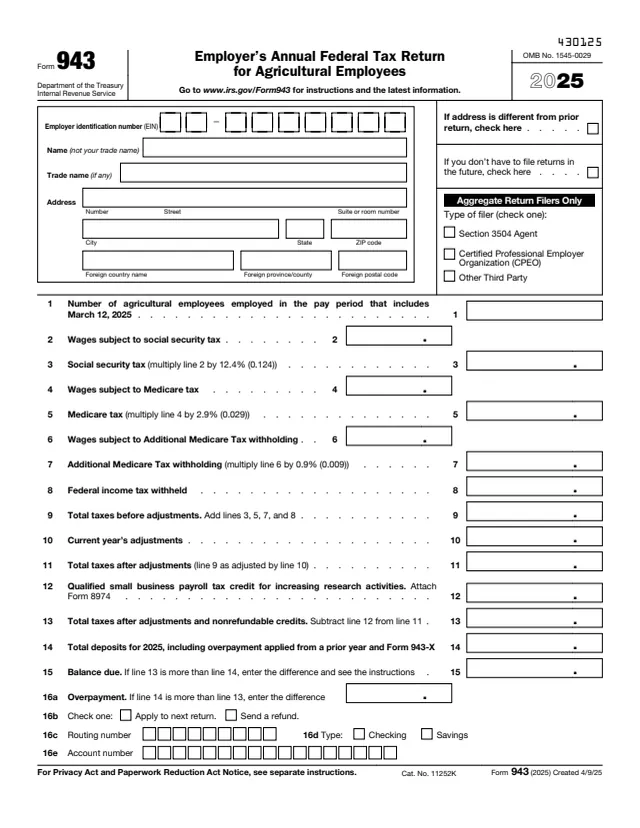
943
109 fields, 3 pages
944
114 fields, 3 pages
5884-D
68 fields, 2 pages
8655
42 fields, 3 pages
The filer is a tax-exempt employer, not the veteran. The form says that if the answer on line 1 is No, the organization does not file this form and cannot claim this credit.
No tool matches that search.
A qualified tax-exempt organization, which the form defines as an organization described in section 501(c) and exempt from tax under section 501(a).
No. The form says to file it separately and not attach it to the return.
The form says the credit is claimed against the employer portion of social security tax and does not apply to the employer portion of Medicare tax.
The form says to allow 8 to 12 weeks, and that it cannot be processed until the original employment tax return for the same period has been processed.
The form says the organization asks for and is issued a certification for each qualified veteran from the state workforce agency, received by the day the individual begins work or requested with Form 8850.
The form says the IRS will send a refund or apply it only if the organization asks in writing.