5471 Sch. E

Income, War Profits, and Excess Profits Taxes Paid or Accrued

Agency
IRS
Revision
Rev. December 2021
Fillable fields
400
Pages
3
Official source
IRS form page
Checked
October 21, 2026
Fill 5471 Sch. E online
Page 1 of form 5471 Sch. E

Schedule E (Form 5471): Income, War Profits, and Excess Profits Taxes Paid or Accrued

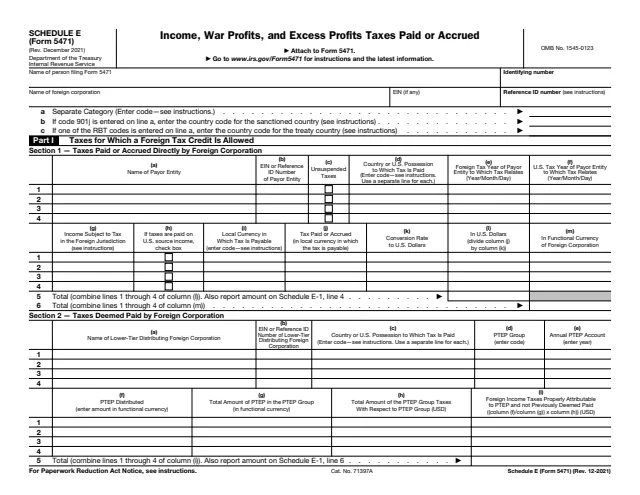
Schedule E (Form 5471) is the separate schedule for income, war profits, and excess profits taxes paid or accrued by a foreign corporation. The Instructions for Form 5471 say to use Part I to report taxes paid, accrued, or deemed paid under section 960(b)(2) by a foreign corporation for which a foreign tax credit is allowed, and Part III to report taxes for which a credit may not be taken. Schedule E-1, on pages 2 and 3, reports the cumulative balance of foreign income taxes paid or accrued by a CFC by separate category of income.

It is not a stand-alone return. The schedule says to attach it to Form 5471, which the About page says certain U.S. citizens and residents who are officers, directors, or shareholders in certain foreign corporations file. The instructions say Schedule E is completed even for noncorporate U.S. shareholders, with a separate Schedule E for each applicable separate category of income.

This page hosts the December 2021 revision. You can fill it out free in your browser on this page and download the result without an account.

What's on Schedule E (Form 5471)

Header and lines a to c

Filer and foreign corporation names, identifying number, EIN and reference ID number. Line a takes the separate category code, line b a sanctioned country code when code 901j is used, and line c a treaty country code for an RBT code.

Part I, Section 1: taxes paid or accrued

Columns (a) to (m) for each tax: payor entity, EIN or reference ID, unsuspended taxes box, country, foreign and U.S. tax years, income subject to tax, U.S. source box, currency code, tax in local currency, conversion rate, U.S. dollars and functional currency.

Part I, Section 2: taxes deemed paid

Lower-tier distributing foreign corporations, with country code, PTEP group, annual PTEP account, PTEP distributed, total PTEP in the group, the group's taxes in U.S. dollars and the taxes attributable to the distribution.

Part II: election

For tax years beginning after December 31, 2004, whether an election has been made under section 986(a)(1)(D) to translate taxes using the exchange rate on the date of payment, and the date of the election.

Part III: taxes with no credit

Taxes disallowed under section 901(j), 901(k) and (l), and 901(m), U.S. taxes, suspended taxes and other taxes, totaled in functional currency on line 3 and in U.S. dollars on line 4.

Schedule E-1

Pages 2 and 3, in U.S. dollars: lines 1a to 16 for taxes related to subpart F income, tested income and residual income, suspended taxes, and ten columns of taxes related to previously taxed E&P.

How to fill out Schedule E (Form 5471)

  1. 1

    One schedule per category

    Complete a separate Schedule E for each applicable separate category of income and enter its code on line a, using Categories of Income in the Instructions for Form 1118. With more than one category, the instructions say a further Schedule E (including E-1) with code TOTAL adds them up.

  2. 2

    Section 1, column (j)

    Enter the tax paid or accrued in the local currency in which it is payable, not the functional currency of the payor or foreign corporation. Taxes paid to more than one country on the same income go on separate lines.

  3. 3

    Columns (k) and (l)

    Translate column (j) into dollars at the average exchange rate for the tax year to which the tax relates, unless an exception applies. The rate uses the divide-by convention: units of foreign currency that equal one U.S. dollar, rounded to at least four places.

  4. 4

    Section 2

    Report a PTEP distribution from a lower-tier foreign corporation only if foreign income taxes are deemed paid under section 960(b) on it. Enter a PTEP group code, such as 959c1 or 951A, in column (d) and the annual PTEP account year in column (e).

  5. 5

    Part III

    Enter taxes for which no credit is allowed, such as taxes paid to the United States in column (f) and taxes suspended under section 909 in column (g). Line 4 translates line 3 to U.S. dollars, in general at the average exchange rate as defined in section 989(b)(3).

  6. 6

    Schedule E-1

    Start line 1a with the prior year line 16 balance. Line 4 takes Section 1, line 5, column (l), and line 6 takes Section 2, line 5, column (i). Enter negative amounts on line 15 of columns (a), (b) and (c) as needed so line 16 is zero, and attach a statement explaining why.

Why fill Form 5471 Sch. E on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, links to other schedules and penalties

Where it goes

Attach Schedule E to Form 5471. The instructions say to attach Form 5471 to the income tax return (or, if applicable, partnership or exempt organization return) and file both by the due date, including extensions.

Zero amounts

When a schedule is required but all amounts are zero, the instructions say it should still be filed with one or more zero amounts. For schedules completed by category, a single instance for any separate category meets the requirement.

Prior year adjustments

Adjustments to foreign income taxes for a prior year are reported in the year to which the taxes relate, not the year of adjustment. The instructions say this may require an amended return and cite section 905(c).

Links to Schedules C and H

Taxes on Schedule E may differ from income tax expense on line 21a of Schedule C. Section 1, line 6, and Part III, line 3, together are the reduction to current year E&P for income taxes; see Schedule H, line 2g.

Penalties

The instructions list a $10,000 penalty for each annual accounting period of each foreign corporation for failure to furnish the information required by section 6038(a) within the time prescribed, and a reduction of 10% of the foreign taxes available for credit under sections 901 and 960.

Recent development

The About Form 5471 page lists new foreign tax allocation reporting in the Schedule E instructions, dated SEP-14-2026. The instructions now ask for a statement on taxes allocated under guidance issued under section 70352(c)(1)(C) of the OBBBA.

Who needs to fill out Schedule E (Form 5471)?

  • Category 1, 4 and 5 filers

    The filing chart in the Form 5471 instructions marks separate Schedule E for Category 1 filers (U.S. shareholders of a section 965 specified foreign corporation), Category 4 filers (U.S. persons who had control of a foreign corporation) and Category 5 filers (U.S. shareholders of a CFC).

  • Unrelated section 958(a) U.S. shareholders

    A chart footnote says Schedules E and E-1 are required for these filers only if they claim deemed paid foreign income taxes of the foreign-controlled section 965 SFC or foreign-controlled CFC under section 960.

  • Related constructive U.S. shareholders

    Another footnote says these filers only need to complete Schedule E and can leave Schedule E-1 blank. Both footnotes point to Rev. Proc. 2019-40.

  • Noncorporate U.S. shareholders

    The instructions say Schedule E is completed even for noncorporate U.S. shareholders, and that it is relevant for those who elect under section 962 to be taxed at corporate rates.

  • Consolidated groups

    In the case of a consolidated return, the instructions say to enter the name of the U.S. parent in the field for the name of the person filing Form 5471.

The U.S. person who files Form 5471 completes it for the foreign corporation, and it goes to the IRS attached to that Form 5471.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 5471 Sch. E

Who completes Schedule E (Form 5471)?

The U.S. person filing Form 5471. The filing chart in the instructions marks it for Category 1, 4 and 5 filers, with footnotes that limit it for some foreign-controlled corporations.

Is Schedule E filed by itself?

No. The schedule says to attach it to Form 5471, and Form 5471 is attached to the filer's income tax return.

How many Schedules E are needed?

One for each applicable separate category of income, plus one with code TOTAL when there is more than one category. The instructions say not to complete a separate Schedule E for the section 951A category.

Which currency goes in column (j)?

The local currency in which the tax is payable, not the functional currency of the payor or the foreign corporation.

What goes in Part III?

Taxes for which a foreign tax credit is not allowed. The instructions say that while not allowed as a credit, these taxes are taken into account in determining the foreign corporation's E&P.

Where are the instructions for Schedule E?

They are a section of the Instructions for Form 5471, linked from the About Form 5471 page on irs.gov. The schedule itself points to www.irs.gov/Form5471.