Lines 1 to 3: plan sponsor
The name of the plan sponsor (the employer if it is a single-employer plan), the employer identification number (EIN) and the plan number.
5309
Application for Determination of Employee Stock Ownership Plan
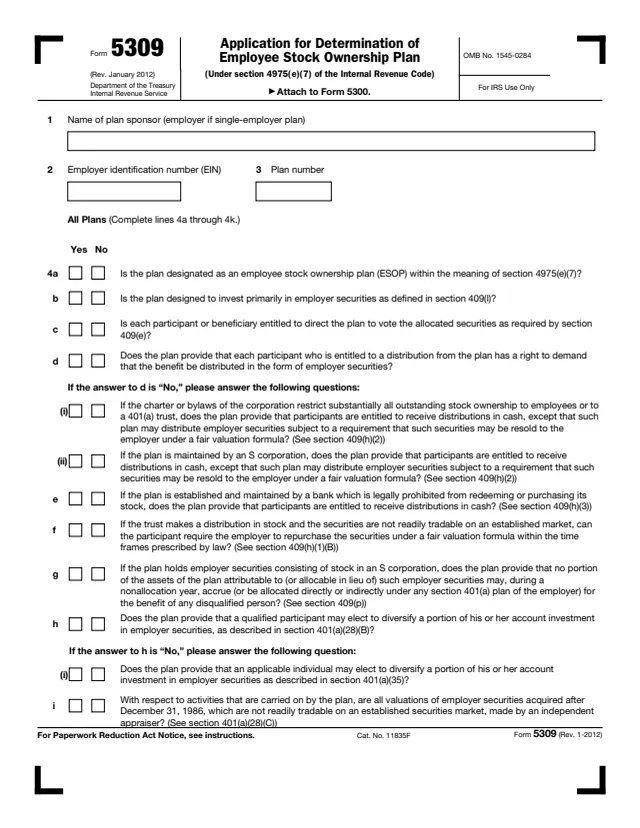
Form 5309, Application for Determination of Employee Stock Ownership Plan, is used to apply for a determination letter for an employee stock ownership plan (ESOP) that meets the requirements of Internal Revenue Code section 4975(e)(7). The form is not filed on its own: its header says "Attach to Form 5300," the Application for Determination for Employee Benefit Plan.
The instructions on page 3 say a corporate employer files it, either when it has established an ESOP intended to meet section 4975(e)(7) or when it amends one. The questions cover voting rights, distributions in employer securities, repurchase rights, diversification, valuations by an independent appraiser and, for leveraged ESOPs, the exempt loan rules. A principal officer authorized to sign signs it.
The current revision is January 2012, and the IRS page lists no recent developments. You can fill out the PDF free in your browser on this page and download it without an account.
The name of the plan sponsor (the employer if it is a single-employer plan), the employer identification number (EIN) and the plan number.
Yes or No questions on whether the plan is designated as an ESOP, invests primarily in employer securities under section 409(l), and passes voting rights through as section 409(e) requires.
The right to demand employer securities, the cash distribution exceptions for restricted corporations, S corporations and banks, and the repurchase right under section 409(h)(1)(B).
S corporation nonallocation years under section 409(p), diversification elections, independent appraisals, distribution timing under section 409(o) and section 1042 sales by C corporations.
Questions tied to Regulations sections 54.4975-7 and 54.4975-11: use of loan proceeds, the suspense account, collateral, lender rights, loan payments, forfeitures and nonterminable protections.
A declaration under penalties of perjury, the signature and date, and spaces to type or print the signer's name and title.
The instructions say written responses are not acceptable where a box is provided, data goes in Courier 10 point font, letters in all capitals, with spaces between words.
Enter the plan sponsor's name, its EIN and the plan number. The instructions say that if a number is requested, a number must be entered.
Every plan completes these lines by checking Yes or No. If 4d is No, answer 4d(i) and 4d(ii). If 4h is No, answer 4h(i) about section 401(a)(35).
Complete these only for a leveraged ESOP applying under section 4975(d)(3) and Regulations section 54.4975-7, again by checking Yes or No.
The principal officer authorized to sign signs and dates the form, then types or prints a name and title. The instructions say stamped signatures are not acceptable, citing Rev. Proc. 2012-4.
Attach the completed Form 5309 to Form 5300 and include a copy of all documents and statements required by those forms.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to submit Form 5309, Form 5300 and a copy of all documents and statements required by those forms, with Form 5309 attached to Form 5300.
The form is for a determination on whether a plan, initially or as a result of a plan amendment, meets the requirements of section 4975(e)(7). The form prints no separate deadline or mailing address.
The instructions say an S corporation ESOP must provide that no prohibited allocation of employer stock is made to a disqualified person for a nonallocation year, for plan years beginning on or after January 1, 2005.
The form lists recordkeeping 6 hr., 13 min.; learning about the law or the form 2 hr., 10 min.; and preparing and sending the form to the IRS 2 hr., 22 min.
The form says information about recent developments affecting Form 5309 is posted at www.irs.gov/form5309. The IRS page lists none at this time.
5310-A
51 fields, 5 pages
5308
30 fields, 2 pages
5330
304 fields, 6 pages
5500-EZ
78 fields, 2 pages
5306
68 fields, 3 pages
The form's Who May File section names corporate employers only. Plan participants and beneficiaries do not file it.
No tool matches that search.
No. The form says to attach it to Form 5300, Application for Determination for Employee Benefit Plan, together with the documents and statements those forms require.
The instructions list any corporate employer who has established an ESOP intended to meet section 4975(e)(7), and any corporate employer who amends such an ESOP.
No. The form says lines 5a through 5g are for plans applying under section 4975(d)(3) and Regulations section 54.4975-7, the leveraged ESOPs. All plans complete lines 4a through 4k.
The instructions say the principal officer authorized to sign. Stamped signatures are not acceptable, and the form points to Rev. Proc. 2012-4.
The tax credit ESOP questions were deleted from the form. The instructions say to state that the plan involves one in the cover letter and refer to Regulations section 1.46-8(d).
The Paperwork Reduction Act notice says filing this information is only required if the plan sponsor wishes the IRS to determine if the plan qualifies under section 4975(e)(7).