Header
The participant's name, date of birth and address, the account number, a box to check if this is a transfer SIMPLE IRA, a box to check if this is an amendment, and the custodian's name and address.
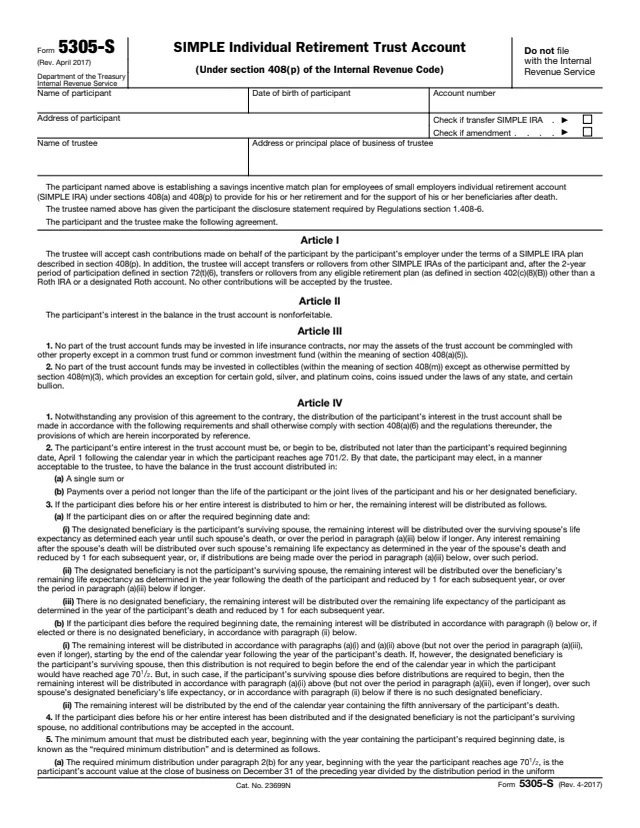
5305-S
SIMPLE Individual Retirement Trust Account
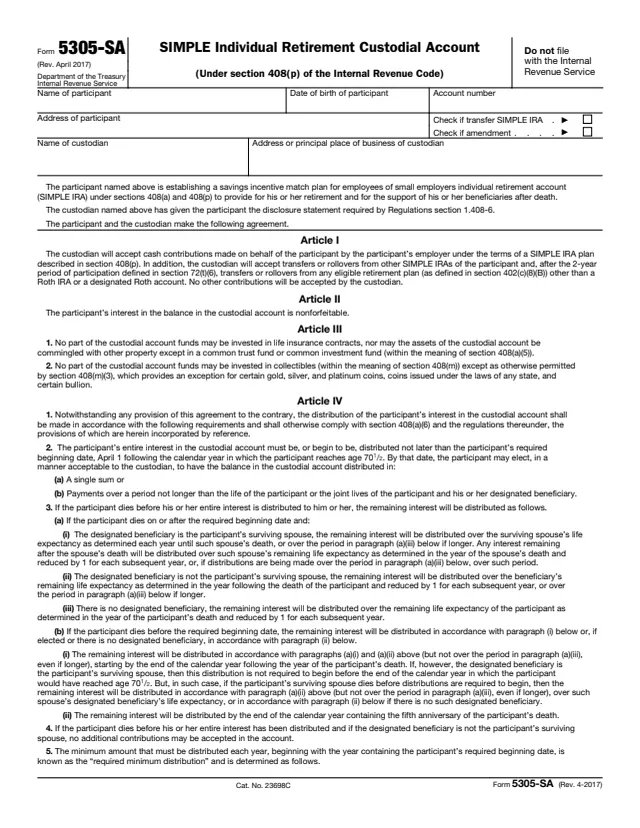
Form 5305-SA is a model custodial account agreement that, in the words of its instructions, meets the requirements of sections 408(a) and 408(p) of the Internal Revenue Code. It sets up a savings incentive match plan for employees of small employers individual retirement account (SIMPLE IRA). The instructions say the SIMPLE IRA is established after the form is fully executed by both the individual, called the participant, and the custodian.
Under Article I, the custodian accepts cash contributions made on behalf of the participant by the participant's employer under a SIMPLE IRA plan described in section 408(p), plus certain transfers and rollovers. The form says no other contributions will be accepted. Only Articles I through VII have been reviewed by the IRS, and Article VIII holds additional provisions.
The form is not filed with the IRS. Its heading says "Do not file with the Internal Revenue Service," and the instructions say to keep it with your records. This is the April 2017 revision. You can fill it out free in your browser on this page and download the result without an account.
The participant's name, date of birth and address, the account number, a box to check if this is a transfer SIMPLE IRA, a box to check if this is an amendment, and the custodian's name and address.
Employer cash contributions under a SIMPLE IRA plan, transfers or rollovers from other SIMPLE IRAs, and, after the 2-year period of participation in section 72(t)(6), from any eligible retirement plan other than a Roth IRA or a designated Roth account.
Article II says the participant's interest is nonforfeitable. Article III bars investing in life insurance contracts and in collectibles, except certain gold, silver and platinum coins, coins issued under state law and certain bullion.
When distributions have to start, the choice of a single sum or payments over life expectancy, what happens after the participant's death, and how the required minimum distribution is figured.
The participant provides the information needed for the reports. The custodian submits the reports prescribed by the IRS to the IRS and the participant, and gives the employer the summary description.
Controlling provisions, amendments and open space for additional provisions, then signature lines for the participant, the custodian and, only if a signature has to be witnessed, a witness.
Enter the participant's name, date of birth and address, and the account number at the top of page 1.
Check the transfer SIMPLE IRA box if the account is not the original recipient of contributions under any SIMPLE IRA plan. Check the amendment box only when this form amends an existing agreement.
Enter the custodian's name and address or principal place of business.
The instructions say distributions under this article may be made in a single sum, periodic payment, or a combination of both, and that the option should be reviewed in the year the participant reaches age 70½.
Add any agreed provisions, such as definitions, investment powers, voting rights, the custodian's fees or state law requirements, and attach pages if needed. If none, draw a line through the space.
The participant and the custodian sign and date page 2. Someone signing for the participant notes their relationship. The witness line is used only if a signature is required to be witnessed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Nowhere. The heading says "Do not file with the Internal Revenue Service," and the instructions say to keep the form with your records.
The custodian gives the employer the summary description in section 408(l)(2). The instructions say this requirement does not apply to a transfer SIMPLE IRA.
Article I accepts transfers or rollovers from eligible retirement plans other than SIMPLE IRAs only after the 2-year period of participation defined in section 72(t)(6), and not from a Roth IRA or a designated Roth account.
In this revision, Article IV puts the required beginning date at April 1 following the calendar year in which the participant reaches age 70½.
Provisions added in Article VIII have to comply with state law and the Internal Revenue Code, and the form says they may not imply that the IRS reviewed or pre-approved them.
The instructions point to Pub. 590-A, Pub. 590-B and Pub. 560 for more on SIMPLE IRAs, including the disclosures the custodian gives the participant.
5305-S
9 fields, 2 pages
5305-SIMPLE
32 fields, 6 pages
5304-SIMPLE
32 fields, 6 pages
5305-A
10 fields, 2 pages
5305
10 fields, 2 pages
5305-SEP
7 fields, 2 pages
The form is an agreement between the employee opening the SIMPLE IRA and the custodian that holds it. The employer funds the account under its SIMPLE IRA plan. Nobody sends the form to the IRS.
No tool matches that search.
No. The heading says "Do not file with the Internal Revenue Service," and the instructions say to keep the form with your records.
Article I says the custodian accepts cash contributions made on behalf of the participant by the participant's employer under a SIMPLE IRA plan, plus certain transfers and rollovers. No other contributions are accepted.
The instructions say it is a SIMPLE IRA that is not the original recipient of contributions under any SIMPLE IRA plan. The summary description requirements of section 408(l)(2) do not apply to it.
The instructions say only Articles I through VII have been reviewed by the IRS. Article VIII holds any additional provisions.
The signature line says that if an individual other than the participant signs the form for the participant, that individual's relationship to the participant is indicated.
Article III says no part of the funds may be invested in life insurance contracts or in collectibles, apart from the exception in section 408(m)(3) for certain coins and bullion.