Article I: employee eligibility
Choose full eligibility or limited eligibility with current and prior compensation amounts (not to exceed $5,000) and years, and an option to exclude employees under a collective bargaining agreement.
5304-SIMPLE
Savings Incentive Match Plan for Employees of Small Employers (SIMPLE)--Not for Use With a Designated Financial Institution
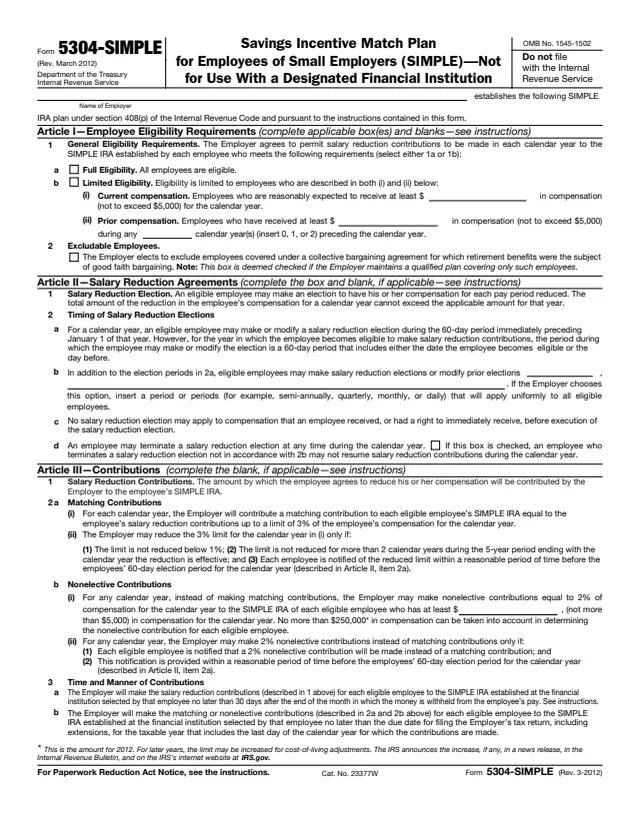
Form 5304-SIMPLE, Savings Incentive Match Plan for Employees of Small Employers (SIMPLE), Not for Use With a Designated Financial Institution, is a model plan document. The instructions say it is a document that an employer may use to establish a SIMPLE IRA plan described in section 408(p), under which each eligible employee is permitted to select the financial institution for his or her SIMPLE IRA.
Pages 1 and 2 hold the plan itself: employee eligibility, salary reduction agreements, contributions, other provisions, definitions, withdrawal procedures and the effective date. Page 3 holds a Model Notification to Eligible Employees and a Model Salary Reduction Agreement, and pages 4 to 6 hold the instructions. The form says "Do not file with the Internal Revenue Service." The employer keeps it with its records.
An employer that wants all contributions to go first to a financial institution it designates uses Form 5305-SIMPLE instead. You can fill out Form 5304-SIMPLE free in your browser on this page and download the result without an account.
Choose full eligibility or limited eligibility with current and prior compensation amounts (not to exceed $5,000) and years, and an option to exclude employees under a collective bargaining agreement.
The 60-day election period before January 1, an optional blank for extra election periods, and a box that stops an employee who ends an election from resuming that year.
Salary reduction contributions, a matching contribution up to 3% of compensation, or a 2% nonelective contribution instead, and the time limits for depositing each.
Vesting, withdrawal and rollover rules, definitions of compensation and employee, a space for withdrawal procedures, the effective date, and the employer's signature.
A Model Notification to Eligible Employees with the employer's contribution election, and a Model Salary Reduction Agreement where the employee sets the amount and names a financial institution.
Enter the employer's name on the first line. The instructions say the plan is considered adopted when all applicable boxes and blanks are completed and the employer has executed it.
Check 1a for full eligibility, or check 1b and insert $5,000 or a lower amount (including zero) and 2 or fewer years. Check item 2 to exclude collectively bargained employees.
Optionally insert extra election periods in item 2b and check item 2d. In Article III, item 2b(i), the instructions say to insert $5,000 to impose that requirement, or a lower amount.
Attach or insert withdrawal procedures. In Article VII, the instructions say to insert January 1 of the year, or for a first SIMPLE IRA plan any date from January 1 to October 1. Then sign and date.
Before each 60-day election period, give eligible employees the notification and a summary description, which can be a completed copy of pages 1 and 2. The page 3 model notification states which contribution the employer will make.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Do not file with the Internal Revenue Service." The instructions say to keep it with the employer's records.
The instructions say salary reduction contributions are deposited no later than the 30th day of the month following the month the amounts would otherwise have been payable, and point to Department of Labor rules that can require earlier deposit.
Article III says matching or nonelective contributions are made no later than the due date for filing the employer's tax return, including extensions.
The instructions say no annual return such as Form 5500 or Form 5500-EZ is filed for the plan, but active participants and salary reduction contributions are reported on Form W-2.
The instructions list a penalty of $50 per day for failing to give the employee notification, and $50 per day on a financial institution for each failure to give the summary description, unless due to reasonable cause.
The dollar limits printed on this revision are stated for 2012, and the form says later years may be increased for cost-of-living adjustments.
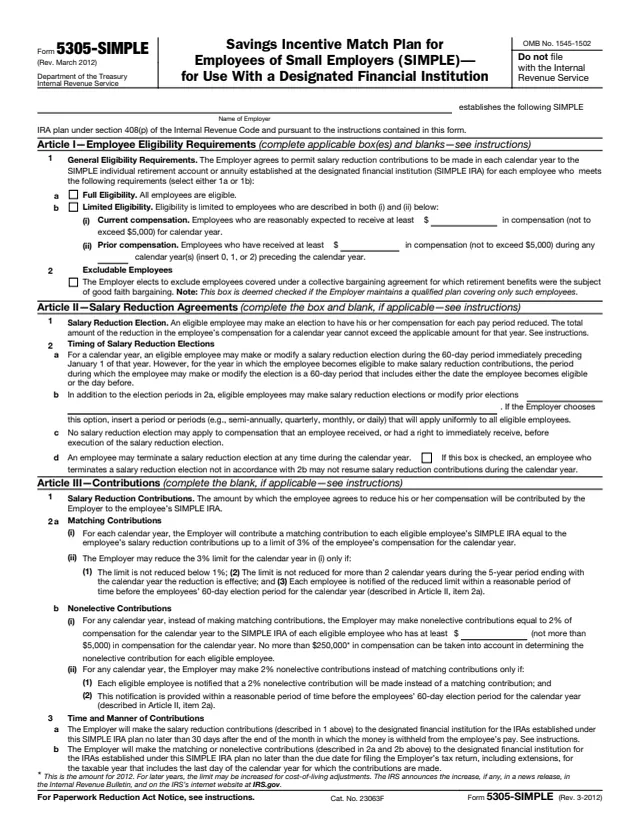
5305-SIMPLE
32 fields, 6 pages
5305-SEP
7 fields, 2 pages
5500-EZ
78 fields, 2 pages
W-2
568 fields, 11 pages
The employer completes and signs the plan. Employees use the model notification and salary reduction agreement on page 3, and each employee's financial institution supplies withdrawal procedures for the summary description.
No tool matches that search.
No. The form says do not file it with the Internal Revenue Service. The instructions say to keep it with the employer's records.
With Form 5304-SIMPLE each eligible employee picks the financial institution. The instructions say Form 5305-SIMPLE is used when all contributions first go to a financial institution the employer designates.
The employer fills in the boxes and blanks and signs it. Employees complete the Model Salary Reduction Agreement on page 3.
Article III provides a matching contribution up to 3% of compensation, which can be reduced to no lower than 1% under set conditions, or a 2% nonelective contribution instead.
The instructions say January 1 of the year, unless it is the first year the employer adopts any SIMPLE IRA plan, when any date from January 1 to October 1 may be used.
The instructions say an employer that used the March 2002, August 2005 or September 2008 version is not required to use this version.