Article I: eligibility
Full eligibility or limited eligibility by current and prior compensation, and an option to exclude employees under a collective bargaining agreement.
5305-SIMPLE
Savings Incentive Match Plan for Employees of Small Employers (SIMPLE)-for Use With a Designated Financial Institution
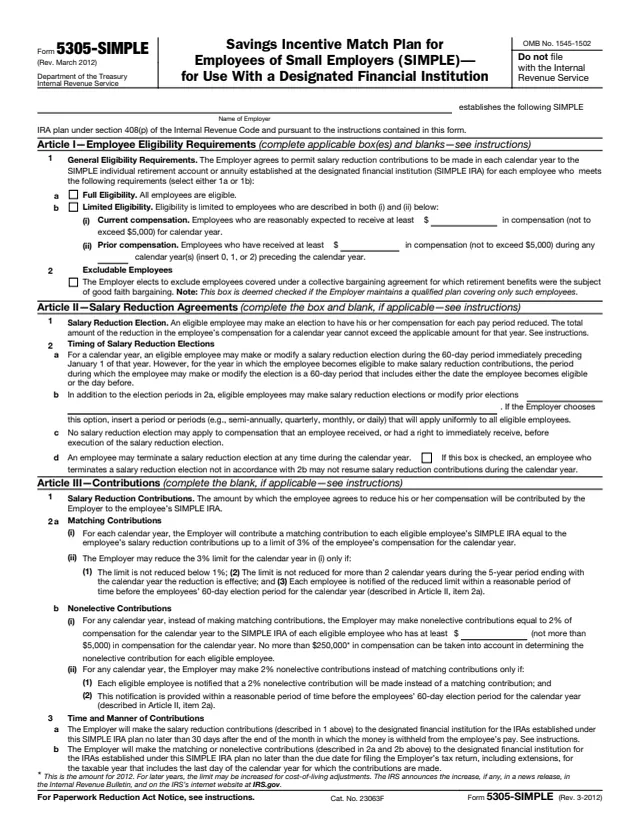
Form 5305-SIMPLE is, in the instructions' words, "a model Savings Incentive Match Plan for Employees of Small Employers (SIMPLE) plan document that an employer may use in combination with SIMPLE IRAs to establish a SIMPLE IRA plan described in section 408(p)." In this version, all contributions go to one designated financial institution, which deposits them to the SIMPLE IRA of each eligible employee.
The employer completes the boxes and blanks, and the instructions say the plan is considered adopted once it has been executed by the employer and the designated financial institution. Page 3 holds a Model Notification to Eligible Employees and a Model Salary Reduction Agreement.
The form says "Do not file with the Internal Revenue Service," and the instructions say to keep it with the employer's records. The dollar limits printed on the form are the amounts for 2012. You can fill out Form 5305-SIMPLE free in your browser on this page and download it without an account.
Full eligibility or limited eligibility by current and prior compensation, and an option to exclude employees under a collective bargaining agreement.
The salary reduction election, the 60-day election periods, optional extra periods and the rules for ending an election.
Salary reduction contributions, a matching contribution up to 3% of compensation or a 2% nonelective contribution, and when each is deposited.
Full vesting, no withdrawal restrictions, no cost for transfers, the 25% additional tax rule in the first 2 years, and definitions of compensation and employee.
The financial institution's withdrawal and transfer procedures, the plan's effective date, and signature blocks for the employer and the designated financial institution.
A Model Notification to Eligible Employees and a Model Salary Reduction Agreement for each employee to sign.
Enter the employer's name on the first line, which states that the employer establishes the SIMPLE IRA plan under section 408(p).
Check 1a for full eligibility, or check 1b and, per the instructions, insert $5,000 or a lower amount (including zero) and 2 or fewer years. Check item 2 to exclude collective bargaining employees.
Optionally insert extra election periods in 2b, such as semi-annually, quarterly, monthly or daily. Check 2d to keep an employee who ends an election outside 2b from resuming that year.
In item 2b(i), the instructions say to insert $5,000 to impose the compensation requirement for nonelective contributions, or a lower amount to cover more employees.
The instructions say to insert January 1 of the applicable year, unless this is the first year any SIMPLE IRA plan is adopted. Then any date from January 1 to October 1 of that year may be used.
The employer and the designated financial institution sign. Before the 60-day election period, employees get the notification and a summary description, such as a completed copy of pages 1 and 2.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says not to file it with the Internal Revenue Service. The instructions say to keep it with the employer's records.
The instructions say employees are notified before their 60-day election period, and that failing to provide the notification brings a penalty of $50 per day until it is provided, unless due to reasonable cause.
The instructions say salary reduction contributions are deposited no later than the 30th day of the month after the month the amounts would have been paid in cash, and point to Department of Labor rules at 29 CFR 2510.3-102.
The instructions say no Form 5500 or Form 5500-EZ is filed for the plan, but active participants and salary reduction contributions are reported on Form W-2.
The $250,000 compensation limit, the $11,500 salary reduction limit and the $2,500 catch-up for employees 50 or older are the 2012 amounts. The form says later years may be increased for cost-of-living adjustments.
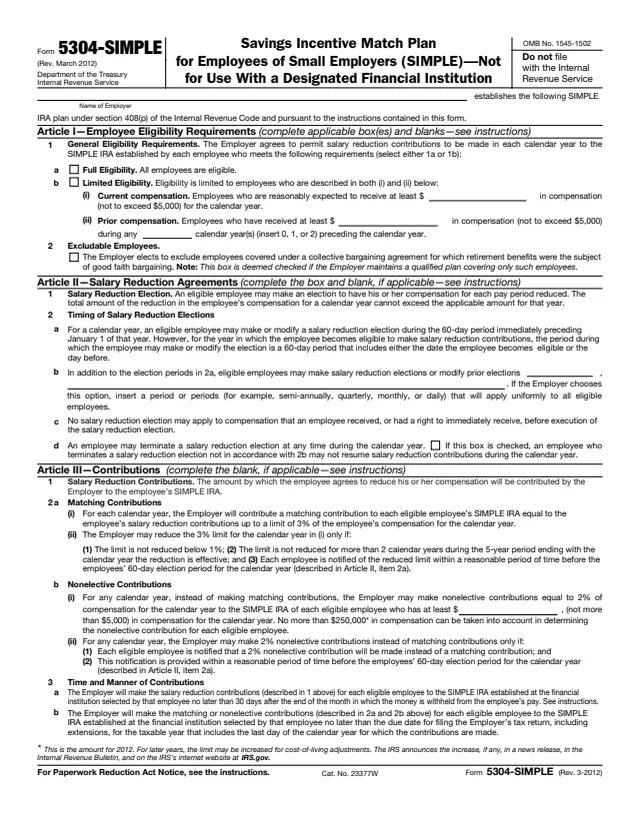
5304-SIMPLE
32 fields, 6 pages
W-2
568 fields, 11 pages
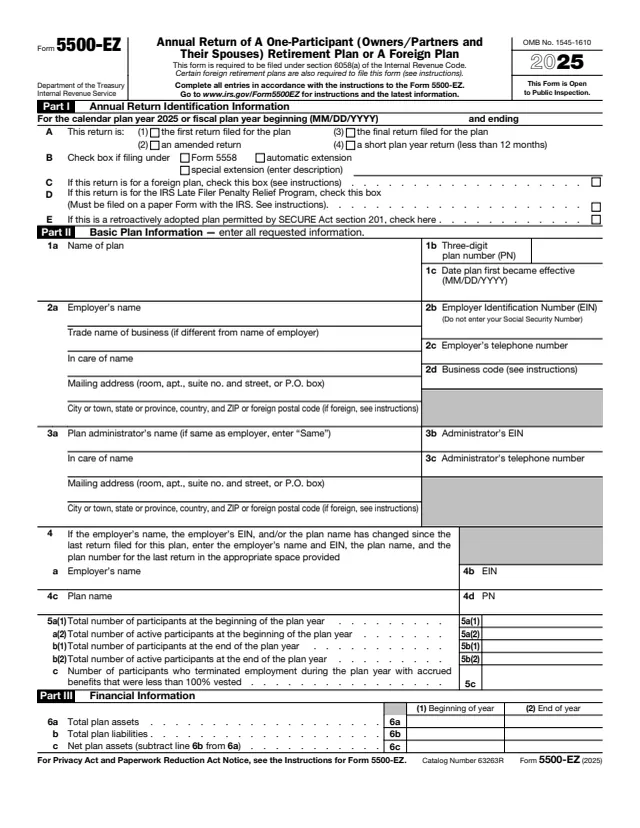
5500-EZ
78 fields, 2 pages
5305-SEP
7 fields, 2 pages
5305-S
9 fields, 2 pages
It is an employer's plan document, signed by the employer and by the designated financial institution. Employees use only the model documents on page 3.
No tool matches that search.
No. The form says not to file it with the Internal Revenue Service, and the instructions say to keep it with the employer's records.
Form 5305-SIMPLE uses one designated financial institution for all contributions. The instructions say to use Form 5304-SIMPLE to let each eligible employee choose the financial institution.
The instructions list two requirements: no more than 100 employees who earned $5,000 or more in the last calendar year, and no other qualified plan during the year, with some exceptions.
Either a match of salary reduction contributions up to 3% of compensation, which can be lowered to no less than 1% for no more than 2 years in 5, or a 2% nonelective contribution.
The instructions say it is adopted when all appropriate boxes and blanks are completed and it has been executed by the employer and the designated financial institution.
They are the 2012 amounts. The form says later years may be increased for cost-of-living adjustments, which the IRS announces.
The instructions say a plan set up with the March 2002, August 2005 or September 2008 version is not required to use this version.