Page 1 heading
Filer and applicant names and numbers, principal business activity code, tax year of change, contact person, fax or encrypted email option, consolidated group and Form 2848 boxes, applicant type and type of change.
3115
Application for Change in Accounting Method
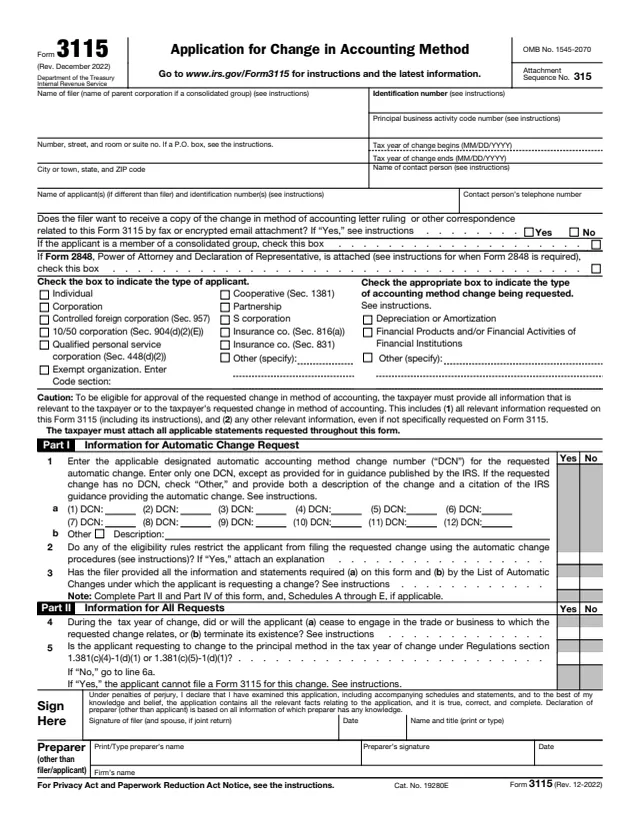
Form 3115, Application for Change in Accounting Method, is filed to request a change in either an overall method of accounting or the accounting treatment of any item. Applicants range from individuals to corporations, partnerships, S corporations, exempt organizations, cooperatives, insurance companies and controlled foreign corporations.
The instructions describe two routes. Under the automatic change procedures, an applicant that timely files and complies is granted consent to change, subject to IRS review, and no user fee is required. The List of Automatic Changes is in Rev. Proc. 2022-14, and each change carries a designated change number (DCN). Under the non-automatic procedures, the IRS National Office issues a letter ruling and a user fee applies.
The form says the taxpayer must provide all relevant information, even information not specifically requested, and attach all applicable statements. Most changes also require a section 481(a) adjustment in Part IV. You can fill out Form 3115 free in your browser on this page and download the result without an account.
Filer and applicant names and numbers, principal business activity code, tax year of change, contact person, fax or encrypted email option, consolidated group and Form 2848 boxes, applicant type and type of change.
Lines 1 to 3: the designated automatic accounting method change number (DCN) or Other with a description and citation, eligibility rules, and whether all required information is provided.
Lines 4 to 19: examinations, audit protection, Appeals and federal court, prior and pending changes, the item and present and proposed methods, the legal basis, and gross receipts for prior years.
Lines 20 to 24: why the automatic procedures do not apply, related documents, reasons for the change, consolidated group methods and the user fee amount.
Lines 25 to 29: cut-off basis, the amount of the adjustment as an increase or decrease in income, any remaining prior adjustment, the 1-year election and intercompany items.
A, change in overall method; B, deferral method for advance payments, cost offset and AFS income inclusion; C, LIFO; D, long-term contracts, inventories and section 263A; E, depreciation or amortization.
The instructions say that unless published guidance provides otherwise, an applicant eligible for the automatic change procedures for the requested year of change files under them. Otherwise the non-automatic procedures may be available.
Enter the filer's name and identification number: an SSN or ITIN for individuals, an EIN for others. Enter the 6-digit principal business activity code for a business, the tax year of change, and check the applicant type and the type of change.
Enter the DCN for the change, only one unless IRS guidance provides otherwise. If the change has no DCN, check Other and give a description and the citation of the IRS guidance.
Answer the questions on examinations, Appeals and prior changes within the 5 tax years ending with the year of change. Attach descriptions of the item, the present and proposed methods and the trade or business.
For a non-automatic request, attach the related documents and a statement of reasons, and enter the user fee on line 24a. The instructions say user fees are paid through Pay.gov, and automatic requests pay none.
Enter the section 481(a) adjustment and attach its computation. The instructions say the period is generally 1 tax year for a negative adjustment and 4 tax years for a positive one. Complete each schedule that applies, such as Schedule E for depreciation.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The original is attached to the filer's timely filed (including extensions) federal income tax return for the year of change. A signed copy goes to the IRS no earlier than the first day of the year of change and no later than the date the original is filed.
By mail: Internal Revenue Service, Ogden, UT 84201, M/S 6111. By private delivery service: Internal Revenue Service, 1973 N. Rulon White Blvd., Ogden, UT 84201, Attn: M/S 6111. By fax: 844-249-8134.
Filed during the tax year for which the change is requested with the IRS National Office: Internal Revenue Service, Attn: CC:PA:LPD:TSS, P.O. Box 7604, Benjamin Franklin Station, Washington, DC 20044, or by secure fax at 877-773-4950.
The instructions say the IRS does not send acknowledgments for automatic change requests, and normally acknowledges a non-automatic request within 60 days after receiving it.
The instructions say a filer that does not file on time generally gets no extension except in unusual and compelling circumstances, though an automatic 6-month extension may be available for automatic change requests.
Schedule E instructions say not to file Form 3115 to make or revoke an election under section 167, 168, 179, 197, or former section 1400I, to change the placed-in-service date, or to change salvage value, with limited exceptions.
970
48 fields, 4 pages

2848
92 fields, 2 pages

1120
481 fields, 6 pages

1065
440 fields, 6 pages

1040
199 fields, 2 pages
The instructions separate the filer, the entity or person required to file Form 3115, from the applicant, whose accounting method is being changed. Often they are the same.
No tool matches that search.
The instructions say it is filed to request a change in either an overall accounting method or the accounting treatment of any item.
Not for automatic change requests. The instructions say a user fee is required for each applicant in a non-automatic request, with amounts in Rev. Proc. 2023-1, paid through Pay.gov.
A designated automatic accounting method change number. It identifies an automatic change from the List of Automatic Changes and is entered on Part I, line 1.
The instructions say a separate Form 3115 is ordinarily filed for each accounting method change, though some concurrent changes can or must share one form.
The amount entered in Part IV to account for the change. The instructions say it is generally taken into account over 1 tax year if negative and 4 tax years if positive.
Not for automatic change requests. For non-automatic requests, the instructions say an acknowledgment is normally sent within 60 days.