Name and identification
Name and identification number of the filer, and of the applicant if different. The instructions say an individual uses a social security number and others use an employer identification number.
970
Application To Use LIFO Inventory Method
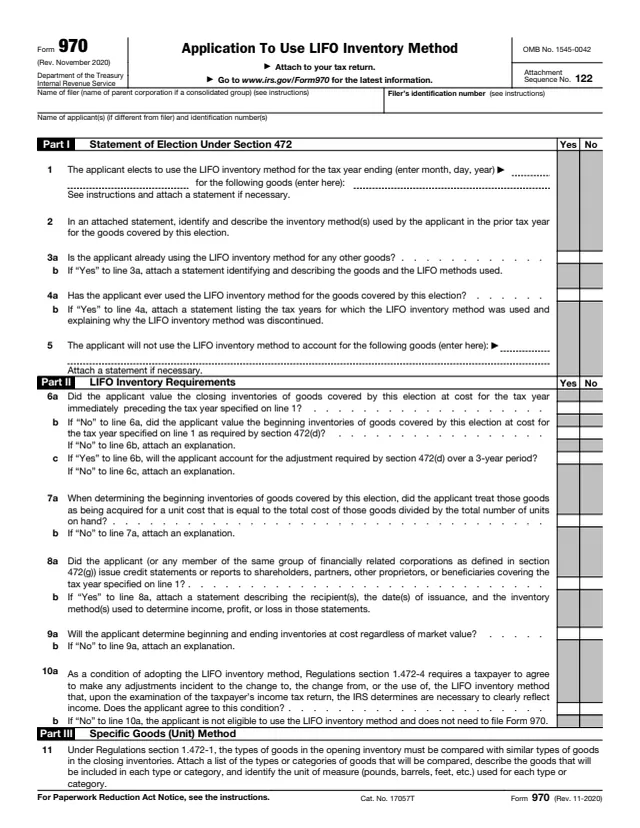
Form 970 is the Application To Use LIFO Inventory Method. The About page says it is filed with the income tax return to elect to use the last-in, first-out (LIFO) inventory method described in Internal Revenue Code section 472. The instructions add that an election statement giving the same information can be filed instead.
The form has six parts. Part I is the statement of election, Part II covers the LIFO inventory requirements, Parts III, IV and V cover the specific goods (unit), dollar-value and inventory price index computation (IPIC) methods, and Part VI asks for other information. Many lines call for attached statements.
The instructions for the form are printed on pages 3 and 4 of the same PDF. You can fill out Form 970 free in your browser on this page and download it without an account.
Name and identification number of the filer, and of the applicant if different. The instructions say an individual uses a social security number and others use an employer identification number.
Lines 1 to 5: the tax year and goods covered, the prior inventory method, any other goods already on LIFO, any past use of LIFO, and goods that will not use LIFO.
Lines 6 to 10: valuing inventories at cost, the section 472(d) adjustment, unit cost of beginning inventories, credit statements or reports, and agreement to the Regulations section 1.472-4 condition.
Lines 11 and 12 for the specific goods (unit) method, and lines 13 to 17 for the dollar-value method, including how items are defined and goods are pooled.
Lines 18 to 21: double-extension or link-chain IPIC, the BLS price index table, the 10 percent method, and any representative month.
Line 22 for the method of determining the cost of inventory items, and line 23 on IRS consent to change the method of valuing inventories.
The instructions say Parts I, II and VI are completed on every Form 970, and Parts III, IV and V as applicable to the LIFO method chosen.
Enter the filer's name and identification number on the first line. If the form is filed on behalf of the applicant, enter the applicant's name and number on the second line.
Enter the tax year LIFO will first be used and list the inventory items it covers. The instructions ask for an attached detailed analysis of inventories at the beginning and end of that year and the beginning of the preceding year.
Answer the yes and no questions on lines 6 to 10 and attach the explanations they call for. The form says that if the answer to line 10a is No, the applicant is not eligible to use LIFO and does not need to file Form 970.
Complete Part III, IV or V for the method used. For line 15, the instructions ask for enough information to justify the pooling method; for line 16, a statement when the method is link-chain, index or other.
If Form 3115 was filed and IRS consent was received for the line 1 tax year, the instructions say not to attach the approval letter but to retain a copy for the records.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 970 (or a similar statement) with the tax return for the first tax year the LIFO method is intended to be used. The form says to attach it to the tax return.
If the return was filed without the election, the instructions say it can be made on an amended return within 12 months of the date the original return was filed, with "Filed pursuant to section 301.9100-2" written at the top of Form 970, at the same address as the original return.
The instructions say LIFO is irrevocable once adopted unless the IRS allows a change to another method, and point to Form 3115 and its instructions for the automatic and non-automatic change procedures.
The instructions say an eligible small business can elect the simplified dollar-value LIFO method under sections 474(c) and 448(c)(3) without IRS consent, and can revoke it only with IRS consent.
The instructions describe a LIFO recapture amount a C corporation includes in gross income when it used LIFO before an S corporation election takes effect or transfers LIFO inventory to an S corporation.
The instructions say that in general, the filer of Form 970 is the applicant, the taxpayer electing LIFO for its inventory. It is attached to that taxpayer's income tax return.
No tool matches that search.
The instructions say it is filed with the tax return for the first tax year the LIFO method is intended to be used.
Yes. The instructions say an election statement that gives the same information requested on Form 970 can be filed instead.
The instructions describe making the election on an amended return within 12 months of the original filing date, with "Filed pursuant to section 301.9100-2" written at the top of Form 970.
The instructions say the LIFO method is irrevocable unless the IRS allows a change to another method. They point to Form 3115, Application for Change in Accounting Method.
The instructions say Parts I, II and VI, plus Parts III, IV and V as applicable to the method used.
No separate booklet is listed on the About Form 970 page. The General and Specific Instructions are printed on pages 3 and 4 of the form.