Partnership information
Name, EIN, principal business activity code, address, contact person and telephone number, and a box to check if Form 2848 is attached.
15254
Request for Section 754 Revocation
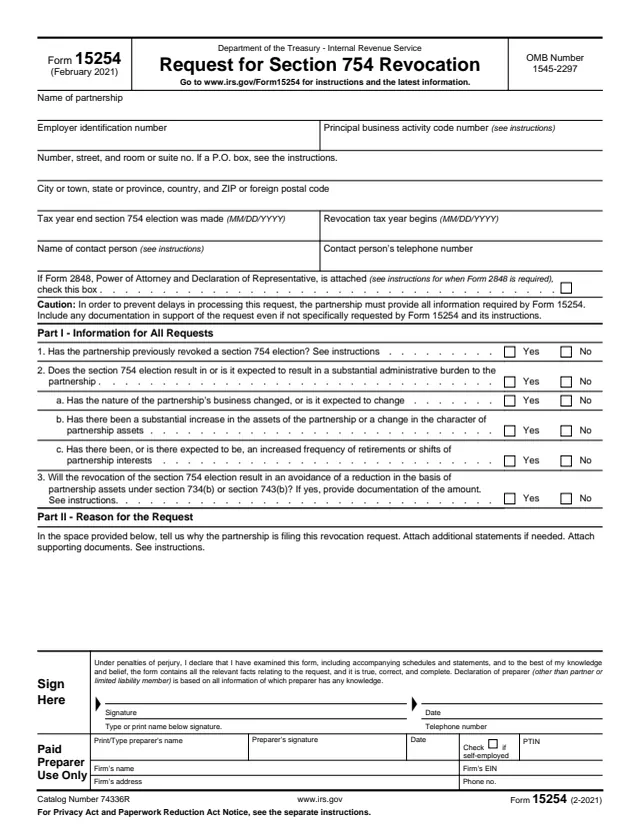
Form 15254 is the Request for Section 754 Revocation. The IRS About page says to file it to request a section 754 revocation. The instructions explain that a section 754 election lets a partnership adjust the basis of partnership property when property is distributed or a partnership interest is transferred, and that it applies to all later years unless revoked.
The form is filed by the partnership. Each partnership seeking consent to revoke its election files its own separate Form 15254, and the partnership receives a letter approving or denying the request. The instructions list examples that may be considered sufficient reason, such as a change in the nature of the business, a substantial increase in partnership assets, a change in the character of the assets, or more frequent retirements or shifts of partnership interests.
The instructions also say no revocation is approved when its purpose is primarily to avoid stepping down the basis of partnership assets upon a transfer or distribution. You can fill out the PDF free in your browser on this page and download it without an account.
Name, EIN, principal business activity code, address, contact person and telephone number, and a box to check if Form 2848 is attached.
The tax year end in which the section 754 election was made, and the date the revocation tax year begins, both as MM/DD/YYYY.
Yes or no questions on any prior revocation and on whether the election causes a substantial administrative burden, with lines 2a to 2c on business changes, asset changes and shifts of partnership interests.
Whether revocation would avoid a reduction in the basis of partnership assets under section 734(b) or 743(b). The form asks for documentation of the amount with a yes answer.
Space to explain why the partnership is filing, with attached statements and supporting documents.
Signature under penalties of perjury with name, date and telephone number, then the Paid Preparer Use Only area.
Enter the partnership's name, EIN and 6-digit principal business activity code from the Form 1065 instructions. Include the suite or room number in the address, or C/O and a third party's name if mail goes to them.
The instructions say the election year is the last day of the tax year for which the election was attached to the return, and the revocation tax year begins on the first day of the year the revocation is to take effect.
Name a partner or LLC member authorized to sign, or the authorized representative. If the contact is someone else, the instructions say to attach Form 2848.
Answer each yes or no question. For yes answers on lines 1, 2, 2a, 2b and 2c, the instructions say to give the effective date or an explanation in Part II.
Give the rationale for the revocation. The instructions list supporting documents such as a copy of the original election, section 734(b) or 743(b) calculations, partner Schedules K-1, depreciation schedules and valuations.
A partner or LLC member signs and dates. A paid preparer signs and completes the Paid Preparer Use Only area. A partner, member or employee who completes the form leaves that area blank.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the application is filed no later than 30 days after the close of the partnership taxable year for which the revocation is intended to take effect, citing Regulations section 1.754-1(c)(1).
Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0011.
The partnership receives a letter approving or denying the request, at the address listed on Form 15254.
A partnership that wants letters about the request by fax attaches a statement asking for this, listing the authorized names and fax numbers.
The form cautions that the partnership provide all information it requires, and include supporting documentation even if not specifically requested, to prevent processing delays.
If the partnership's mailing address or responsible party changes after filing its return, the instructions point to Form 8822-B.

1065
440 fields, 6 pages

1065
111 fields, 1 page

2848
92 fields, 2 pages
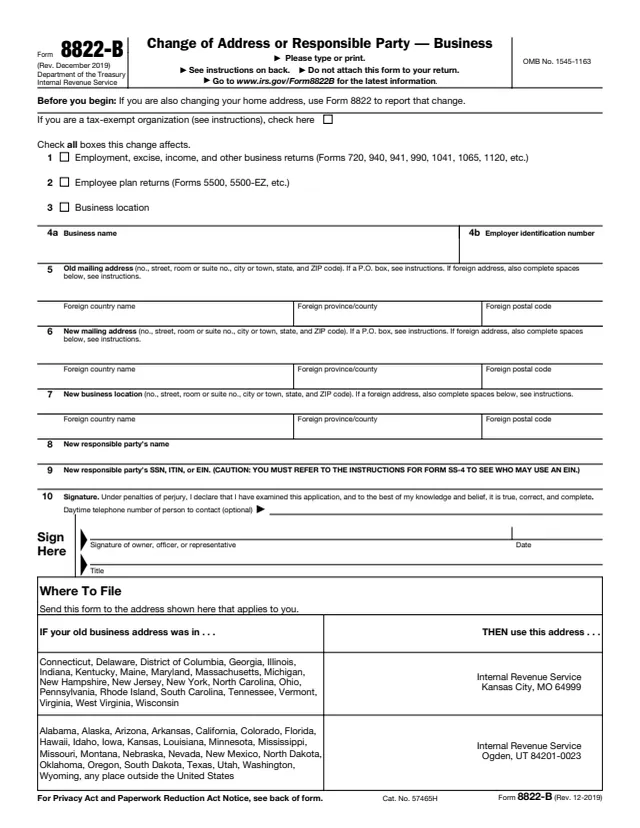
8822-B
22 fields, 2 pages
15288
24 fields, 2 pages
The instructions say that, in general, Form 15254 is filed by the partnership. It is not a form an individual files.
No tool matches that search.
The partnership. The instructions say each partnership seeking consent to revoke its section 754 election files its own separate Form 15254.
The instructions say no later than 30 days after the close of the partnership taxable year with respect to which the revocation is intended to take effect.
The instructions give Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0011.
Examples include a change in the nature of the business, a substantial increase in assets, a change in the character of assets, or more frequent retirements or shifts of partnership interests, causing an increased administrative burden.
The instructions say no application is approved when the purpose is primarily to avoid stepping down the basis of partnership assets upon a transfer or distribution.
The instructions say it is attached when the contact person is not a partner or LLC member authorized to sign, and for the IRS to discuss the request with a representative.